Walmart (WMT.US) 1Q27: Fundamentals intact; EBIT growth needed to support momentum
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
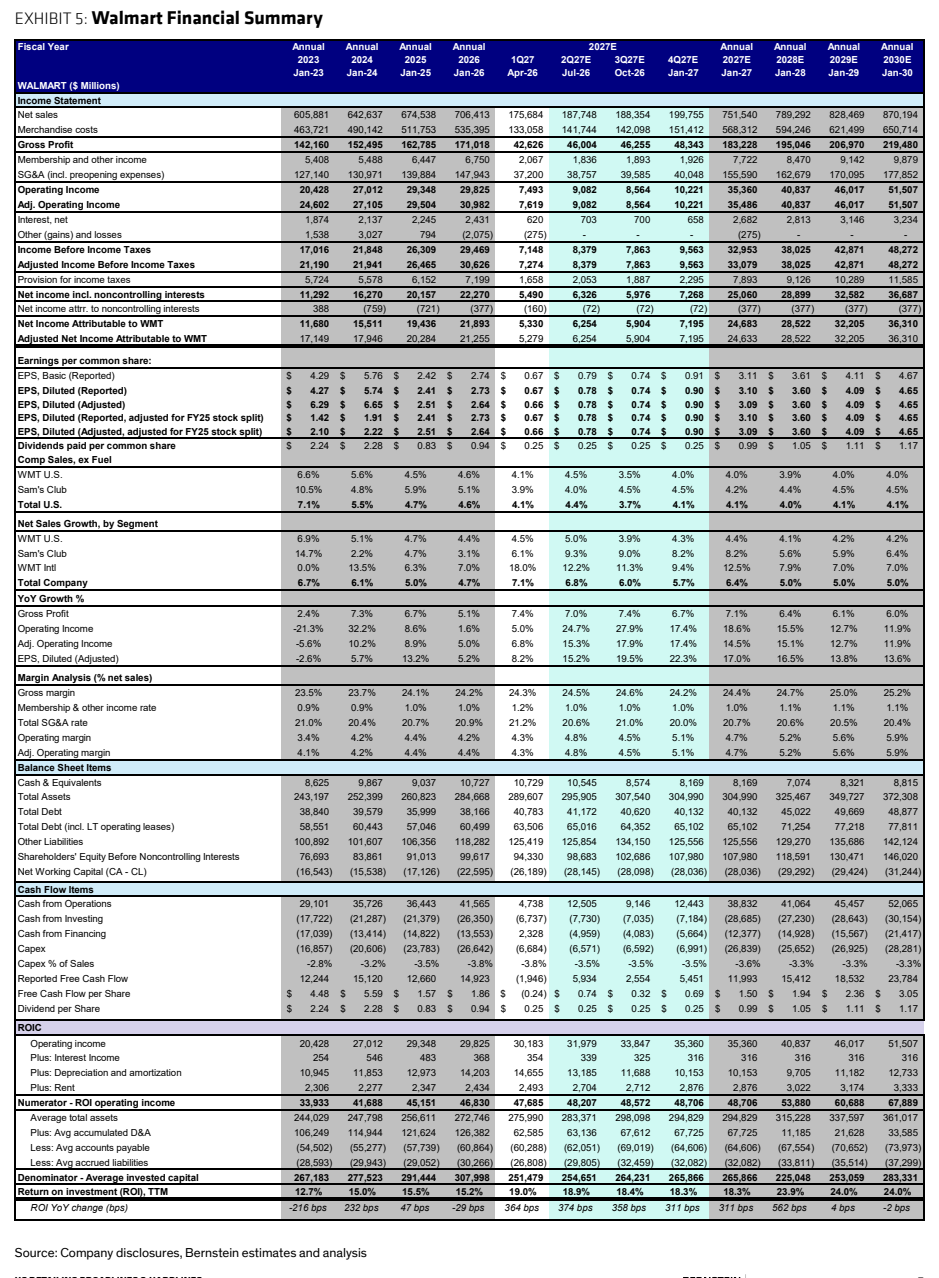
Bernstein maintains an Outperform rating on Walmart with a target price of $145. In the first quarter of fiscal 2027, constant-currency net sales grew 5.7%, surpassing prior guidance of 3.5%-4.5%. However, adjusted constant-currency EBIT growth came in at 5.1%, below the guided range of 4%-6%, largely due to a 250 basis point drag from fuel costs.
Walmart US comparable sales, excluding fuel, grew 4.1%, slightly beating the market consensus of 4.0%. The gross margin stood at 24.3%, with adjusted EPS of $0.66, aligning with expectations. Global advertising revenue surged 37%, driven by a 44% increase in Walmart Connect within the US market. The company also reaffirmed its conservative FY27 guidance.
Bernstein argues that the recent share price pullback has been overdone. The firm anticipates that e-commerce profitability improvements, declining delivery costs, and easier year-over-year comparisons will drive mid-double-digit EBIT growth. Furthermore, if energy inflation persists, Walmart stands to benefit from its value positioning and potential consumer trade-down. Bernstein lowered its adjusted FY27 EPS estimate to $3.09 and FY28 to $3.60.
Key exhibits
Exhibit 1
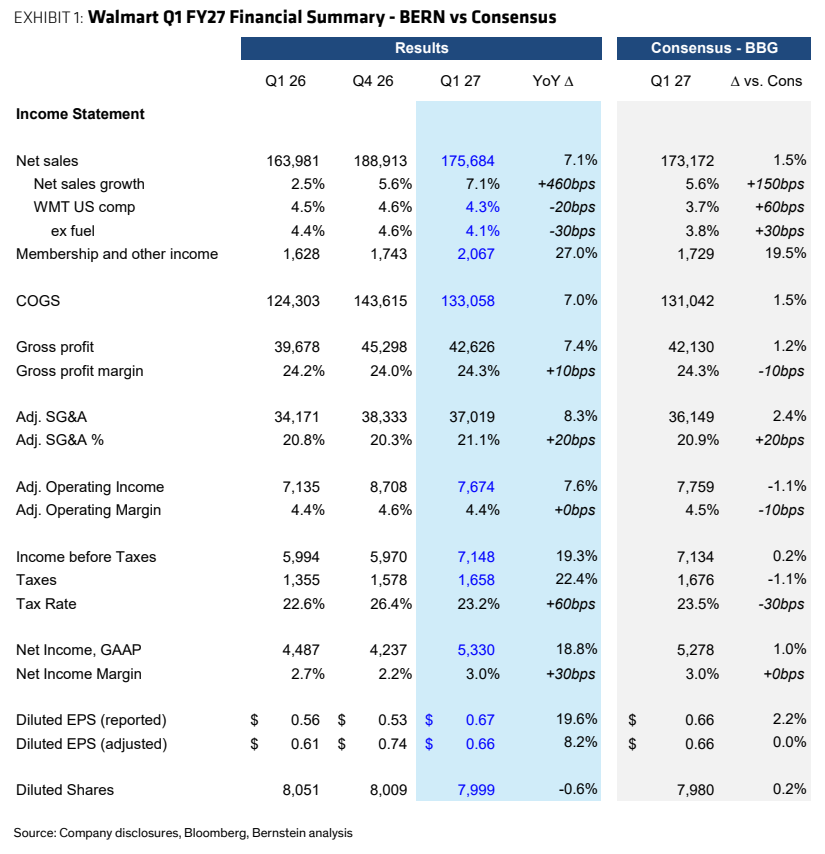
Exhibit 2
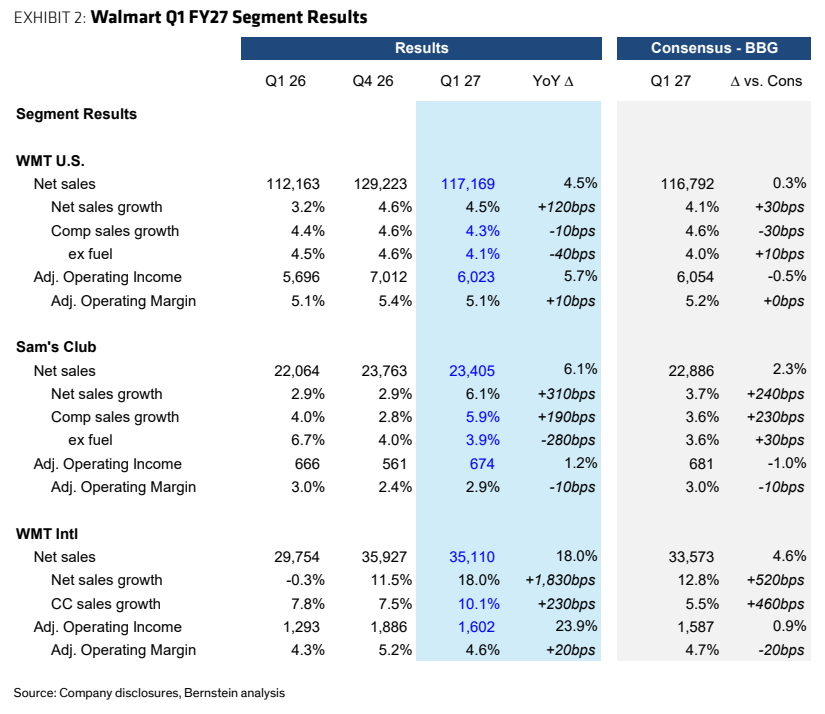
Exhibit 3
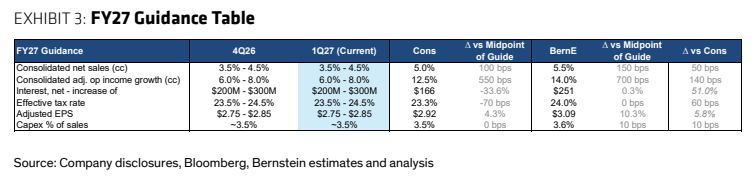
Exhibit 4
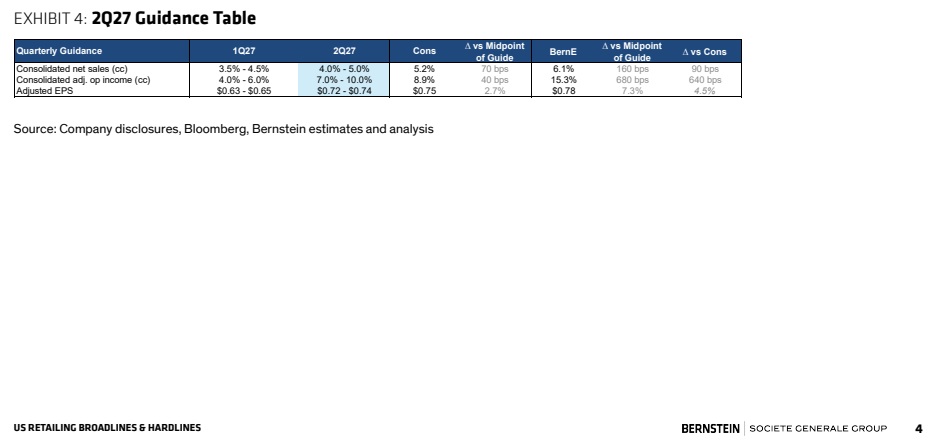
Exhibit 5