China Data Centers: Highlights from China AI Computing Industry Ecological Development Conference
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Key Views
Domestic AI accelerators may exceed 50% shipment share by 2026, led by Huawei and Alibaba T-Head. However, performance and ecosystem gaps persist versus overseas H800-class solutions. Domestic chips offer 40%-50% lower capex per IT kW but deliver only 10%-30% of compute capacity, making cost per unit of compute 2-4x higher. Major CSPs still rely on imported chips for 70%-90% of current capacity. Policy support remains strong, with Bloomberg estimating roughly RMB 2 trillion in data center investment over five years.
Outlook
Token operations are emerging as a new business model layer. Sustainable API margins will hinge on low-cost electricity, network scheduling, and concurrency stability rather than raw model capability alone. Cross-border token export via inbound data processing zones may unlock niche opportunities.
Recommended Securities
- VNET — Buy
- GDS — Buy
- Range Intelligent — Buy
- Shanghai Athub — Neutral
- Beijing Sinnet — Sell
Key exhibits
Exhibit 1
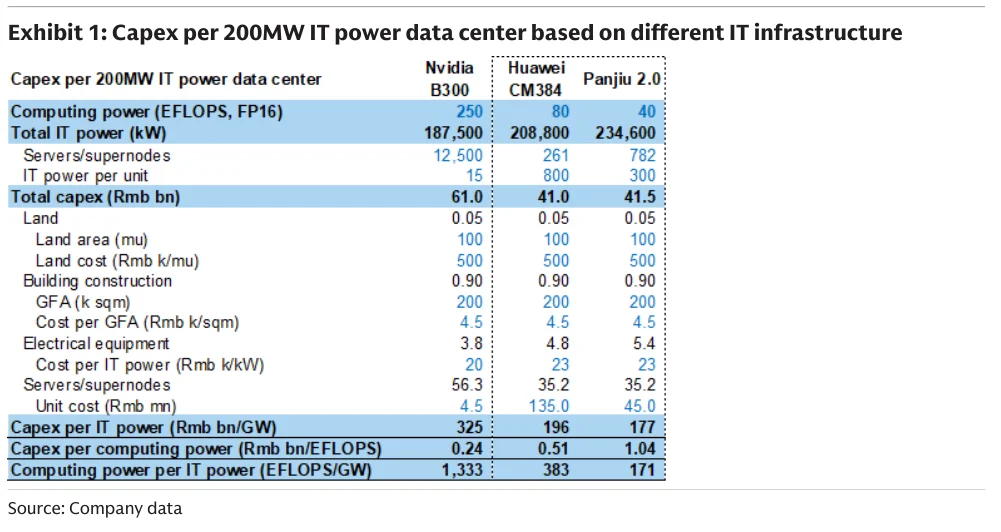
Exhibit 2

Exhibit 3

Exhibit 4
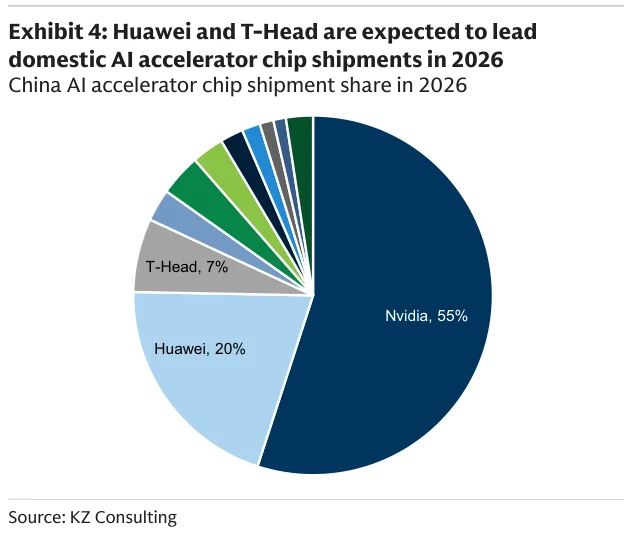
Exhibit 5

Exhibit 6
