UBS US Equity Strategy: Low Bar, Strong Q3 Earnings Revisions
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
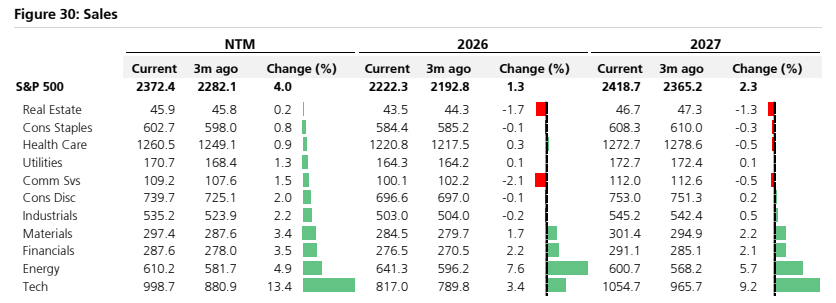
UBS notes the bar for S&P 500 third-quarter earnings is low, with nearly 70% of companies expected to post slower EPS growth than in the second quarter. The market has already priced in deceleration, with the median stock down 7% since the Q2 reporting season, yet revisions remain strong: aggregate estimates were raised 1.8%, including a 3.6% upgrade for the Tech+ group. UBS expects S&P 500 EPS to grow 26.3% year over year in Q3, approaching 30% if the historical beat of roughly 3% repeats. Tech+ remains the core driver, with EPS growth moderating from 54.2% to 46.7%, while ex-Tech+ growth slows to 14.6% from 24.8%. UBS forecasts hyperscaler cloud revenue up 60% year over year, above the 56% consensus, and projects $574 billion of cloud revenue over the next four quarters, roughly 15% above consensus. Quantitative screens flag 40 potential positive surprise names, including Gen Digital, Matador Resources, Arthur J. Gallagher, Kontoor Brands and StandardAero, and 20 negative surprise names such as Dow, Eversource, Evercore, ADP and Graphic Packaging (GPK). Derivatives strategy points to volatility opportunities in tech, financials, materials and energy.
Key exhibits
Exhibit 1
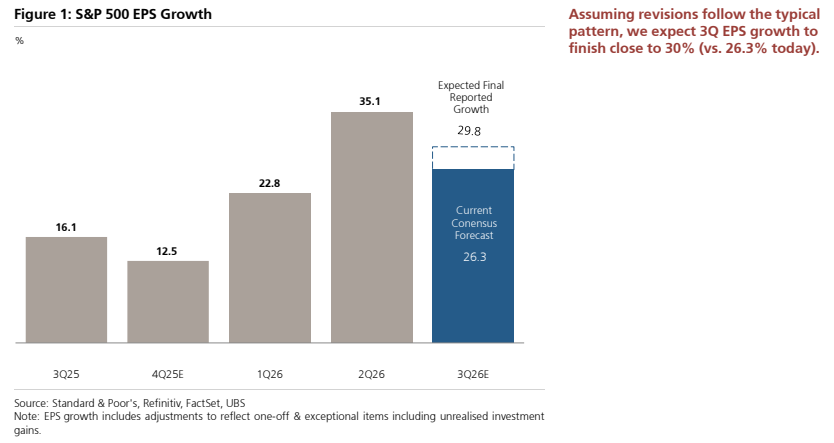
Exhibit 2
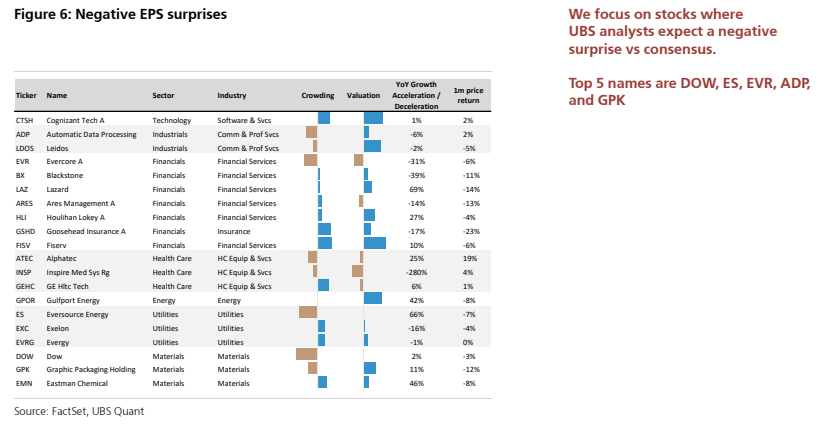
Exhibit 3
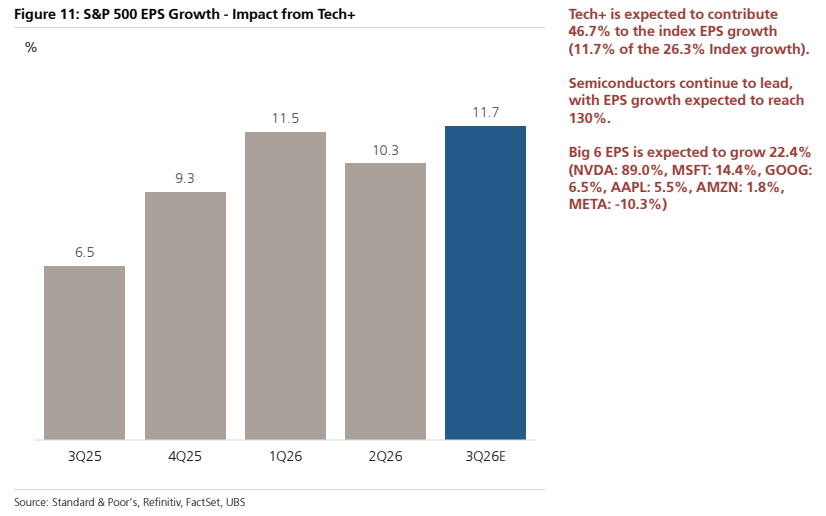
Exhibit 4
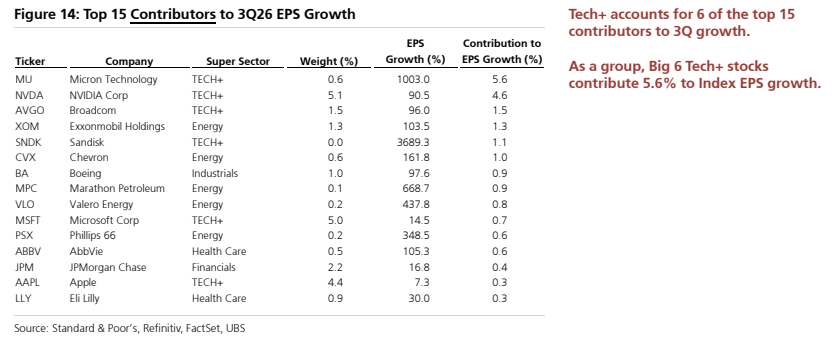
Exhibit 5
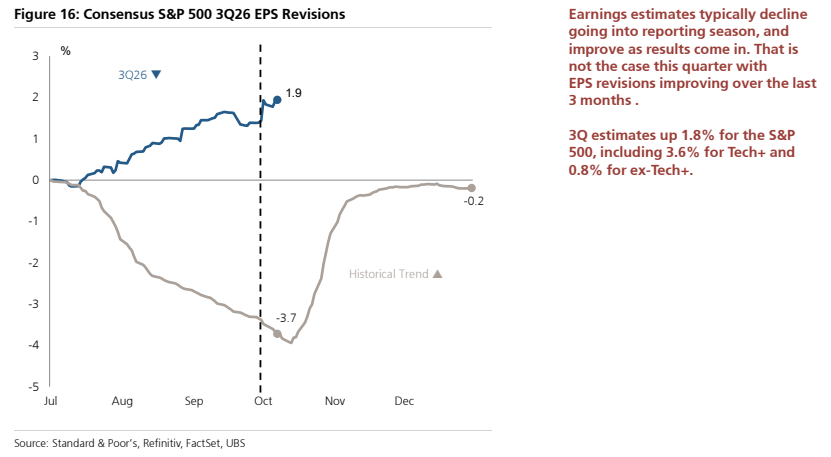
Exhibit 6
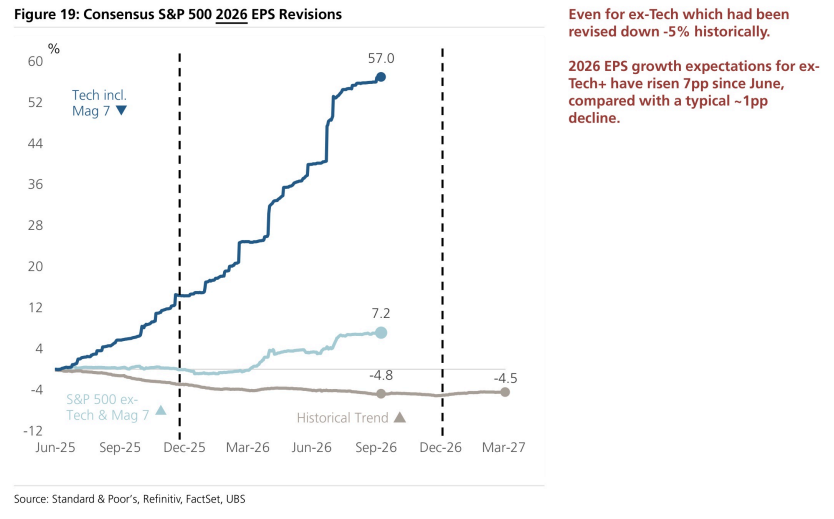
Exhibit 7
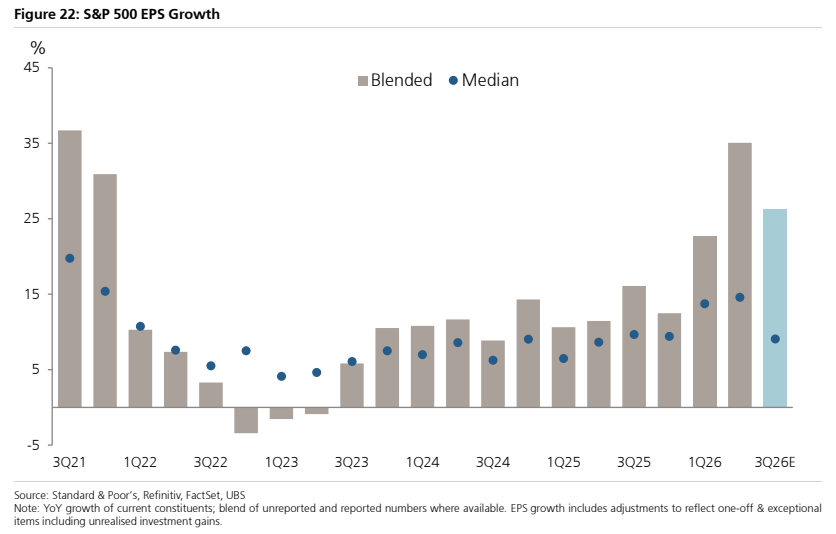
Exhibit 8

Exhibit 9
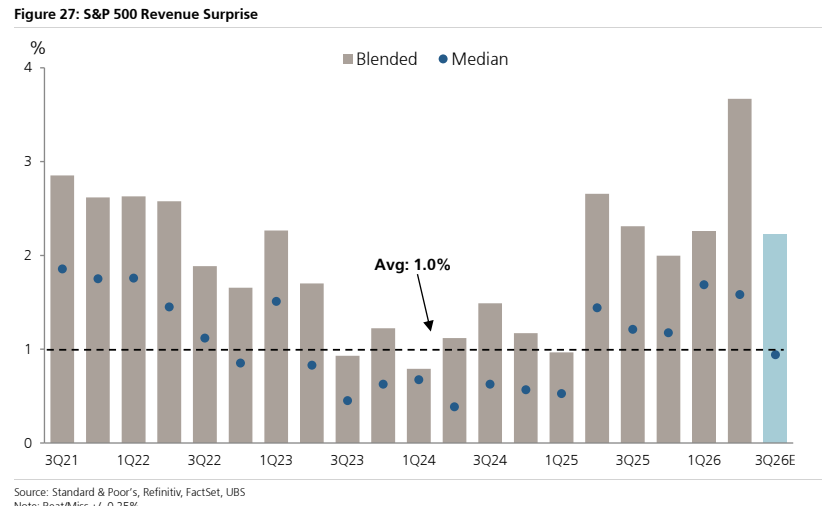
Exhibit 10