Citi: Signs of Stabilization in China's June Data
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
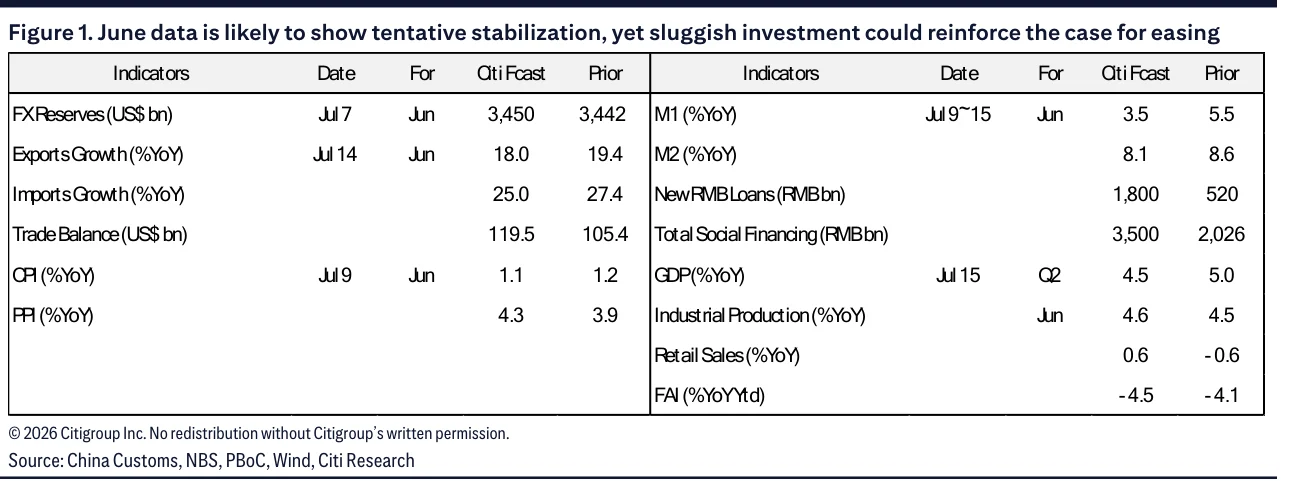
Citi forecasts that China's June data will show initial economic stabilization, though structural divergence will persist. The bank maintains its Q2 GDP growth forecast at 4.5% year-over-year, potentially marking the lowest point for the year. Exports continue to lead growth, supported by an AI super-cycle, while retail sales are expected to return to positive territory at 0.6% year-over-year due to accelerated trade-in subsidies. Industrial production is projected to hold steady at 4.6%.
Conversely, fixed asset investment remains a primary drag, with the year-to-date contraction potentially widening to -4.5%. Credit data is also anticipated to disappoint; new RMB loans are estimated at 1,800 billion RMB, down from 2,240 billion RMB a year earlier, reinforcing the rationale for further monetary easing.
Inflation metrics reflect mitigating cost pressures. Citi expects CPI at 1.1% and PPI at 4.3%, with oil price shocks largely fading. However, rising coal prices and AI-related input costs may limit PPI deflation improvement. Export strength is notable, with June exports projected to surge 18.0% year-over-year and imports up 25.0%, yielding a trade surplus of approximately $119.5 billion.
The data profile suggests stabilization without a broad-based recovery. Consequently, the upcoming Politburo meeting may maintain its current tone, favoring targeted consumption support over massive stimulus. The July Loan Prime Rate decision stands as the earliest policy test to see if weakening investment and credit trends prompt additional monetary accommodation.
Key exhibits
Exhibit 1