JPMorgan Equity Strategy: Q3 Earnings Preview - Reassuring Earnings Delivery
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
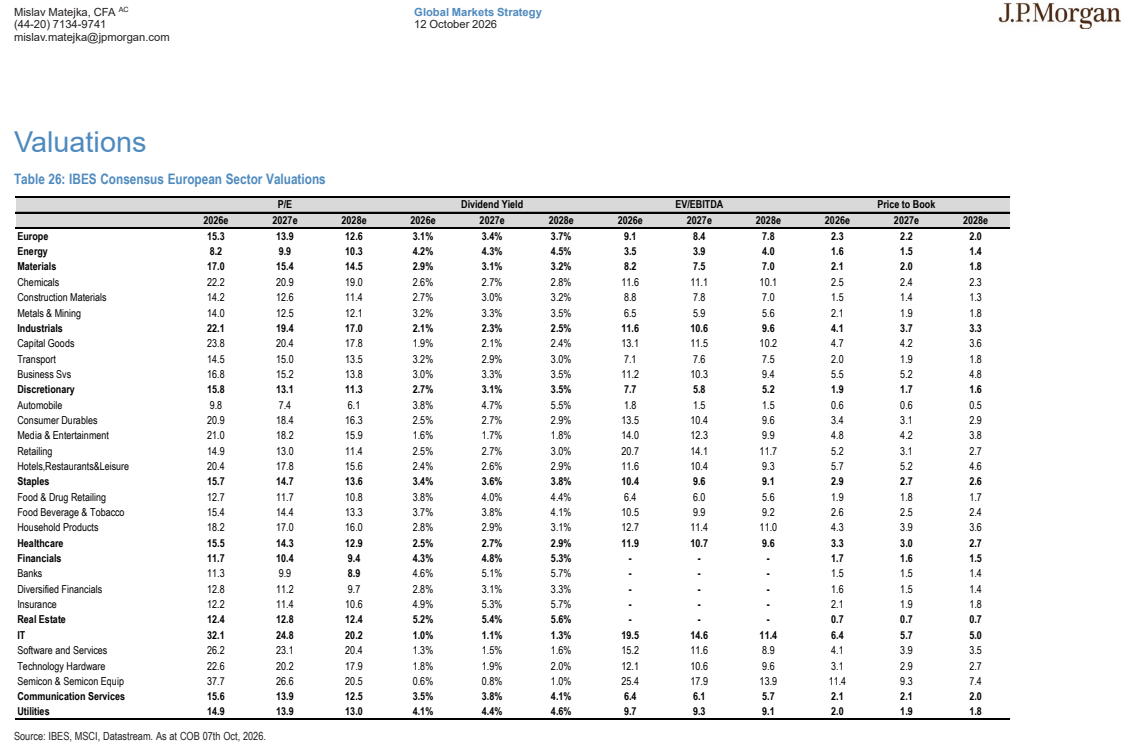
JPMorgan argues the third-quarter earnings season should support equities despite recent volatility. Global PMIs accelerated to multi-year highs in Q3, pointing to strong EPS delivery, and sentiment toward earnings is constructive. Headline consensus for S&P 500 Q3 EPS growth is 24%, but stripping out Meta's one-off tax adjustment and Nvidia and Micron lowers it to 15%, with median growth of just 8%. In Europe, expected EPS growth is 19%, or 11% excluding energy, with a median of 9%. European margin expansion is notable: 2026 EBIT/sales is projected at 14.4%, roughly 250bp above 2019, and 75% of CAC 40 revenue comes from outside France, underscoring resilience. JPMorgan favors technology, European semiconductors, banks, chemicals and industrials, seeing the earnings season—alongside expectations that bond yields are peaking and credit spreads stabilizing—as a catalyst for recovery from September's volatility, with banks poised to rebound if these conditions align. In energy it is Overweight UK supermajors, Eni and Galp and Underweight OMV; preferred capital goods names include Siemens Energy, Legrand, Alstom, Vestas, Weir and Epiroc. In chemicals it likes Novonesis, Umicore, Syensqo, Croda, Clariant, Akzo, Fuchs and Solvay, and is Underweight BASF, Wacker, Yara, Evonik, Brenntag, IMCD, DSM-Firmenich and Arkema.
Key exhibits
Exhibit 1
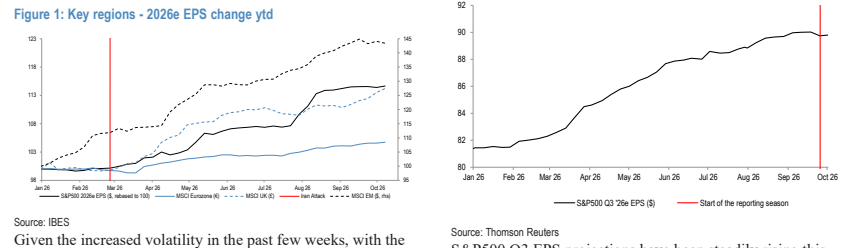
Exhibit 2

Exhibit 3

Exhibit 4
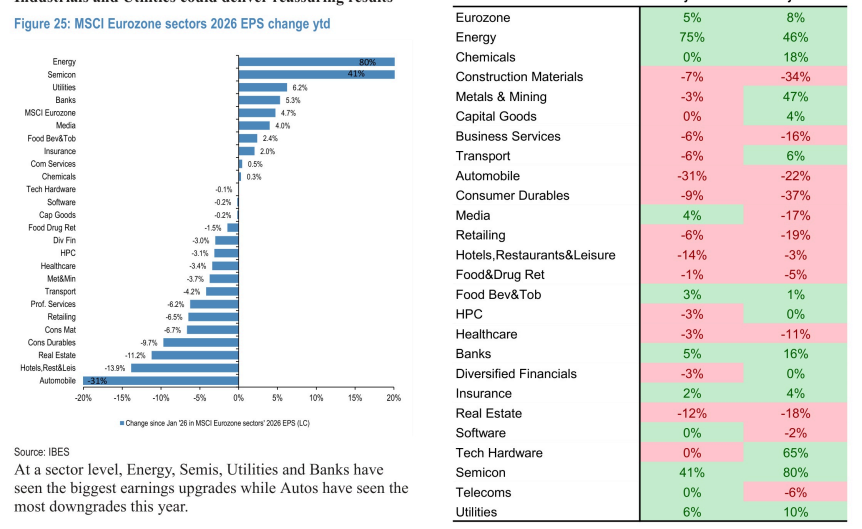
Exhibit 5

Exhibit 6

Exhibit 7

Exhibit 8

Exhibit 9