MedTech & HCIT: 2Q26 Chart Pack Preview: Mixed Fundamental Picture Meets Discounted Valuations
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Key Views
The report highlights three pressures: broad growth deceleration, maturing product cycles, and company-specific headwinds. The US surgical volume environment shows sequential improvement but remains unnormalized with no catch-up effect. Organic growth estimates are largely in line with or slightly below consensus, with notable exceptions: ABT (+60bps), ISRG (+70bps), and MDLN (+130bps). Aggregate 2Q26 organic growth improved slightly quarter-over-quarter, driven by Stryker's recovery from a cybersecurity disruption and a one-time inventory timing benefit at Solventum.
Outlook
Full-year guidance risk appears limited, as most companies have not built acceleration into forward estimates. Margin improvement is expected but is back-end weighted toward 4Q and depends on revenue scale and mix. Most key raw material costs are declining on a 30-day rolling basis, though DRAM prices surged 81.0% year-over-year. A modest earnings beat could trigger a short-term rebound, but sustained recovery requires more aggressive capital allocation, estimate recalibration, and pipeline visibility.
Recommended Securities
Goldman favors EW, OMDA, and PODD for quarterly upside potential, alongside ABT and MMED for constructive 2H26-2027+ narratives.
Key exhibits
Exhibit 1

Exhibit 2

Exhibit 3

Exhibit 4

Exhibit 5

Exhibit 6

Exhibit 7
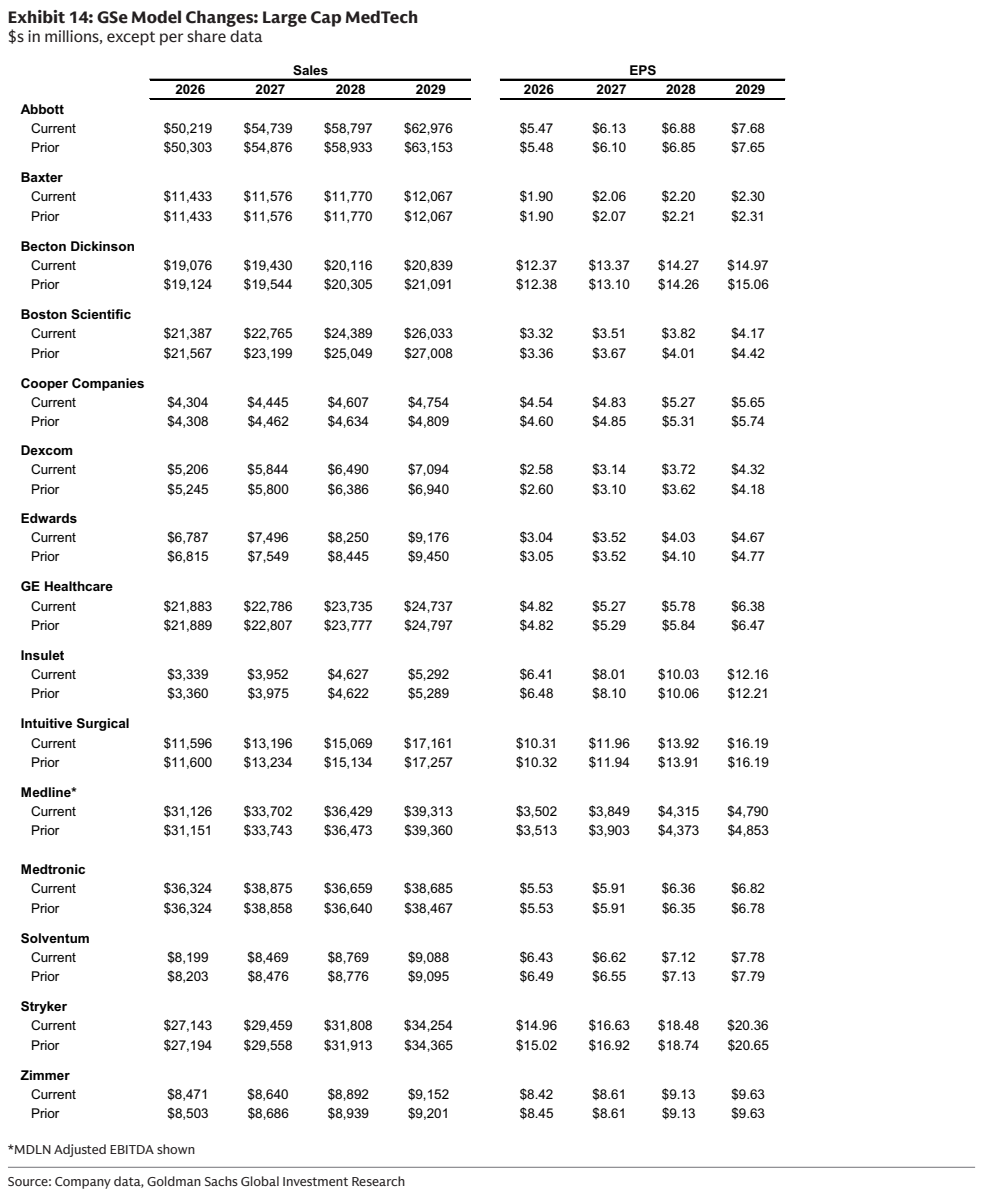
Exhibit 8
