J.P. Morgan: Wiwynn Corp (6669.TW) — Procurement Model Lifts Margin Profile; AI Ramps Set Up 2H26 Outperformance; Overweight
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
J.P. Morgan reiterates its Overweight rating on Wiwynn, asserting that a strategic shift in its business model will enhance profitability while robust artificial intelligence demand drives second-half outperformance. The analysis emphasizes that Wiwynn is actively transitioning from a traditional original design manufacturer framework toward a procurement-driven model. This strategic pivot is expected to materially improve both cash flow generation and overall profit margins.
Concurrently, the firm anticipates that surging AI server requirements will significantly elevate Wiwynn’s AI revenue contribution during the second half of 2026, positioning the company to outperform the broader market. This expected acceleration is underpinned by Wiwynn’s ongoing customer diversification strategy, which systematically reduces reliance on any single hyperscale client and mitigates associated concentration risks. Furthermore, the company demonstrates robust supply chain management capabilities, a critical advantage given the current intense demand for AI infrastructure components.
By blending an upgraded procurement framework with a diversified client base and operational excellence, Wiwynn is well-positioned for sustained growth. J.P. Morgan maintains its Overweight stance, though a specific target price is not detailed in the summary. The investment thesis pivots on margin expansion and AI-driven revenue acceleration entering late 2026.
Key exhibits
Exhibit 1
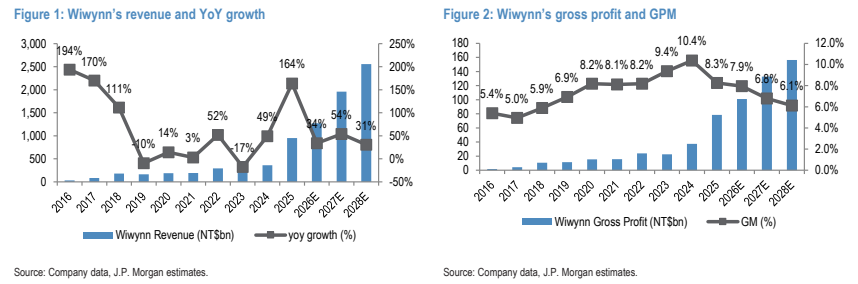
Exhibit 2

Exhibit 3

Exhibit 4
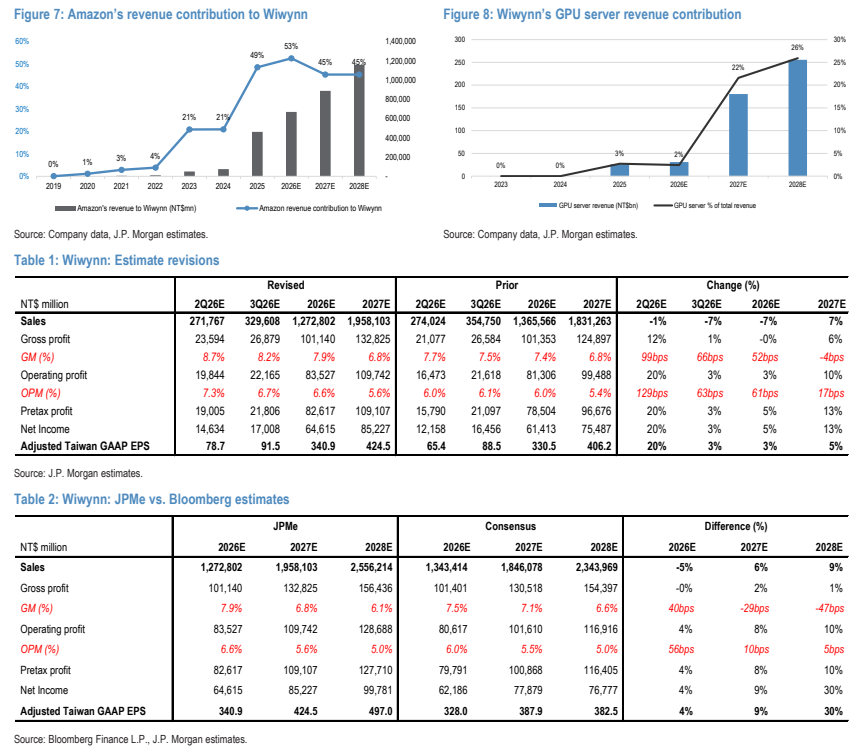
Exhibit 5
