Goldman Sachs on Insta360 (688775.SS): Near-Term Memory Cost Pressures, Long-Term Product Migration Drives Growth; Buy
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Goldman Sachs maintains a Buy rating on Insta360 (688775.SS), arguing that while rising memory costs will pressure near-term margins, a sustained product mix shift toward premium offerings will drive long-term growth.
Memory costs are projected to increase 30% year-over-year in 2026, pushing the gross margin down by two percentage points to 45%. Consequently, management guided for 15% revenue growth in 2026, below prior expectations of 20%. Inventory days also rose from 90 to 100 to support restocking.
However, the company is successfully migrating its portfolio from consumer-grade to professional-grade equipment. The mass production of 8K panoramic cameras targeting the professional film market is slated for the second half of 2026. Furthermore, AI software subscription revenue is expected to double its contribution, reaching 5% of total revenue, with the user base hitting 500,000 by year-end.
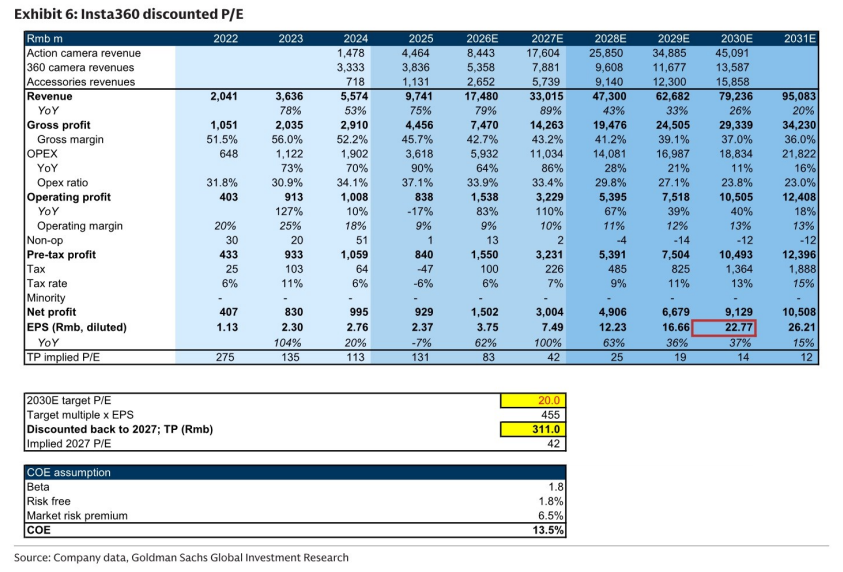
As memory costs normalize in 2027, gross margins are anticipated to recover to 47%. Combined with higher average selling prices from the premium shift, net profit is projected to grow 25% in 2027. The target price is based on 30 times 2027 PE, implying 20% upside. Key risks include further memory price surges, slower product migration, and foreign exchange volatility.
Key exhibits
Exhibit 1
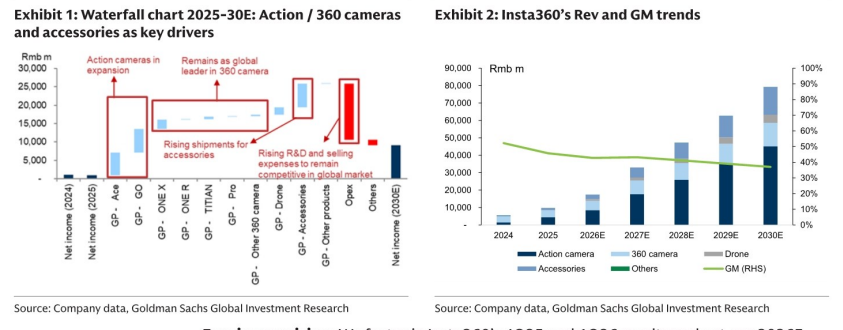
Exhibit 2
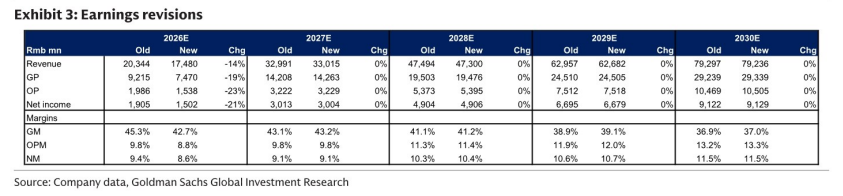
Exhibit 3

Exhibit 4
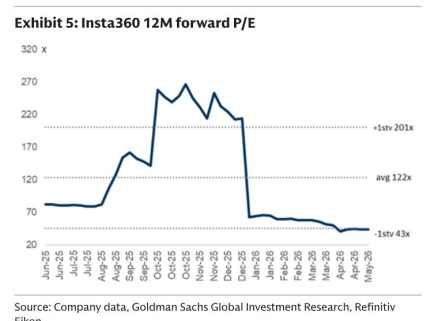
Exhibit 5