JPMorgan Kirby (KEX.US): Barges, Backlog and Aftermarket—Kirby's Next Phase of Growth; Initiated at Overweight with $200 End-2027 Target
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
JPMorgan initiates coverage of Kirby with an Overweight rating and a December 2027 price target of $200, implying roughly 40% upside. As the largest US inland tank barge operator, Kirby benefits from structurally tight supply—newbuild economics remain poor and the fleet has long stagnated—supporting utilization above 90%, pricing power and revenue visibility. Its Distribution & Services (KDS) segment offers differentiated growth on data-center-driven power demand, with a $1.0-1.5 billion backlog and a rising contribution from power generation. Margins should keep recovering as fuel and shipyard-related headwinds fade and spot pricing stays above contract rates, while the Infrastructure Investment and Jobs Act should improve inland waterway reliability. JPMorgan expects mid-to-high single-digit inland revenue growth in 2026 with mid-single-digit coastal growth, inland operating margins reaching the high-teens to low-20s percent range, and 2027 adjusted EPS of $8.22, with earnings compounding through pricing power and disciplined capital allocation.
Key exhibits
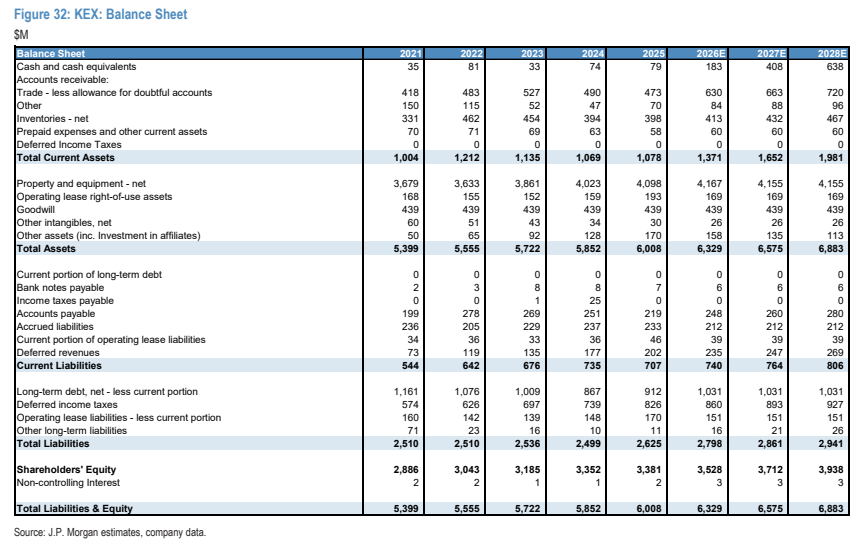
Exhibit 1
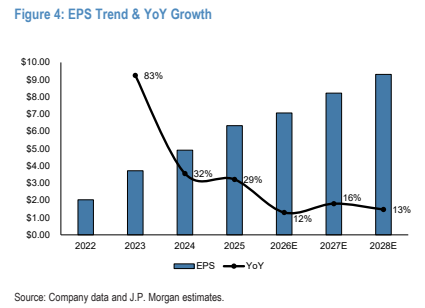
Exhibit 2
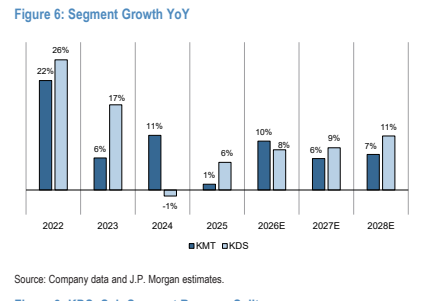
Exhibit 3
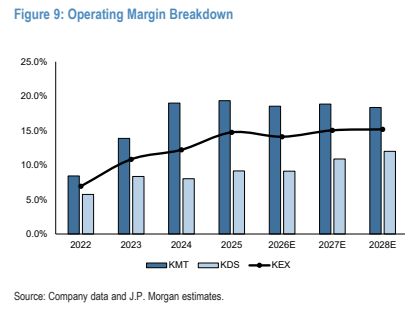
Exhibit 4
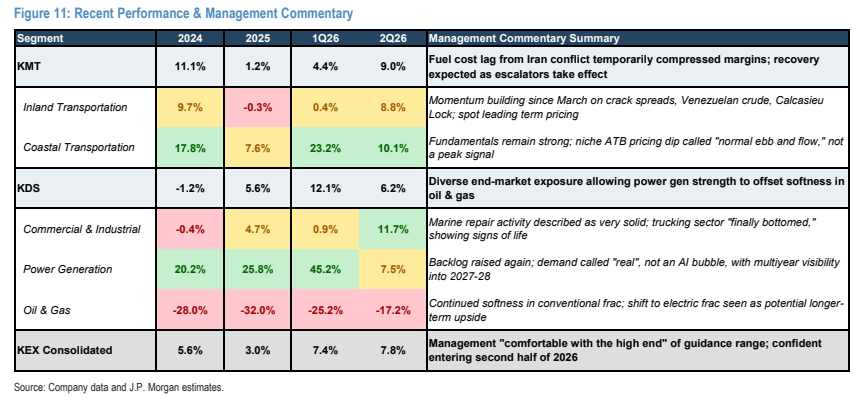
Exhibit 5
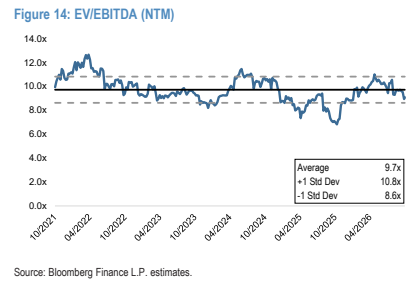
Exhibit 6
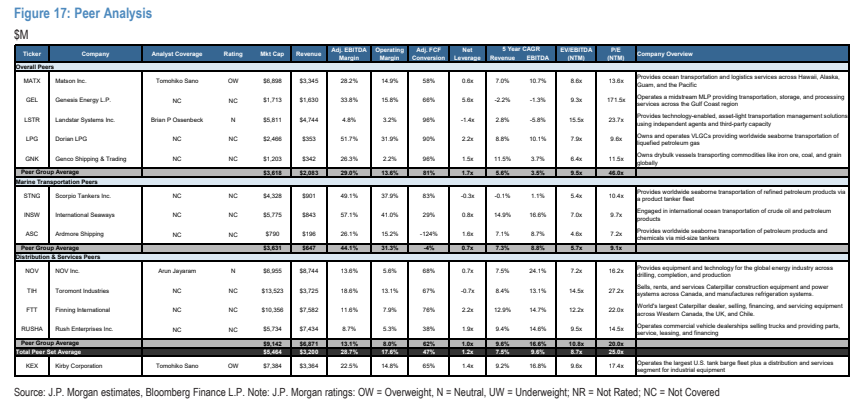
Exhibit 7
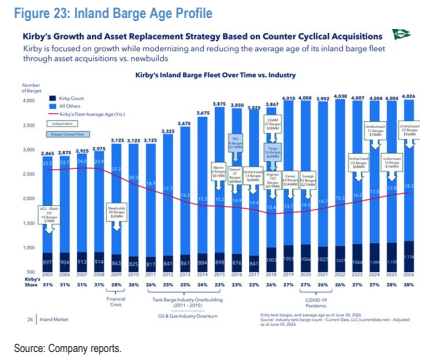
Exhibit 8
Exhibit 9