Morgan Stanley Greater China Materials: China Steel and Iron Ore Weekly Update
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
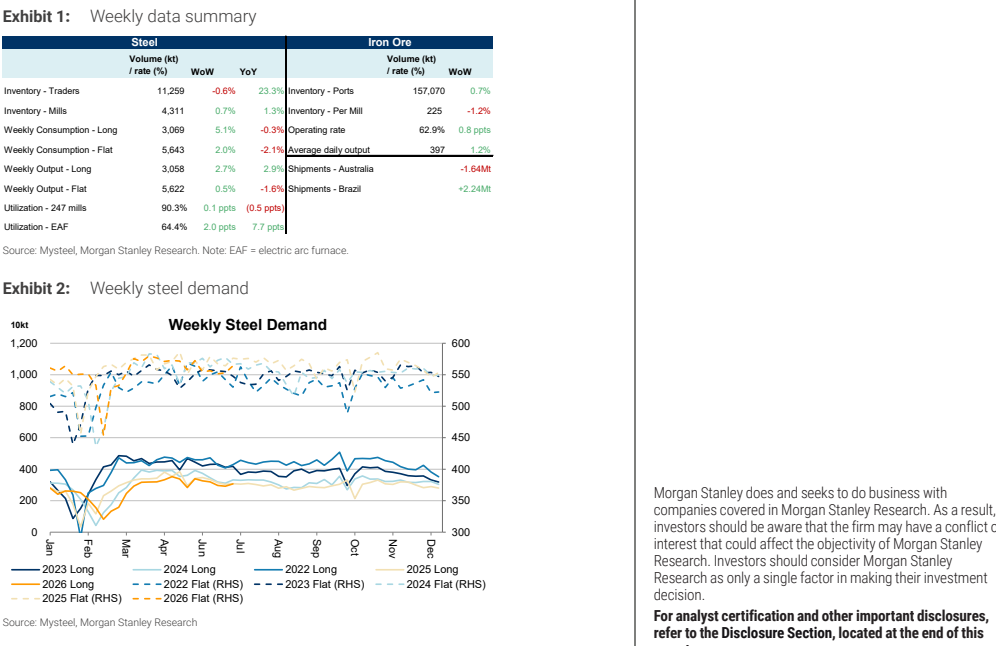
Morgan Stanley provides a cautious weekly assessment of China's steel and iron ore markets, noting that despite a modest 0.5% week-over-week rebound in steel production, output remains down 3.2% year-over-year. Demand remains fundamentally weak, and the pace of social inventory destocking has slowed, with the weekly decline narrowing by 1.2 percentage points.
On the raw materials side, iron ore prices rose 2.1% week-over-week, supported by supply disruptions from reduced Brazilian shipments. However, port inventories climbed 1.5% to 145 million tons, capping further upside. Downstream demand indicators stay subdued, with new real estate starts still falling 15% annually and infrastructure investment growth slowing to 4%. Additionally, the export order index dropped to 48.5, signaling weakening external demand.
The absence of new major policy stimulus limits the potential for an immediate fundamental recovery. Industry profitability continues to compress, with gross margins per ton of steel falling to 200 RMB. Scrap steel prices declined 1.5%, diminishing substitution effects, while coking coal prices held steady amid rising inventory pressures. Morgan Stanley maintains its cautious sector outlook, emphasizing the need to monitor upcoming demand recovery trends and potential policy shifts.
Key exhibits
Exhibit 1