Goldman Sachs: Alibaba Group (BABA) — Seizing the AI Agentic Opportunity
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Goldman Sachs views Alibaba as reaching a critical inflection point in the AI agent era, maintaining a Buy rating on the shares. Management recently unveiled several key products during the Alibaba Cloud Summit, including the flagship Qwen3.7-Max model and the Qwen Cloud platform. The new model is specifically designed for multi-agent collaboration and long-duration autonomous tasks, capable of running independently for up to 35 hours and managing over 1,000 tool calls. Additionally, Alibaba's chip division, T-Head, launched the Zhenwu M890 AI accelerator, which delivers triple the performance of its predecessor and has already shipped 560,000 units.
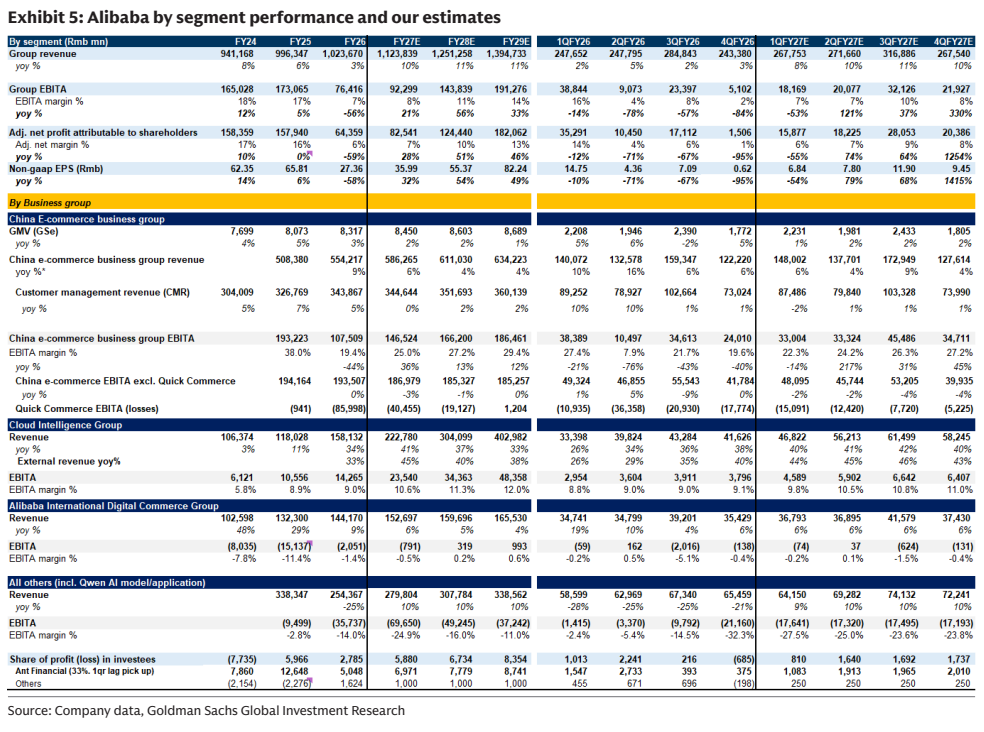
These technological advancements are expected to drive a significant acceleration in cloud revenue. Goldman Sachs forecasts cloud revenue growth of 40% year-over-year in the first quarter of fiscal 2027 and 41% for the full fiscal year, driven by enterprise adoption of token-consuming AI agents. Management's targets for MaaS Annual Recurring Revenue include RMB 10 billion by the June quarter and RMB 30 billion by the end of fiscal 2027.
Consequently, Goldman Sachs projects Alibaba's EPS will grow 32% and 54% in fiscal years 2027 and 2028, respectively. The firm maintains a Buy rating with a sum-of-the-parts target price of $186 for the US-listed shares and HK$180 for the Hong Kong-listed shares. Key downside risks include macroeconomic headwinds, slower retail monetization, and potential execution shortfalls in strategic investments.
Key exhibits
Exhibit 1
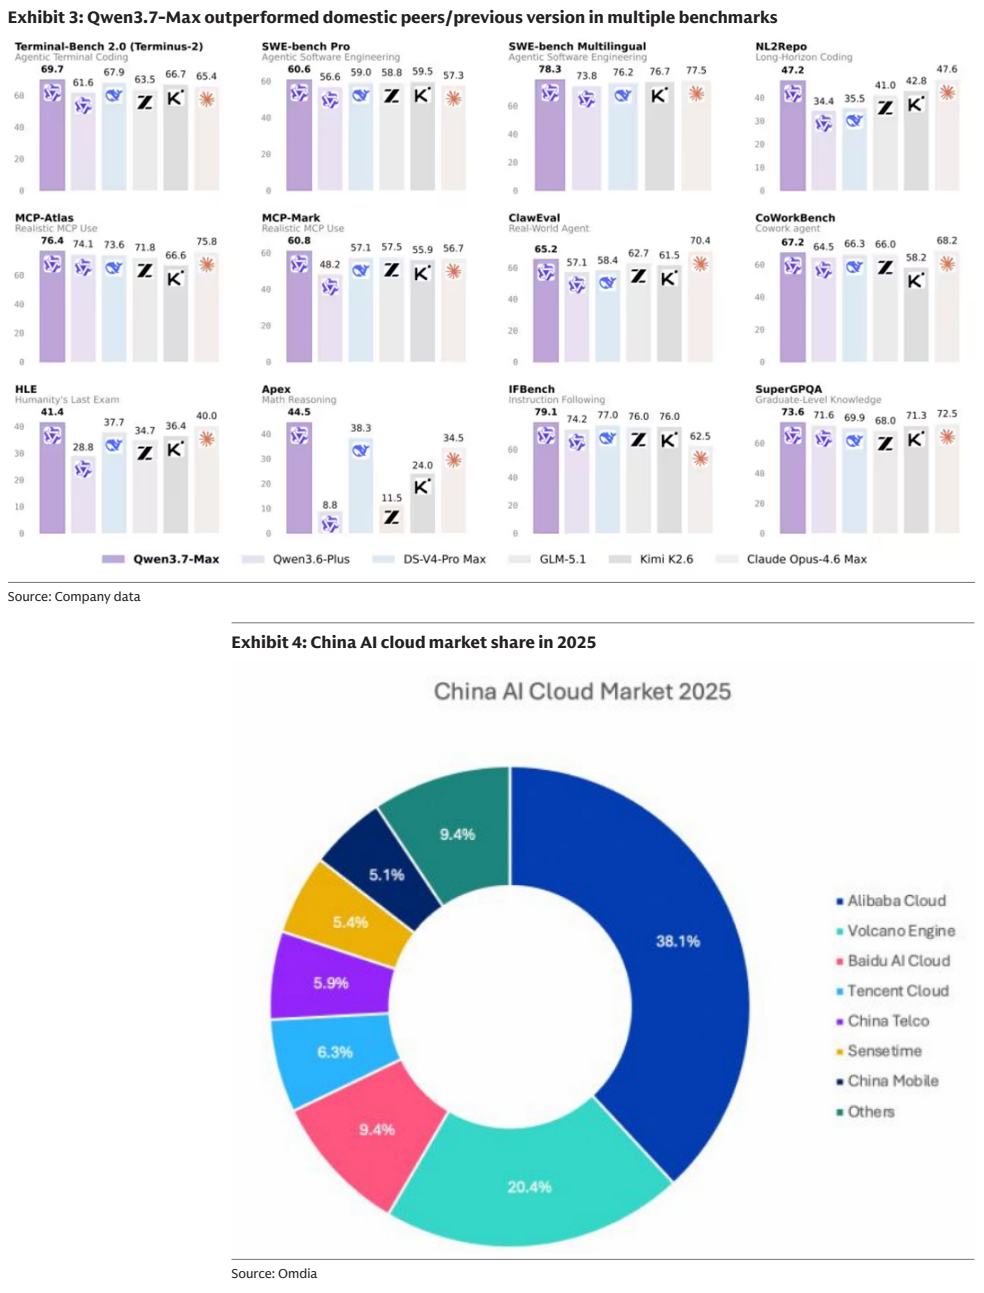
Exhibit 2