UBS Iron Ore and Coal: China — Encouraging Data but Early Days
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
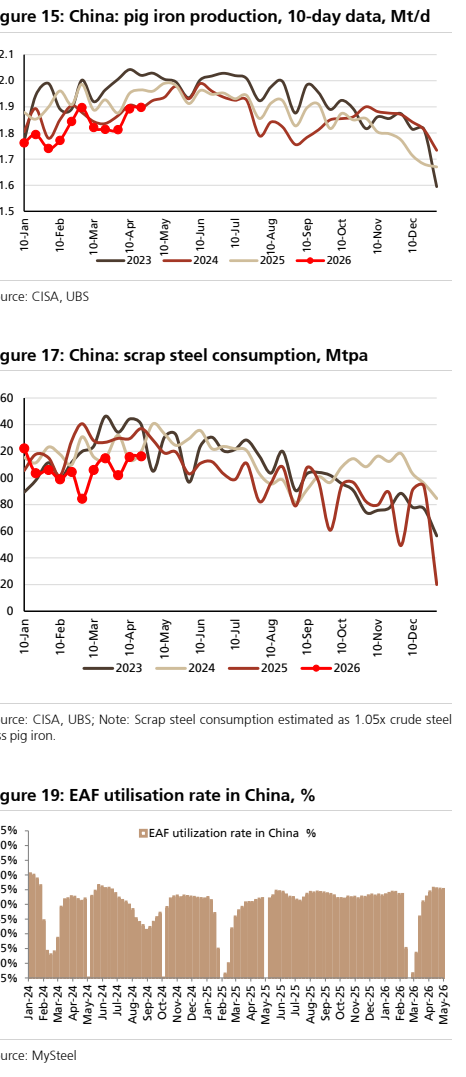
UBS observes that recent Chinese iron ore and coal demand data points are encouraging, though the firm cautions that it remains too early to confirm a sustained trend reversal. Steel production has rebounded, driving an 8% year-over-year increase in iron ore imports, which reached 102 million tonnes in May 2026, primarily supported by mill restocking activities. Crude steel output also rose 3.5% year-over-year.
However, underlying demand remains highly bifurcated. The persistent weakness in the property sector continues to drag on broader consumption, with new housing starts falling another 12%. On the metallurgical coal front, prices rebounded 2% month-over-month but remain 15% lower year-over-year, significantly limiting further upside potential.
Thermal coal consumption grew 4% year-over-year in May, almost entirely driven by power generation demands, while industrial coal usage remained flat. Domestic coal production increased 5%, keeping supply conditions loose and pressuring import price advantages. Iron ore port inventories declined by 5 million tonnes from April to 135 million tonnes, though levels remain elevated compared to the previous year.
UBS maintains a cautiously optimistic stance, noting that the apparent data improvements partially stem from a favorable base effect rather than a fundamental demand recovery. The firm awaits further monthly data to confirm the trend, closely monitoring the efficacy of real estate stimulus measures, infrastructure investment pacing, and steel capacity rationalization.
Key exhibits
Exhibit 1
Exhibit 2
Exhibit 3
Exhibit 4
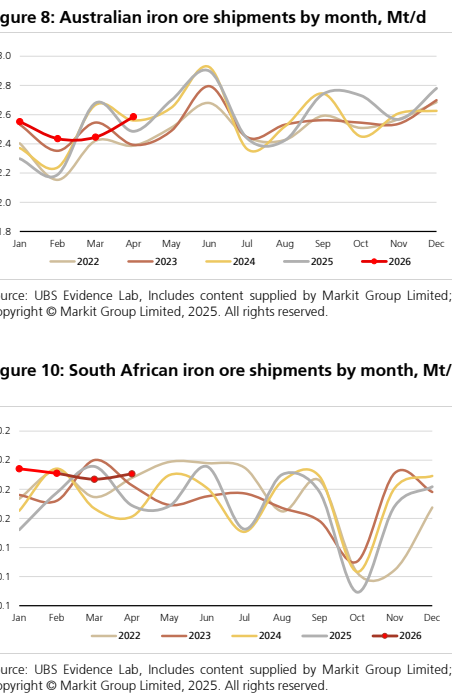
Exhibit 5
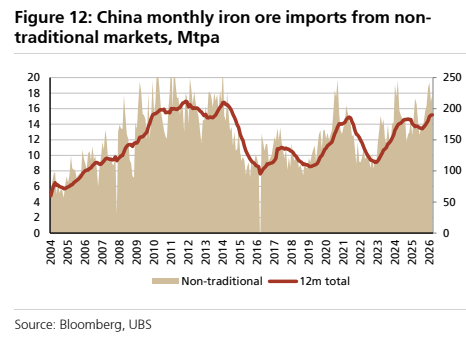
Exhibit 6
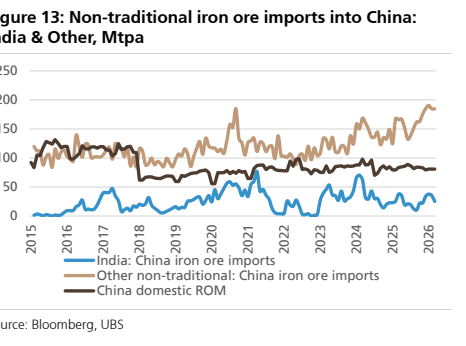
Exhibit 7
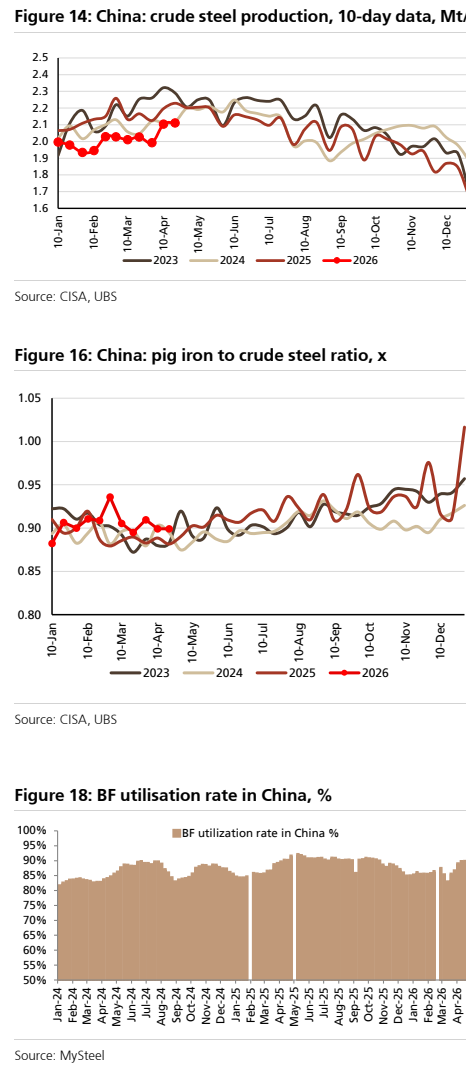
Exhibit 8