Morgan Stanley China Strategy: Free Liquidity Drops to Lowest Since Last May
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
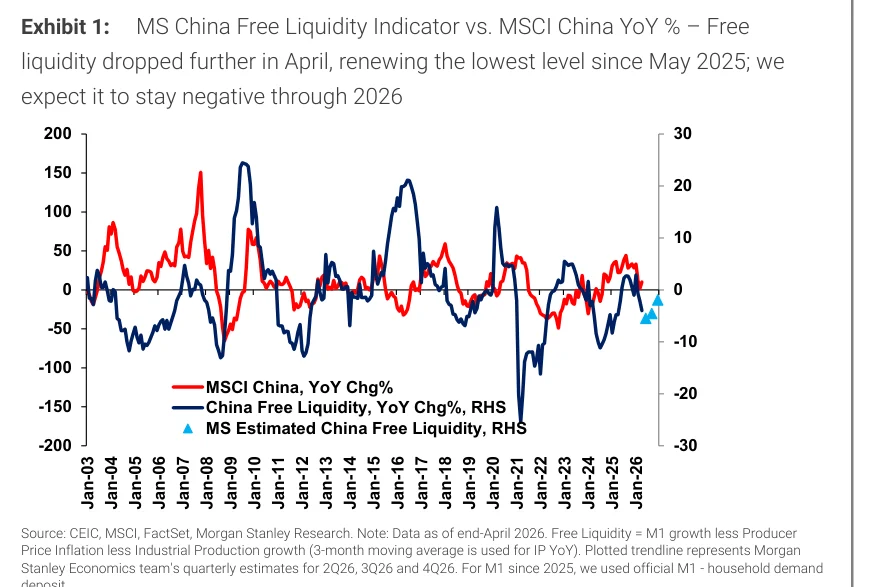
Morgan Stanley reports that its proprietary China free liquidity indicator continued to decline in April, reaching its lowest level since May 2025. This deterioration is primarily driven by persistently weak M1 money supply growth coupled with a rapid acceleration in the Producer Price Index. The bank projects that this free liquidity gauge will remain in negative territory throughout 2026, placing continued constraints on the year-over-year performance potential of the MSCI China index. Historically, the free liquidity metric has demonstrated a strong correlation with MSCI China annual returns. The current depressed readings suggest that macroeconomic liquidity offers diminishing marginal support to Chinese equity valuations, thereby limiting upside potential for broad market beta. Upstream price increases, while bolstering profitability for select resource sectors, are effectively tightening the overall liquidity environment by elevating broader production costs. According to the framework, reviving equity market risk appetite will require more robust credit and monetary policy transmission mechanisms. Such mechanisms must translate into tangible improvements in M1 growth and corporate cash flows. Until energy shocks dissipate and PPI pressures ease meaningfully, liquidity conditions are likely to remain a binding constraint. Investors are advised to maintain a cautious stance on broad MSCI China exposure and await definitive signs of a free liquidity recovery driven by credit expansion.
Key exhibits
Exhibit 1