Goldman Sachs: MongoDB (MDB.US) F1Q Preview — Positive on Atlas Growth Trajectory and AI Positioning
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Goldman Sachs maintains a Buy rating on MongoDB (MDB.US) with a $420 target price ahead of its F1Q25 earnings, reflecting confidence in the company's Atlas cloud migration trajectory and emerging AI positioning. The firm projects F1Q25 revenue of approximately $478 million, representing roughly 20% year-over-year growth and modestly exceeding the Street consensus of $475 million. Non-GAAP operating profit is estimated at $115 million, implying a 24% margin.
Atlas remains the core growth engine, with revenue expected to grow approximately 25% year-over-year and account for 68% of total revenue. Goldman highlights that enterprise workload migration to Atlas continues unabated, supported by healthy net new annualized recurring revenue. On the AI front, MongoDB's vector search capability has attracted roughly 1,000 customers in trial phases, though revenue contribution is expected to remain limited in F1Q, with more meaningful impact anticipated in the second half of fiscal 2025.
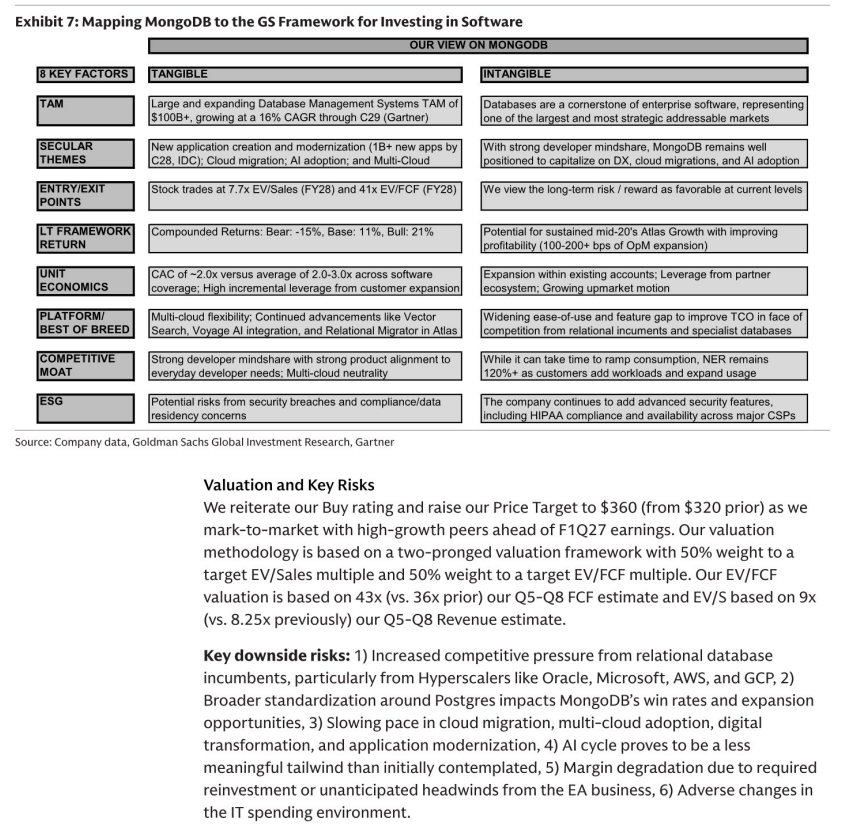
Management's own guidance of $472–476 million in revenue and $108–111 million in non-GAAP operating profit is viewed as conservative. At current levels, the stock trades at approximately 6.5x EV-to-revenue for fiscal 2025, below the historical average of 8x, offering an attractive entry point. The $420 target is derived from an 8x EV-to-revenue multiple applied to estimated fiscal 2025 revenue of approximately $2.25 billion. Key downside risks include macroeconomic deterioration, intensifying competition from hyperscaler alternatives such as AWS DocumentDB, a deceleration in Atlas growth, and slower-than-expected AI monetization.
Key exhibits
Exhibit 1

Exhibit 2

Exhibit 3
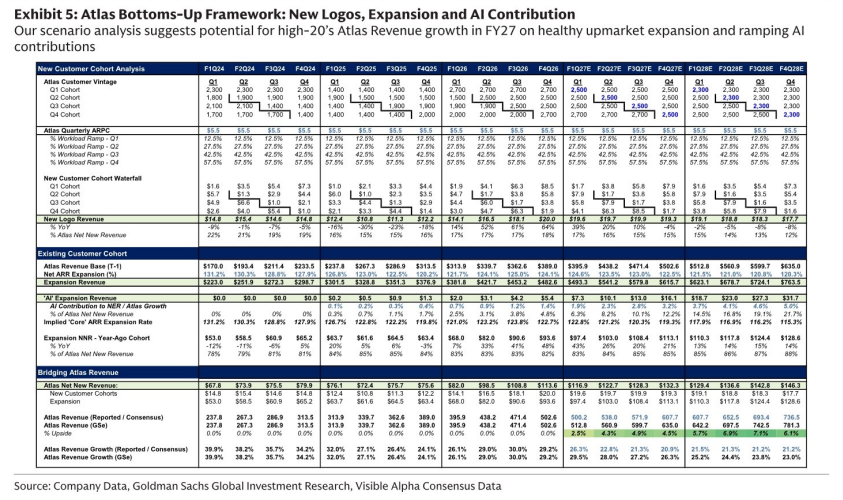
Exhibit 4

Exhibit 5