BofA Oracle Corporation 4Q26 Preview: Balancing Growth and DC Buildout with Financing Needs; PO to $240
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
BofA Securities previews Oracle Corporation's fourth-quarter fiscal year 2026 results, highlighting the intricate balance the company must strike between sustaining revenue growth and managing massive data center capital expenditures alongside associated financing requirements. The firm maintains a Buy rating on the stock, raising the price objective from $230 to $240, based on approximately 25 times the fiscal 2027 non-GAAP earnings per share estimate.
For the upcoming quarter, BofA projects revenue of $14.6 billion, representing an 8% year-over-year increase, alongside non-GAAP earnings of $1.80 per share. The Oracle Cloud Infrastructure segment remains the primary growth engine, with revenue expected to surge 45% to $2.2 billion. Conversely, the traditional database licensing business faces ongoing pressure, with anticipated revenue declining 2% due to accelerated cloud migrations.
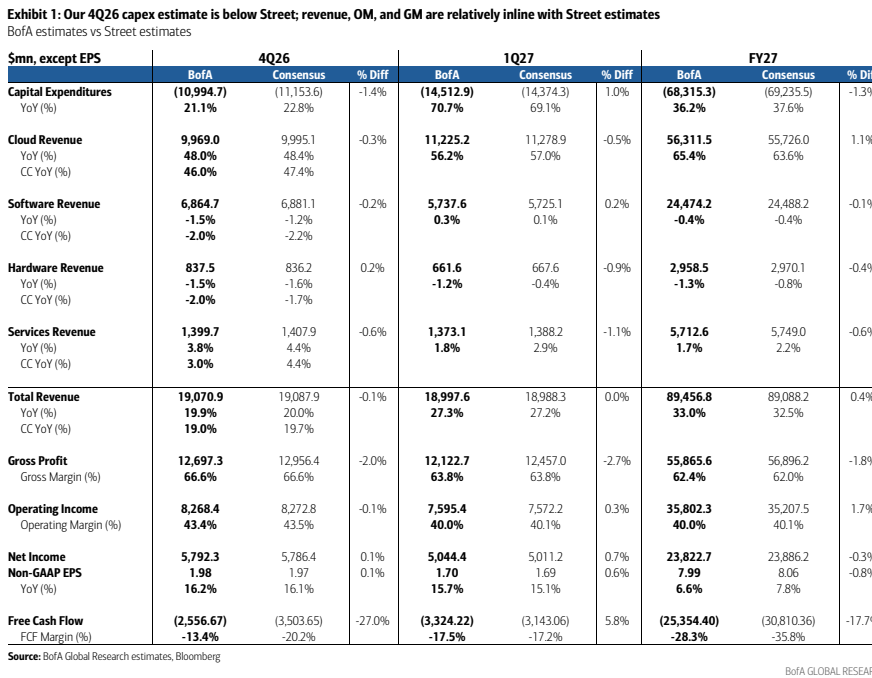
Capital expenditures for data centers remain elevated, estimated at $3.5 billion for the quarter and $13 billion for the full year, exceeding prior guidance. However, the company successfully finances this expansion through a combination of debt issuance and operating cash flow, maintaining a manageable net debt to EBITDA ratio of approximately 2.5 times. Despite short-term financing concerns, BofA reaffirms confidence in Oracle's long-term trajectory toward its fiscal 2027 revenue target of $65 billion.
Key exhibits
Exhibit 1