BofA Unity (U.US) Q3 2026 Preview: Size of the Beat in Focus; Create Strategy Clarity Key to Next Leg Up
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
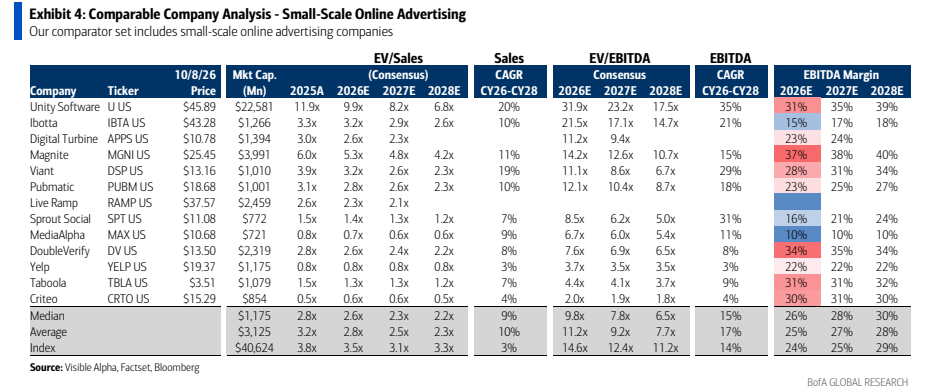
BofA reiterates a Buy rating on Unity with a USD 50.00 target price, based on 18x FY2027E EBITDA. Ahead of third-quarter results, the debate has shifted to the size of the beat: UnityAds growth is running strong, with year-on-year growth expected to decelerate from 100% to 57% across the first to fourth quarters of FY2027, and third-quarter Grow revenue carries upside risk against guidance of 20% sequential growth. The key focus will be how effectively management demonstrates results from integrating the Vector model with game-engine runtime data, and whether it can articulate a clear long-term monetization logic for the Create business. BofA views the market's low expectations for Create monetization and profitability improvement as a source of potential positive surprise, and its FY2026 and FY2027 revenue estimates sit above Street consensus. The bank forecasts FY2027 EPS of USD 2.16 and FY2028 EPS of USD 2.36. Upside risks include Vector outperformance and proof of Create profitability; downside risks stem from Grow growth failing to reaccelerate or macro headwinds reducing mobile-gaming ad spend.
Key exhibits
Exhibit 1
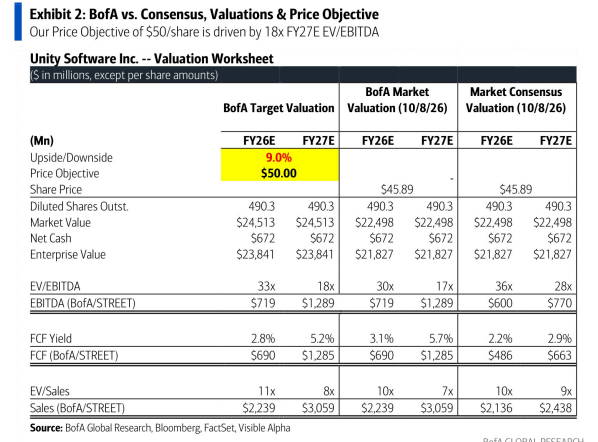
Exhibit 2
Exhibit 3