Bernstein US IT Hardware Server OEMs: Investors' Three Concerns About Dell and Why We Think the Risk Is Contained
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Bernstein tackles three investor concerns about Dell sparked by financing receivables jumping 71% year over year to $20.5 billion in FQ2'27: AI data center readiness risk, the durability of the financing surge, and credit quality deterioration. The analysts contend financing is integral to Dell's differentiated AI infrastructure offering, and the build mainly mirrors the surge in AI server orders—up 150% sequentially to $60.9 billion in FQ2'27—rather than structural risk.
Under 11% of Dell's AI server business involves financing, mostly short-term bridge facilities of four to twelve months, and financing receivables as a share of the AI server backlog are actually declining. The credit mix has shifted: high-grade credits fell from 47% of the portfolio in FQ1'27 to 36% in FQ2'27, with mid- and low-grade at 64%. Even so, Dell has not loosened underwriting—take-or-pay agreements feature in structuring—and the loss reserve rate holds near 1.5%. FQ2'27 net write-offs were $20 million, a 0.5% rate, in line with history. Dell expects long-term capital providers to replace Dell Financial Services as customer data centers reach operational targets. Bernstein reiterates Outperform on Dell with a $650 target; HPE and SMCI are both Market-Perform, at $62 and $42.
Key exhibits
Exhibit 1

Exhibit 2

Exhibit 3
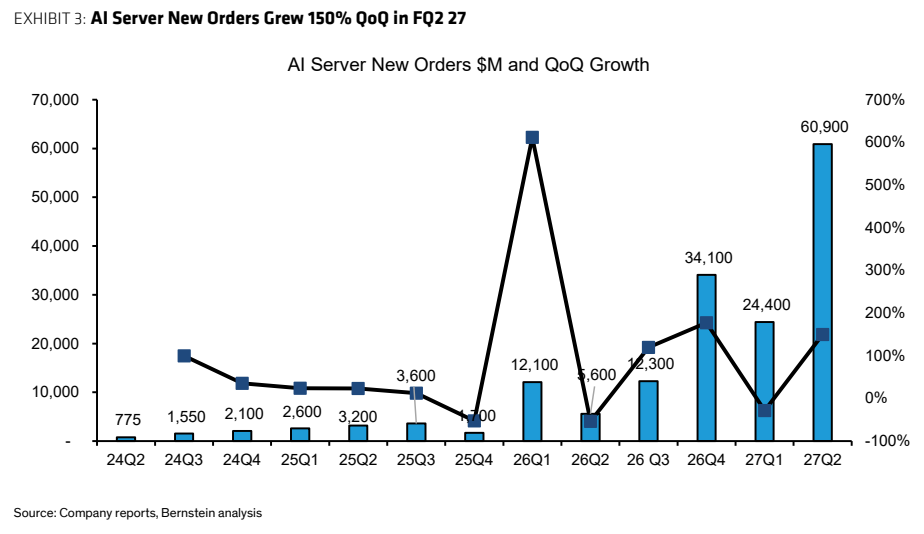
Exhibit 4

Exhibit 5

Exhibit 6

Exhibit 7

Exhibit 8
