UBS: Arista Networks (ANET.US) Supply Chain Takes a Bite Out of Rev Rec but Long-Term Demand Drivers Intact, Reiterate Buy
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
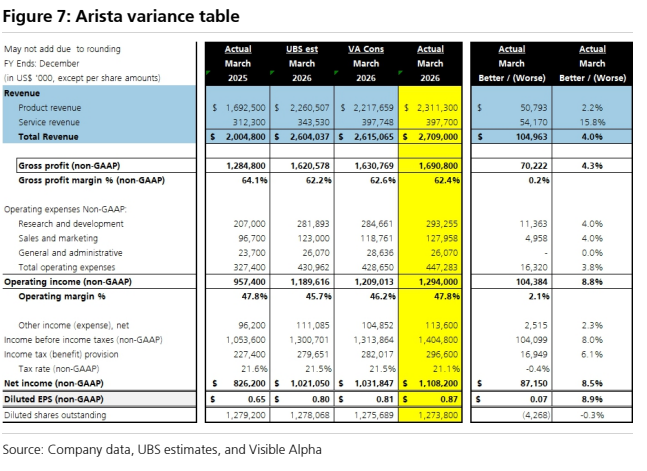
UBS reiterates a Buy rating on Arista Networks, raising its target price from $177 to $187 following stronger artificial intelligence capital expenditure trends. For the first quarter, Arista reported revenue of $2.71 billion, beating expectations by 4%, alongside earnings per share of $0.87. Management raised its full-year 2026 revenue growth guidance to approximately 28%, up from 25%, pushing the AI revenue target from $32.5 billion to $35 billion.
Despite this robust demand, supply chain constraints affecting wafers, silicon, CPUs, and optical modules are currently limiting revenue recognition. Consequently, the gross margin guidance of 62% to 64% is trending toward the lower end. Nevertheless, underlying demand signals remain exceptionally strong. Product deferred revenue surged by $643 million sequentially, and purchase commitments reached $8.9 billion, reflecting sustained hyperscale orders.
Arista's second quarter guidance projects revenue of $2.8 billion and earnings of $0.88 per share. UBS subsequently lifted its 2026 and 2027 EPS estimates to $3.61 and $4.36, respectively. The revised target price of $187 is based on approximately 42 times the 2027 EPS estimate. This valuation premium aligns with the broader AI infrastructure peer group, which trades near 45 times earnings. UBS cautions that ongoing supply chain pressures and non-linear AI revenue recognition could render current forecasts conservative.
Key exhibits
Exhibit 1
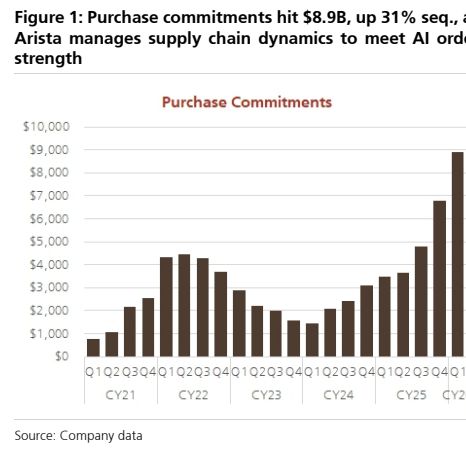
Exhibit 2
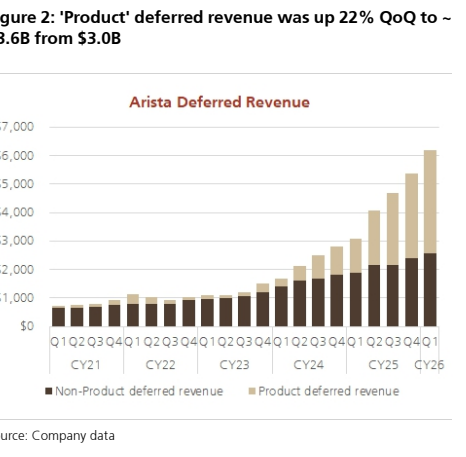
Exhibit 3
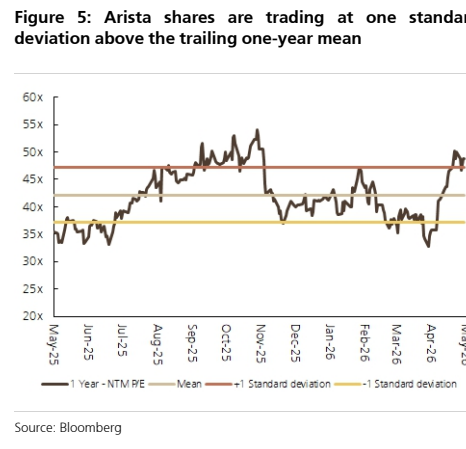
Exhibit 4
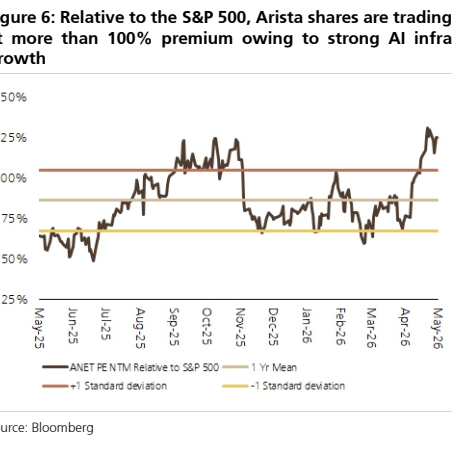
Exhibit 5