UBS: Mango Excellent Media (300413) Ads Show Resilience but Membership Trend Weak; Maintain Neutral
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Key Views
Advertising revenue has remained stable despite a soft macro environment, supported by the company's premium content monetization capabilities. However, membership growth is decelerating, with ARPU under downward pressure due to intensifying competition and declining user willingness to pay. The company continues to invest in content production, but short-term conversion into significant revenue growth appears unlikely. Cost-side pressures further limit margin improvement potential.
Outlook
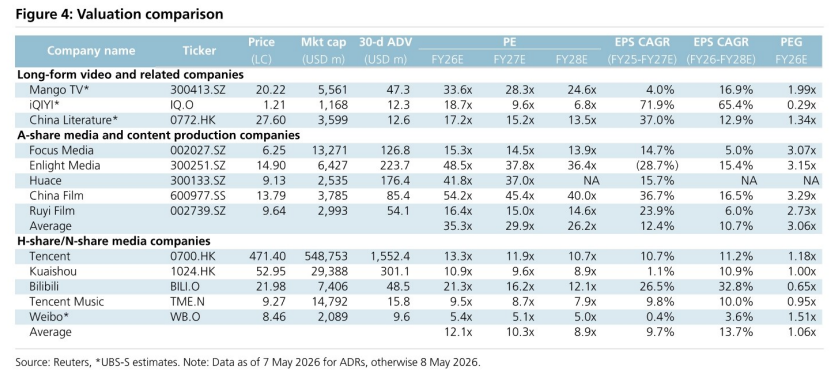
Current valuation already reflects market concerns over decelerating growth, leaving limited upside potential. Key downside risks include persistently weak membership growth, content cost overruns, and advertising revenue volatility. The report did not specify a revised target price, explicit catalysts, or a defined time window for validation. No notable positive catalysts are identified, suggesting investors await a more attractive entry point.
Recommended Securities
Mango Excellent Media (300413): Neutral. No target price provided.
Key exhibits
Exhibit 1
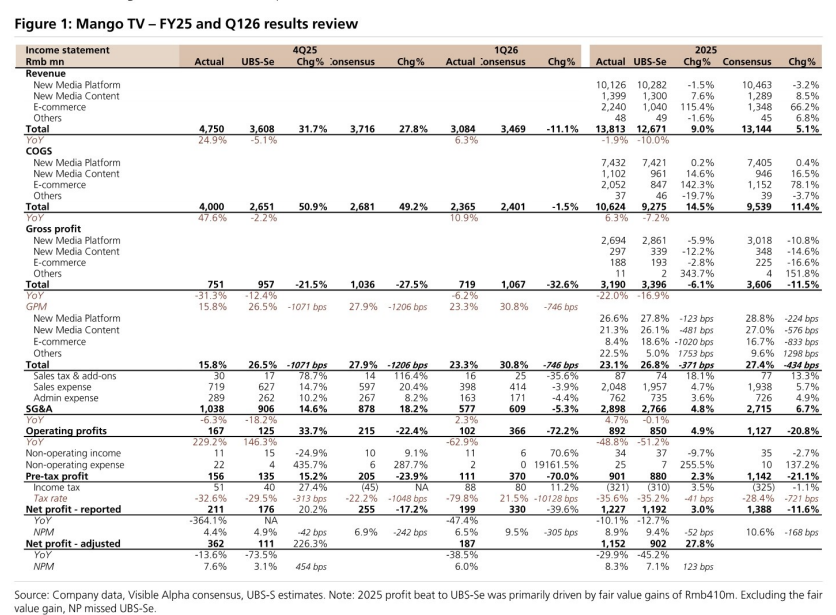
Exhibit 2
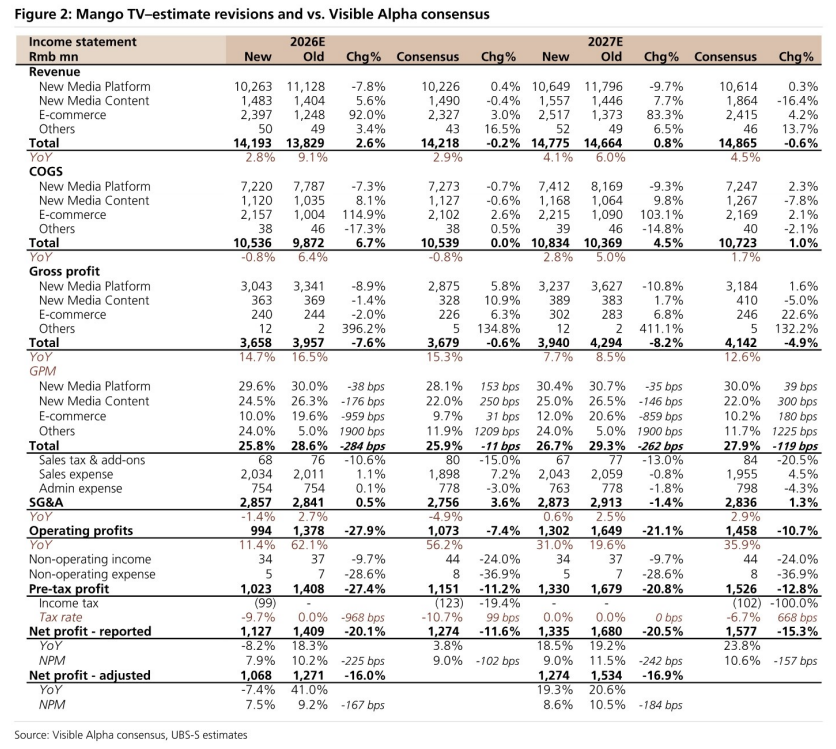
Exhibit 3
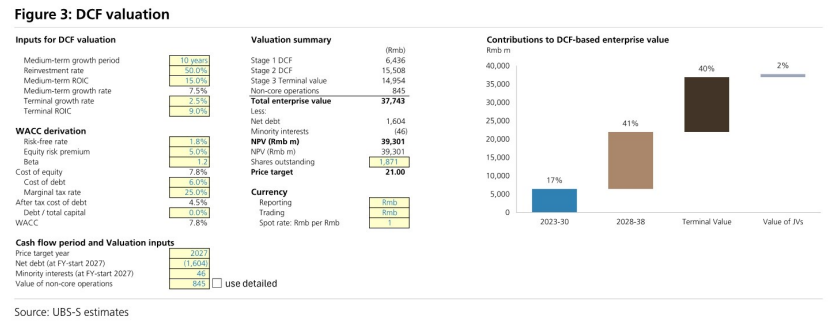
Exhibit 4