ECO Optoelectronics (688610): Industrial Camera Applications Keep Expanding
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
ECO Optoelectronics' H1 2026 results validate strong demand across PCB, display-panel and lithium-battery end markets: revenue rose 82.33% YoY to RMB378m, attributable net profit 91.92% to RMB69m, and profit excluding share-based payments 148.38% to RMB91m. Segment revenue: electronics manufacturing RMB115m (+60.44%), new display RMB109m (+143.66%), new energy RMB85m (+79.85%) and others RMB69m (+58.60%). Gross margin improved 1.85pct to 43.01% and net margin to 18.31%, while the expense ratio fell 0.85pct to 22.48%. Product iteration continues—16K optical-port color TDI line-scan cameras and CXP12-UD smart frame grabbers launched; high-speed cameras are in semiconductor-inspection validation with leading domestic equipment makers; high-resolution line-scan cameras ship in volume into gene sequencers, extending into ophthalmic OCT and pharma automation. Huatai maintains 2026-28 net profit forecasts of RMB128m/RMB237m/RMB342m (+100.28%/+84.79%/+44.28%) on revenue of RMB801m/1.217bn/1.647bn, applies 75x 2027E P/E in line with peers' iFind consensus, and raises the target price to RMB261.00 from RMB181.04, reiterating Buy. Risks: softer downstream demand, slower new-field penetration, delayed capacity additions and faster overseas technology iteration.
Key exhibits
Exhibit 1
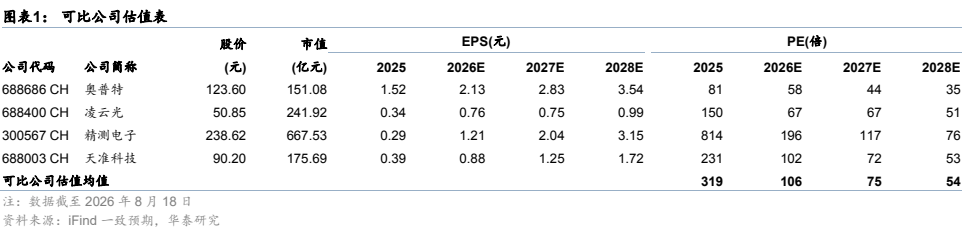
Exhibit 2
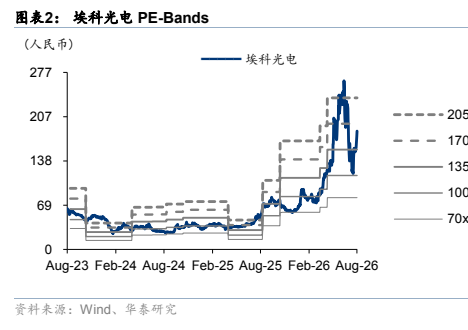
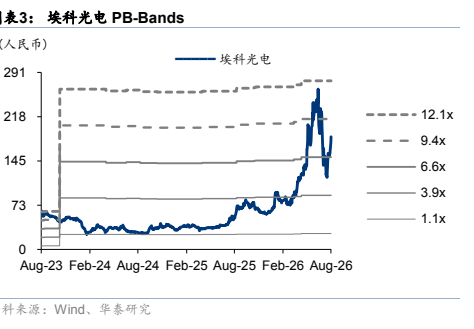
Exhibit 3