Goldman Sachs Global Markets Daily: A More Durable Risk Premium in JGBs
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Goldman Sachs has raised its long-end Japanese Government Bond (JGB) yield forecasts, citing a more durable risk premium embedded within the curve. The firm now expects the 10-year JGB yield to reach 2.50% by the end of 2026 and 2.25% by the end of 2027, up from the previous 2.00% projection for both years. This adjustment reflects the market's growing conviction that the Bank of Japan's (BOJ) gradual normalization approach is insufficient to manage long-term inflation and fiscal risks.
While market pricing for the BOJ's terminal rate aligns with Goldman's 1.5% estimate, the intermediate and long ends of the curve are steepening significantly. Unlike the United States or the Eurozone, where hawkish policy repricing has historically capped term premiums, Japan is experiencing a sustained increase in risk compensation. This dynamic suggests investors remain concerned about the credibility of the policy reaction function and potential fiscal expansion.
Goldman's curve modeling indicates that the 2-year-5-year and 5-year-10year segments appear particularly steep relative to fundamentals, positioning the belly of the curve as the primary release valve for inflation anxieties. The bank notes that bearish shocks to JGBs are primarily driven by domestic factors rather than global spillovers. Consequently, a meaningful decline in long-term yields will likely require decisive BOJ action against inflation or a concrete reduction in fiscal uncertainty, rather than merely lower global interest rates.
Key exhibits
Exhibit 1

Exhibit 2
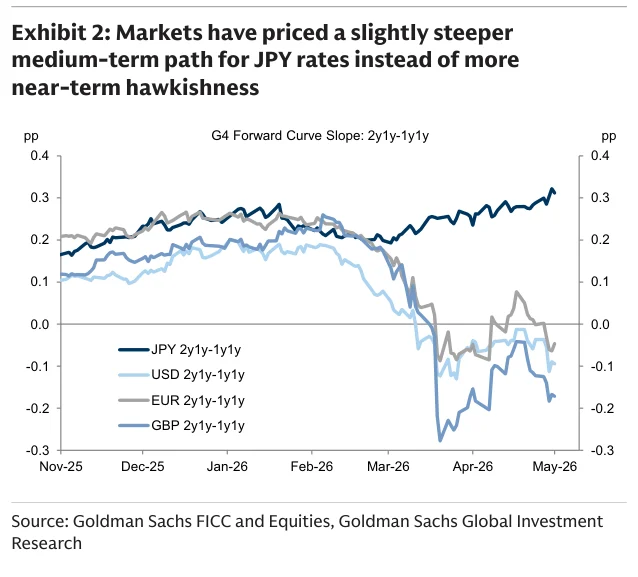
Exhibit 3

Exhibit 4

Exhibit 5

Exhibit 6

Exhibit 7

Exhibit 8

Exhibit 9

Exhibit 10
