ASMPT Ltd: 2Q26 Preview: OSAT and PCB – Dual Growth Engines
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Morgan Stanley previews ASMPT's 2Q26 results, highlighting robust capital expenditure in the OSAT and PCB sectors as dual growth engines for its Semiconductor Solutions and SMT segments. The bank raises its target price from HK$188 to HK$248 and maintains an Overweight rating. OSAT capital expenditure is projected to grow 45% in 2026, exceeding prior estimates of 34%, while PCB capital expenditure surges approximately 69%, driven by AI demand. Positioned as the sole supplier for CoWoS-L on-substrate TCB, ASMPT benefits from TSMC's CoWoS capacity expansion, expected to reach 200kwpm by the end of 2027.
For the 2Q26 preview, the bank forecasts sequential revenue growth of 9% and year-over-year growth of 34%, alongside a gross margin of 41.1%. Looking ahead to 3Q26, revenue is projected at HK$4.921 billion. Morgan Stanley upgraded its 2026 to 2028 EPS forecasts by 7%, 10%, and 10%, respectively. At 30 times forward 2027 earnings, the valuation remains attractive compared to peers Besi and Hanmi.
Key monitoring areas include HBM TCB order momentum, which has moderated as memory manufacturers prioritize server DRAM over HBM production. Additionally, investors should closely track photonics orders, potential organizational updates including a new CEO appointment, hybrid bonding progress, and underlying automotive and industrial SMT demand.
Key exhibits
Exhibit 1

Exhibit 2

Exhibit 3

Exhibit 4
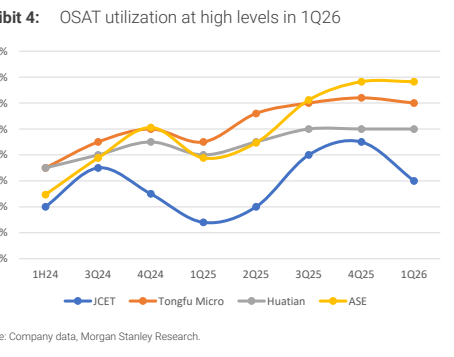
Exhibit 5

Exhibit 6

Exhibit 7

Exhibit 8
