Powering Up Europe: Who Pays for Electrification and Artificial Intelligence?
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Key Views
Under the base case (most EU targets unmet, slow data center deployment), prices rise 2% per year. Under the super-adoption case (EU targets met, higher AI agent penetration), they rise 4%. The UK and Germany may face mid-to-high single-digit increases driven by grid fees, while Italy and Spain remain roughly flat through 2035.
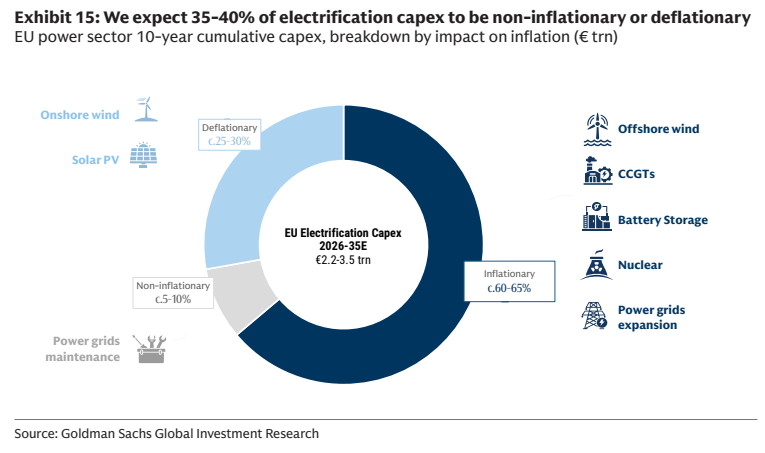
Approximately 35–40% of cumulative electrification capex (€2.2–3.5 trillion over ten years) is non-inflationary or deflationary. Demand growth from EVs, heat pumps, industrial boilers, and data centers dilutes fixed costs, potentially reducing household energy bills by around 30%, saving roughly €1,200 annually.
Recommended Securities
Goldman Sachs favors three categories: electrification transition stories (Naturgy, Enel, Engie, PPC), renewable developers (RWE, EDPR, Solaria, Orsted, Vestas, Nordex), and energy security infrastructure providers (Siemens Energy, EON, Snam).
Key exhibits
Exhibit 1
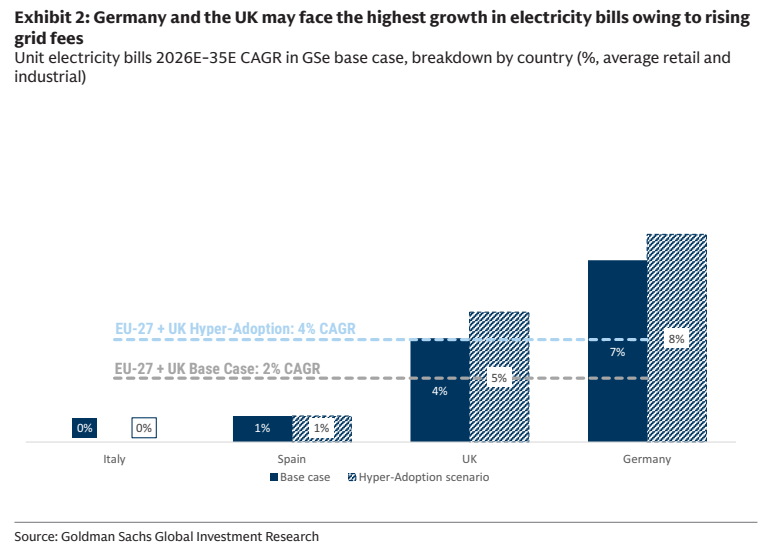
Exhibit 2
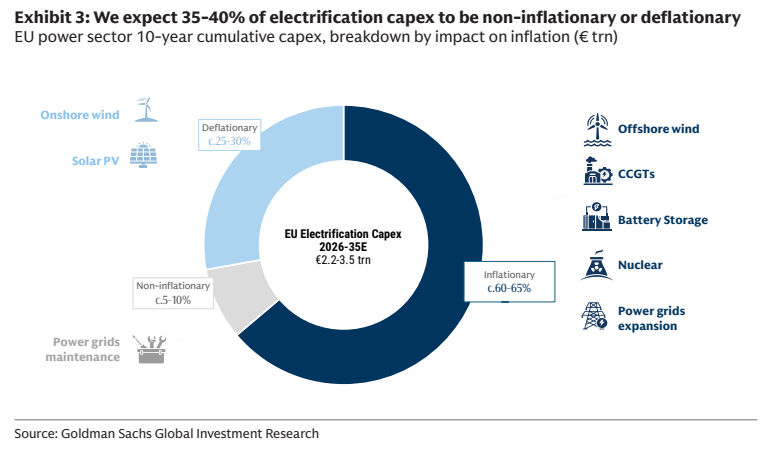
Exhibit 3
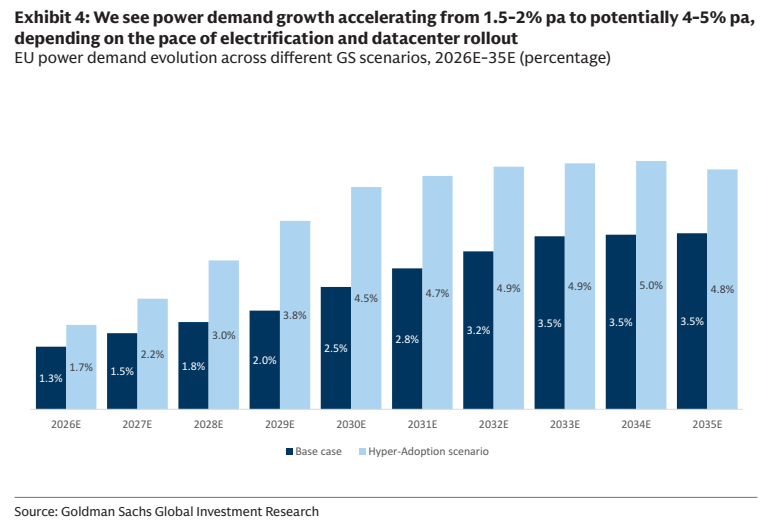
Exhibit 4
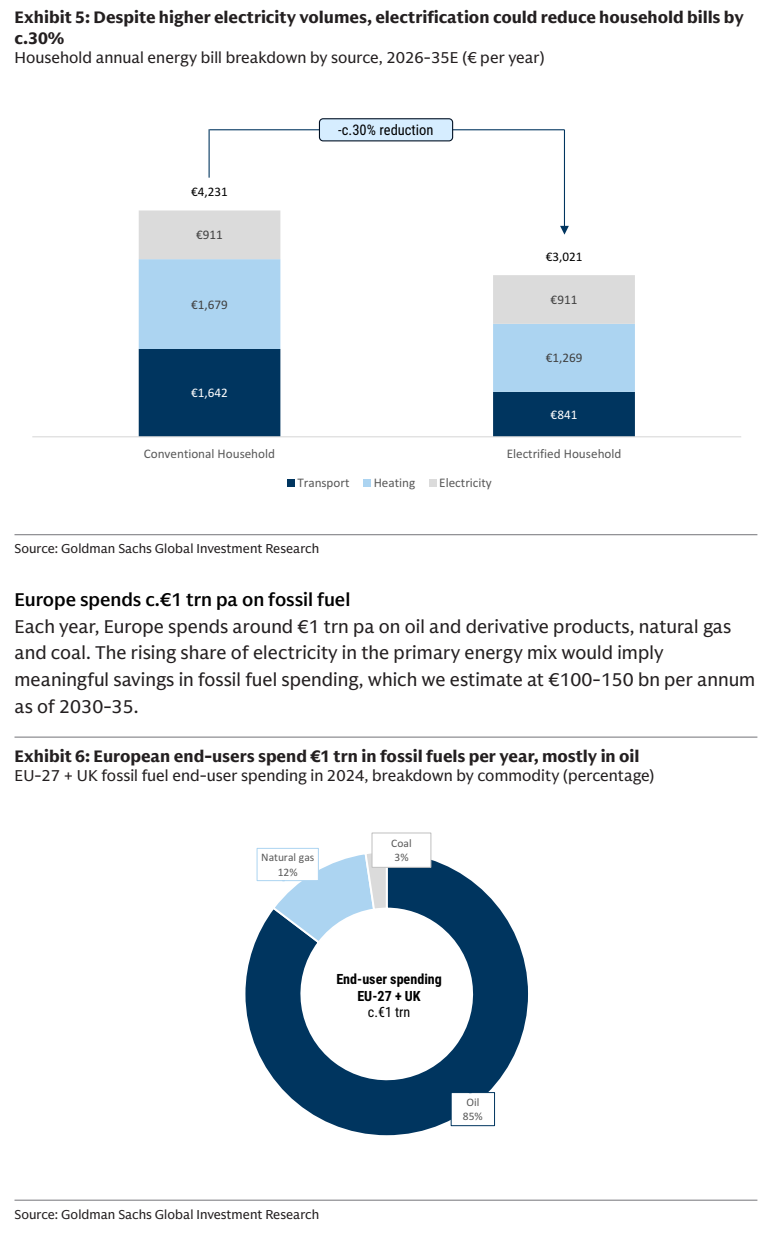
Exhibit 5
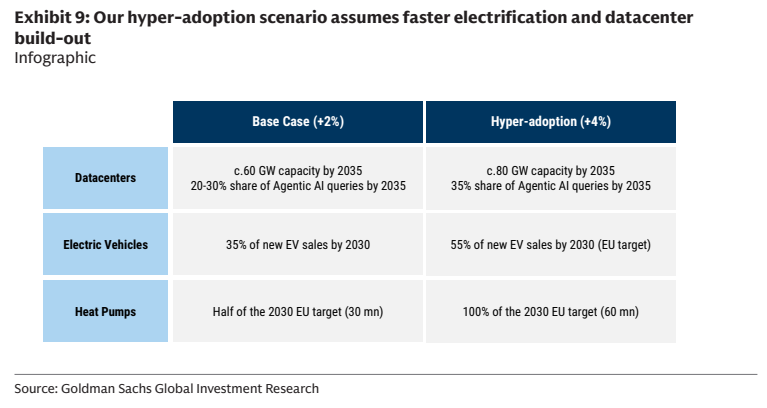
Exhibit 6
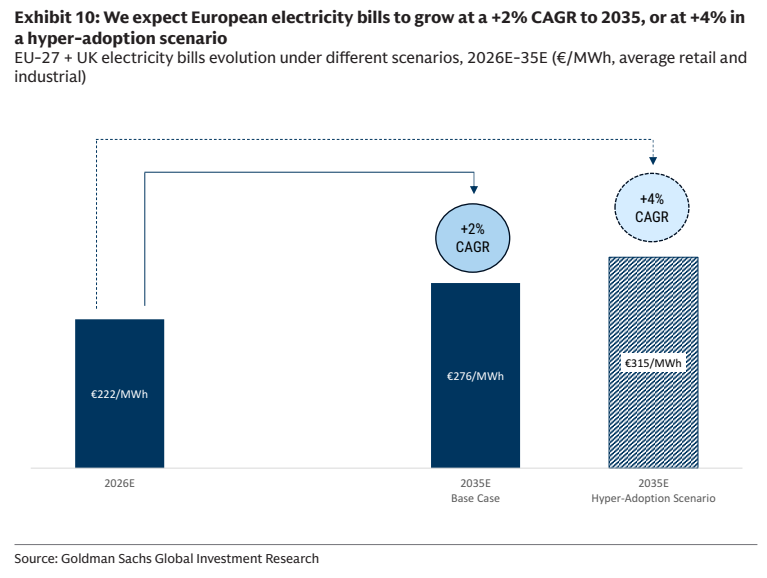
Exhibit 7
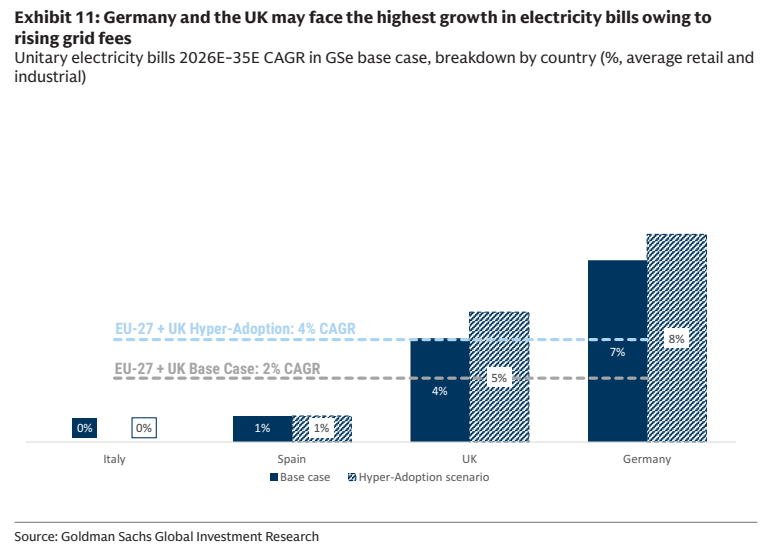
Exhibit 8