Deutsche Bank World Outlook: 1999 Meets 1990
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Deutsche Bank's latest global outlook presents a compelling macroeconomic narrative, suggesting the current environment strikingly mirrors both the technology exuberance of 1999 and the debt-laden recessionary risks of 1990. The report argues that financial markets are currently overestimating the short-term disruptive impact of artificial intelligence, leading to unsustainable valuations in AI-related equities, while simultaneously underpricing mounting geopolitical tensions and systemic debt risks. Global debt levels have reached historic highs, reminiscent of 1990 peaks, leaving both corporate and government balance sheets highly vulnerable to interest rate shocks. Meanwhile, inflation is proving extraordinarily sticky, with core CPI expected to remain stubbornly above 3% through the end of 2026. Against this challenging backdrop, Deutsche Bank forecasts global GDP growth to slow to 2.8%. The firm anticipates the Federal Reserve will implement only a single rate cut in 2026, though the exact timing remains highly uncertain. Given the dual threats of an impending valuation correction and deteriorating underlying economic fundamentals, Deutsche Bank strongly advises investors to adopt a highly defensive portfolio allocation. The recommended strategy includes overweighting safe-haven assets such as gold and short-duration sovereign bonds, while aggressively underweighting broad equities and corporate credit.
Key exhibits
Exhibit 1

Exhibit 2

Exhibit 3

Exhibit 4

Exhibit 5

Exhibit 6

Exhibit 7
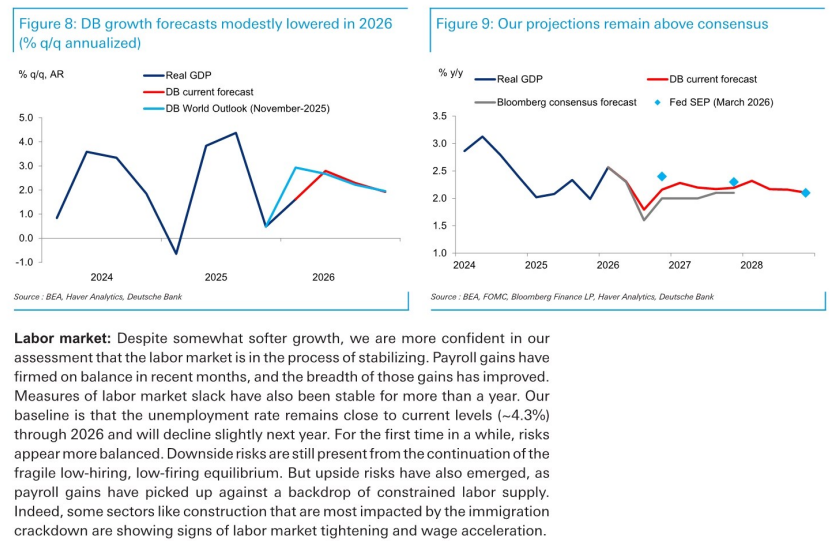
Exhibit 8
