UBS Global Unichip (3443.TW): Q1 Beat on Better GM; CPU and Automotive Projects Support Medium-Term Growth
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
A UBS report details that Global Unichip (3443.TW) delivered a strong first quarter, with gross margin reaching 32.5%, significantly beating the market consensus of 30.8%. This margin expansion was primarily driven by favorable product mix improvements. First-quarter revenue reached NT$4.52 billion, representing an 8% sequential increase and 15% year-over-year growth.
For the second quarter, management guided for revenue growth of 5-10% quarter-over-quarter, with gross margin expected to hold steady between 31% and 33%. UBS maintains a Buy rating on the stock with a target price of NT$1,200, based on an 80x price-to-earnings multiple applied to the 2026 forecast of NT$15 earnings per share.
The medium-term growth thesis is underpinned by two primary drivers. First, CPU projects are slated to begin contributing meaningfully to revenue in the second half of 2026, spearheaded by a prominent US chip design client. Second, the company has secured orders from two Tier-1 automotive suppliers, with mass production expected to commence in 2027. For the full year 2026, revenue is projected to grow 18-22%. Downside risks include potential project delays from key clients, intensifying market competition, and foreign exchange volatility.
Key exhibits
Exhibit 1

Exhibit 2

Exhibit 3

Exhibit 4
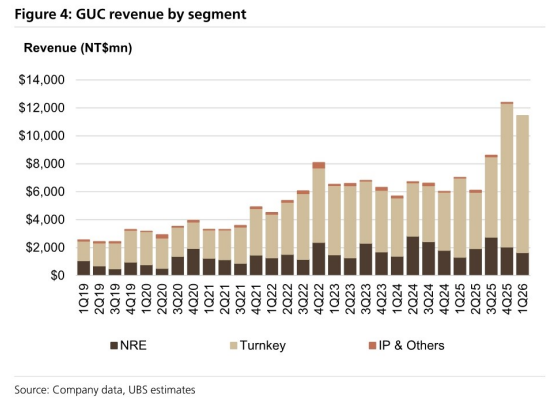
Exhibit 5

Exhibit 6
