JPMorgan | Ferrovial (FER.MC): Group EBITDA Seen Up 16%, but Focus Remains on I-24 and I-285E
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Abstract
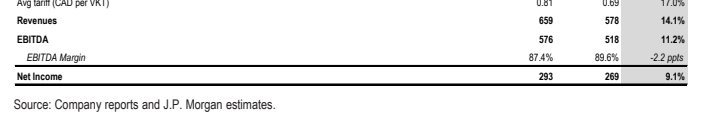
JPMorgan expects Ferrovial's Q3 2026 group EBITDA to rise 16.1% year on year, driven by margin expansion of roughly 40 basis points in Construction and continued pricing gains across the toll road business, where traffic should grow about 1.7% and average tolls roughly 11%. 407-ETR EBITDA is projected to increase 14%, despite a 2.5% traffic decline, with Toronto's weak economy and wildfires posing downside risk to third-quarter volumes. Despite the solid operating backdrop, the analysts flag two overhangs. The I-24 project — with financial details confidential under an NDA and a concession valued at $24.8 billion — should weigh on the shares until financial close, anticipated in Q2 2027. Separately, if Ferrovial wins the I-285E project in Georgia, Transurban's exit from the consortium would leave Ferrovial carrying 100% of the stake, a likely negative for the market reaction. JPMorgan downgraded the stock to Neutral with a €50.00 target price; Q3 results are due on October 27.
Key exhibits
Exhibit 1
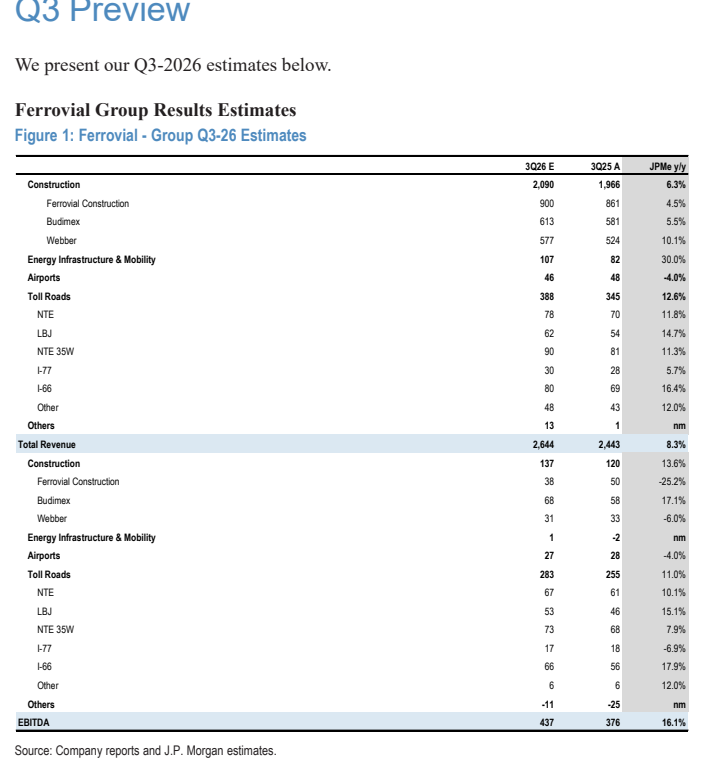
Exhibit 2