Burberry: Reflections on 1Q27 (Calendar 2Q26) – The Cross-Atlantic Halo Effect from US Marketing Activities
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Key Views
Wholesale partners are sending positive signals, prompting management to raise 1H27E wholesale guidance from MSD to HSD growth. The company continues leveraging successful campaigns such as "Portraits of an Icon" and "Good Sport" to showcase outerwear and cashmere. While investors remain concerned about operating leverage, management has committed to controlling operational costs through disciplined marketing and merchandising strategies. First-half 27E gross margin headwinds are attributed to inventory provision timing, though confidence in restoring a 70% gross margin requires further evidence.
Outlook
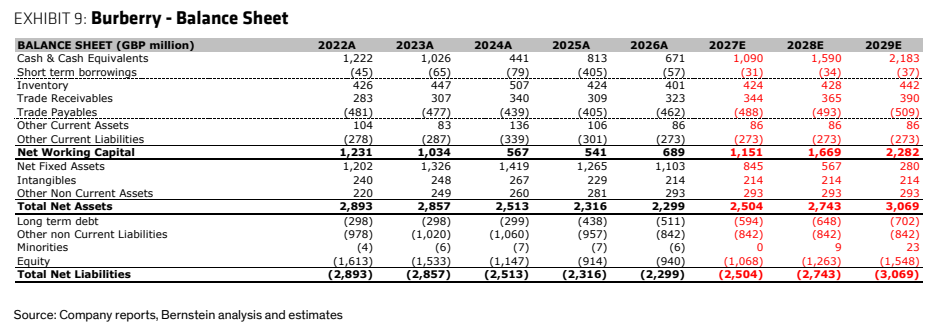
Bernstein trimmed its earnings estimates, lowering FY27E EBIT margin by 70bps to 8.8%, and cutting FY27/28E EPS by 8.7% and 1.6% respectively. The sustainable path back to mid-teens operating margins depends first on full-price revenue growth and retail space productivity, with incremental opportunities from further retail network optimization.
Recommended Securities
Burberry Group PLC (BRBY.LN): Rating Outperform; target price 1,300 GBp; last close 1,120.50 GBp, implying approximately 16% upside potential. The valuation applies 1.7x relative P/E versus MSCI Europe to blended forward NTM+1 EPS, equating to 22x NTM+1 P/E.
Key exhibits
Exhibit 1
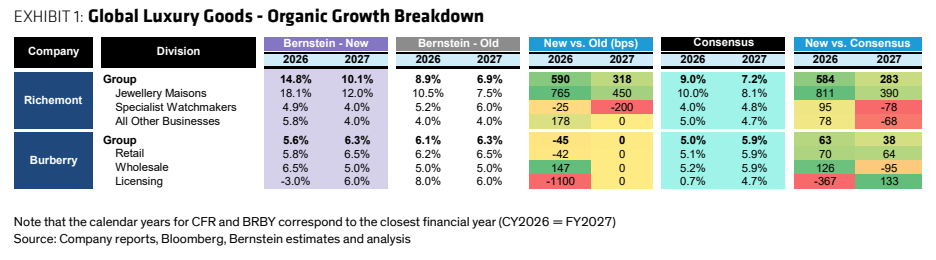
Exhibit 2
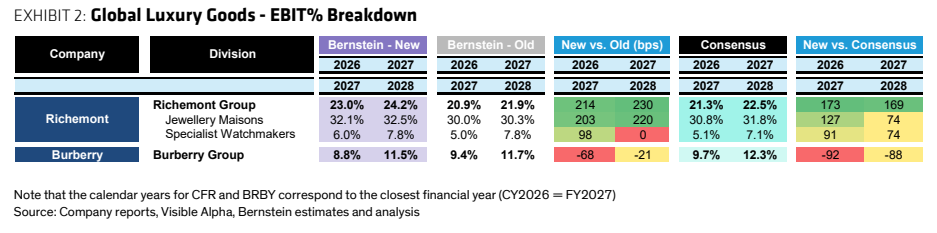
Exhibit 3

Exhibit 4
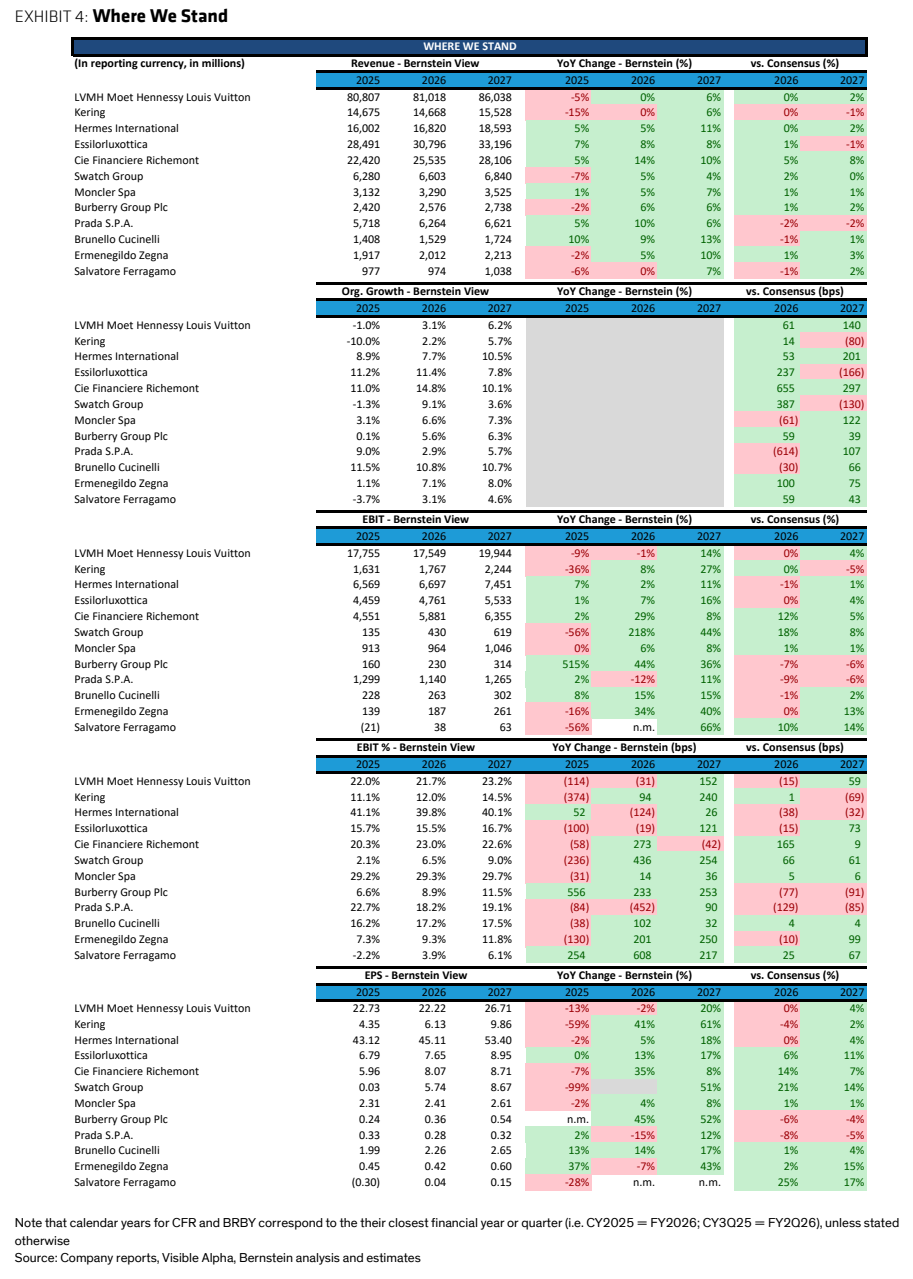
Exhibit 5
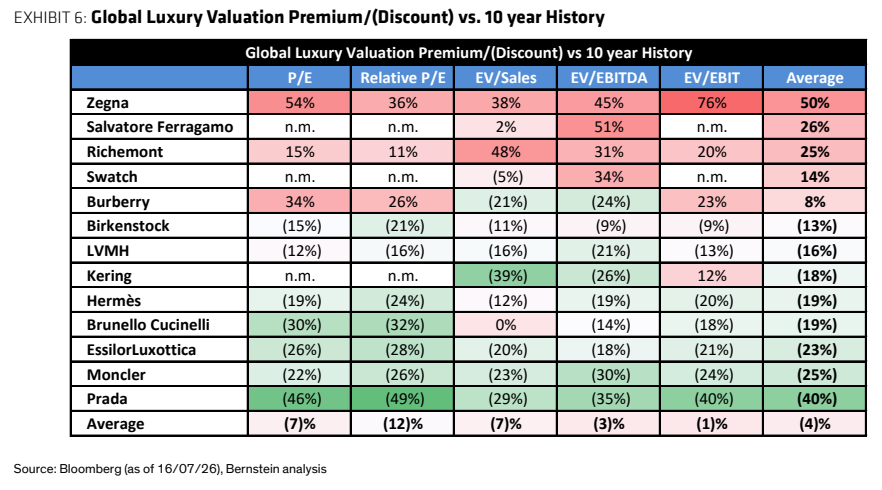
Exhibit 6
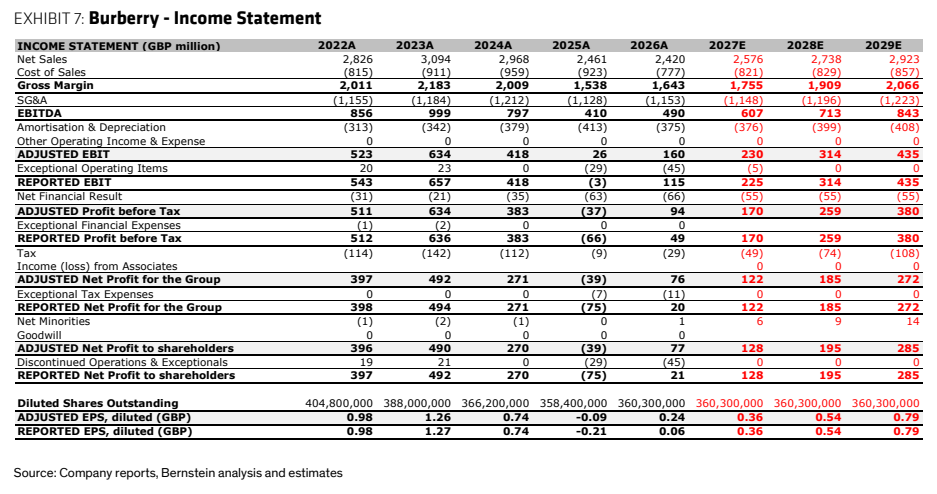
Exhibit 7
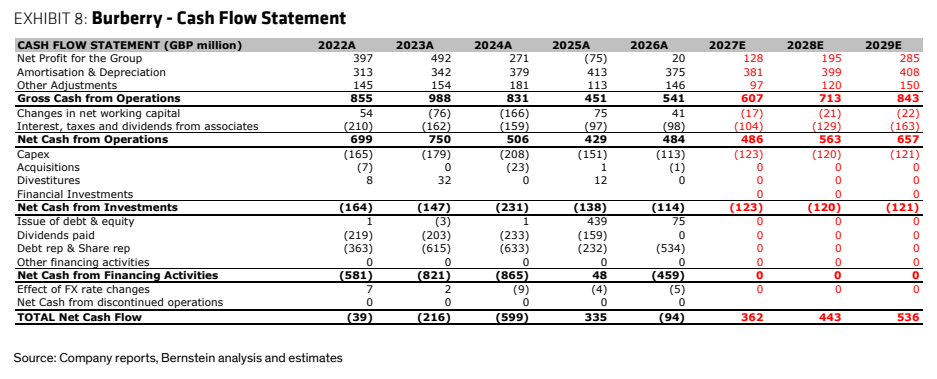
Exhibit 8