Morgan Stanley: Haidilao June 2026 Operational Update — Remains Soft
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Key Views
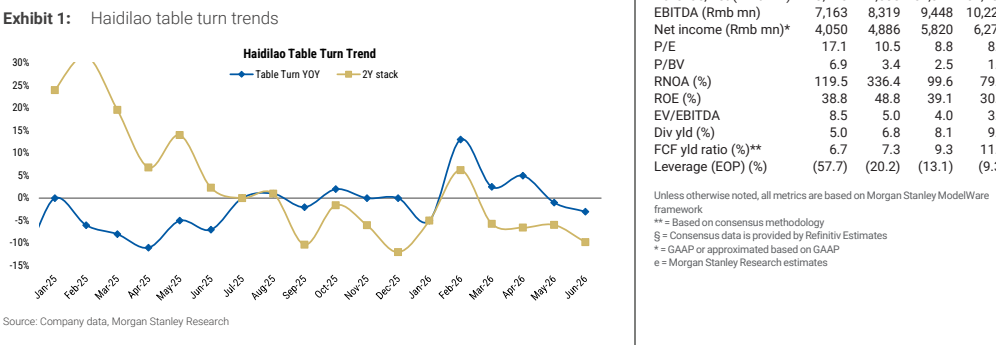
H2 base effects ease, yet tourism indicators (hotel RevPAR, domestic flights) suggest summer traffic may stay lukewarm. The report maintains an Overweight rating with a target price of HK$20.00, based on 20x 2026E P/E. The current price stands at HK$10.95, implying 83% upside.
EPS forecasts for 2026–2028 are RMB 0.90/1.07/1.16, with revenue estimates of RMB 49,588 million/54,317 million/57,451 million. The target multiple sits slightly above one standard deviation below the historical average valuation since 2018, reflecting gradual macro recovery, low inflation, and a slowly expanding store network.
Outlook
Strong operating leverage and disciplined cost control drive a 2025–27 EPS CAGR of 27%. Upside risks include faster macro recovery, stronger-than-expected demand, and accelerated new store openings. Downside risks include slow turnover recovery, raw material inflation, store opening delays, elevated labor costs, or excessive cost control eroding service quality.
Recommended Securities
- Haidilao International Holdings (6862.HK) — Rating: Overweight; Target Price: HK$20.00; Current Price: HK$10.95 (July 10, 2026); Upside: 83%.
Key exhibits
Exhibit 1