BofA Global Equity Volatility Insights: Underestimate FOMO at Your Own Risk
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Bank of America warns that despite rising inflation concerns and climbing long-end yields slowing the US equity rally, market resilience persists. In bubble-driven environments, the fear of missing out (FOMO) can overpower macroeconomic headwinds, analogous to the Nasdaq's surge during the internet bubble despite rising 30-year yields. Currently, the tension between macro risks and market bubble tendencies is pushing risks toward a twin-tailed distribution, enhancing the value of option asymmetry.
To navigate this landscape, BofA suggests using TLT put spreads to hedge against further yield increases, offering roughly 8 times maximum payout. Conversely, QQQ call spreads and hybrid NDX-USDGBP options provide inexpensive, limited-risk exposure to potential upside momentum. The firm reiterates a preference for NDX over SPX to hedge against concentrated risk and boom-bust dynamics, especially with major upcoming tech IPOs likely fueling further enthusiasm.
Geopolitically, UK political risk has resurfaced as a critical macro driver, creating cross-asset opportunities. Additionally, Chinese AI hardware is increasingly dominating the FTSE China A50 index, with the information technology sector now comprising 25% and poised to surpass financials. BofA recommends a 3-month XIN9I call spread, leveraging deeply inverted call skew to achieve a 7.1 times maximum payout ratio while strictly capping losses at 1.4%.
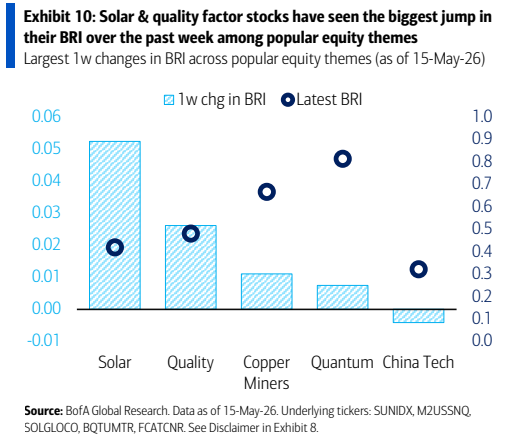
Key exhibits
Exhibit 1
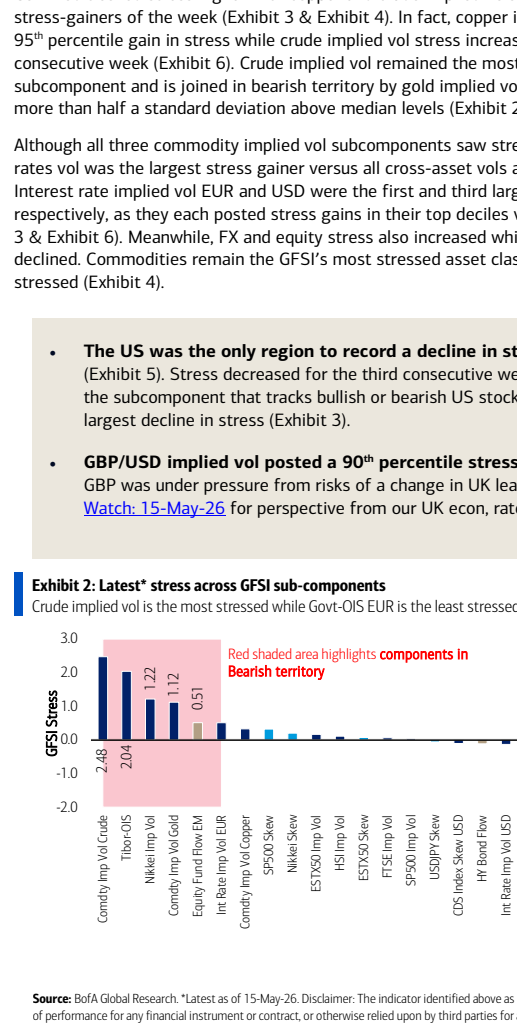
Exhibit 2
Exhibit 3
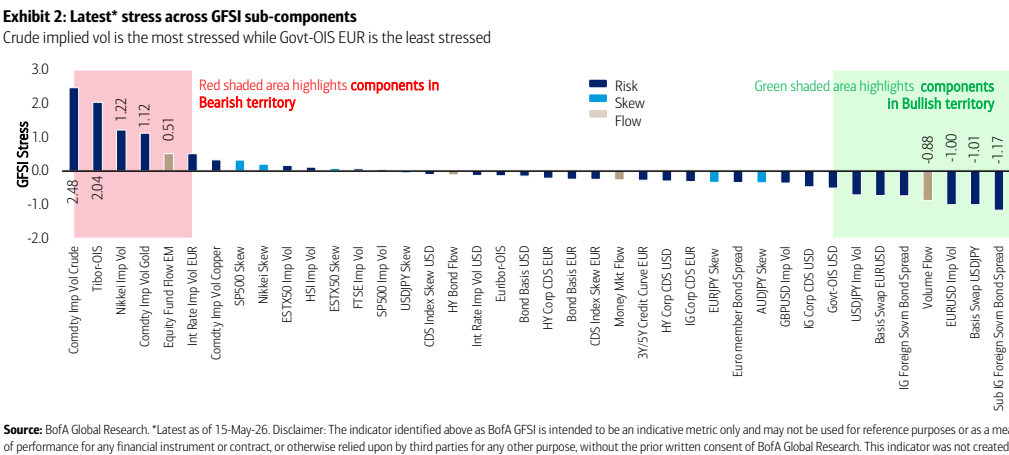
Exhibit 4
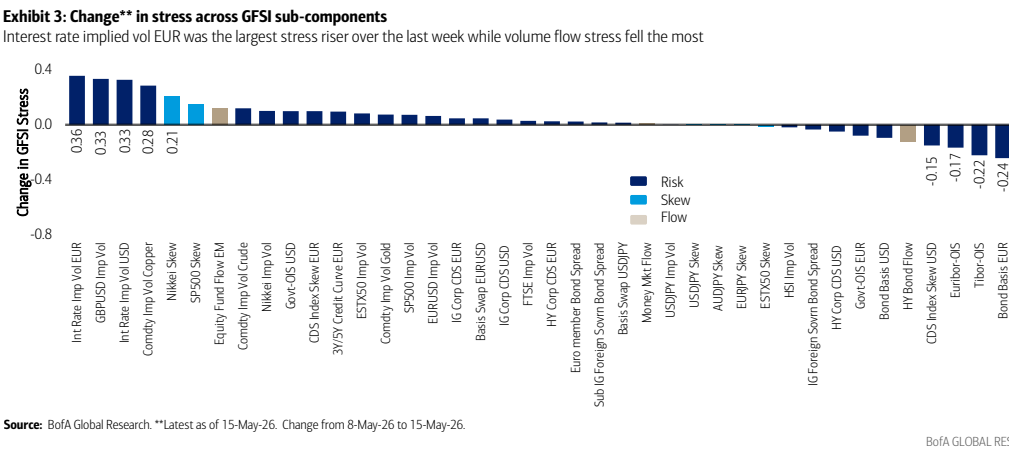
Exhibit 5
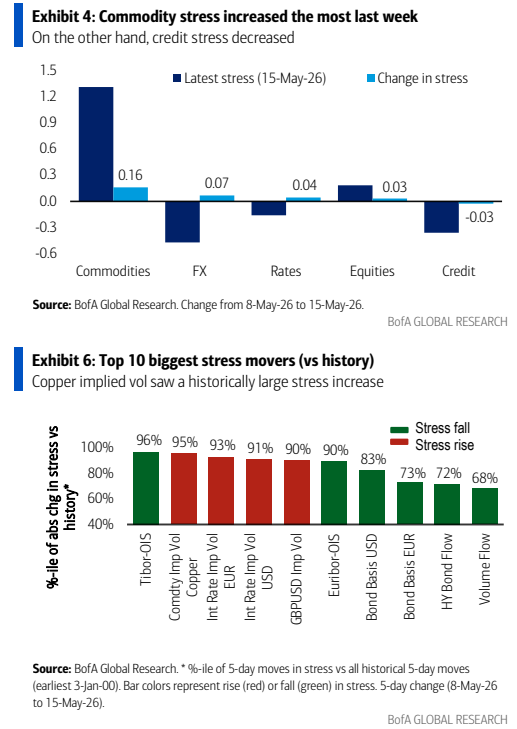
Exhibit 6
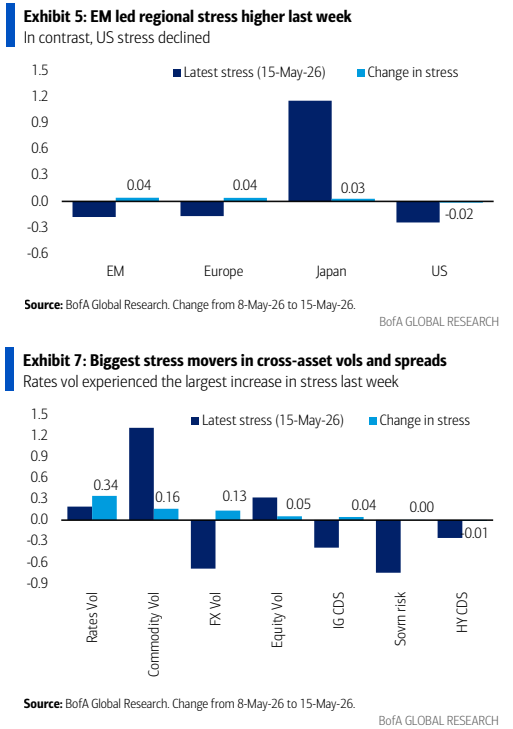
Exhibit 7
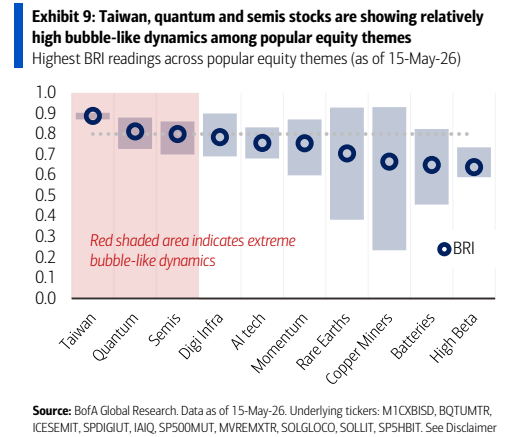
Exhibit 8