Deutsche Bank CoreWeave (CRWV.US): Putting Margins and Returns Under the Microscope
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Deutsche Bank published an in-depth analysis of CoreWeave (CRWV.US), scrutinizing its profitability and capital return trajectory. The report projects gross margins will expand from 55% in 2025 to 60% in 2026, though this remains below the market consensus of 62%. Similarly, EBITDA margins are forecast to reach 45% in 2025 and 50% in 2026, driven by scale effects and operating leverage. Return on invested capital (ROIC) is expected to climb to 12% in 2025 and 15% in 2026, but faces significant pressure from intense capital expenditure, which reaches 150% of revenue in 2025. Depreciation constitutes a major cost component, accounting for 35% of revenue in 2025 before moderating to 30% the following year. The report highlights notable risks, including accelerated GPU depreciation, intensifying competition from major cloud providers, and high customer concentration, with the top three clients contributing 70% of revenue. Free cash flow is projected to turn positive in 2026, yielding 2%, while the net debt to EBITDA ratio improves to 2.8x. Deutsche Bank maintains a Buy rating with a target price of $65, based on a 12x 2026 EBITDA valuation, citing long-term contracts and proprietary software optimization as key differentiators.
Key exhibits
Exhibit 1
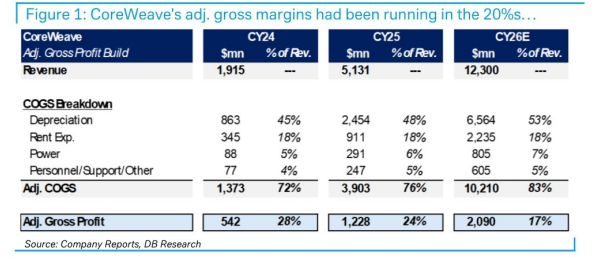
Exhibit 2
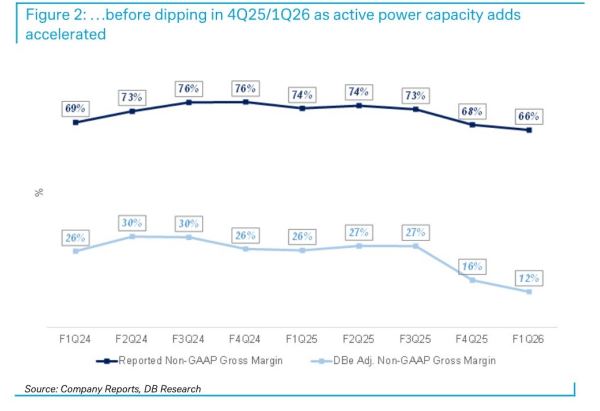
Exhibit 3
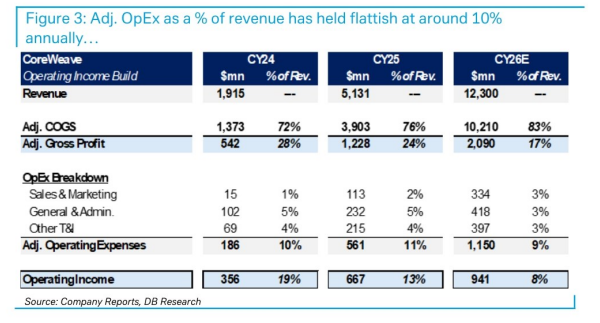
Exhibit 4
Exhibit 5
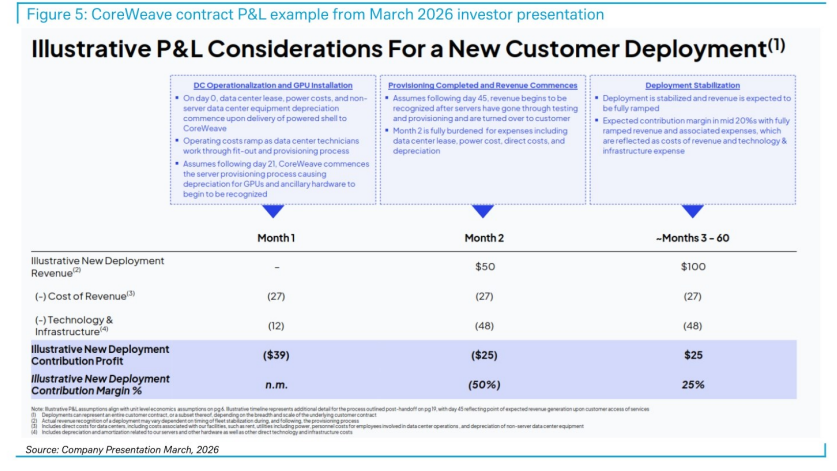
Exhibit 6
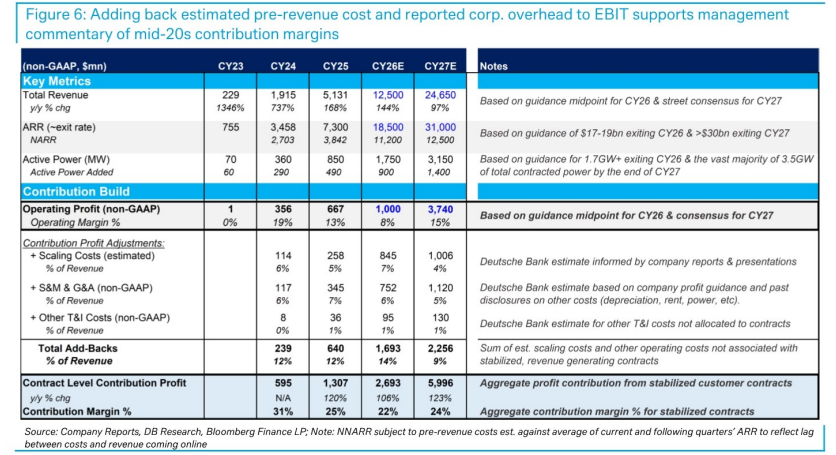
Exhibit 7

Exhibit 8
