Citi: Samsung Electronics (005930.KS) 2Q26E Preview — Bonus Provisions Drag on Operating Profit, but Memory Upside Intact
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Citi projects Samsung Electronics' 2Q26E operating profit at W7.23 trillion, missing the market consensus of W8.92 trillion by roughly 18%. This shortfall stems primarily from higher-than-expected quarterly bonus provisions, with total provisions estimated at W4.56 trillion, of which W2.0 trillion is recognized in 2Q26E. The Device Solutions (DS) division bears the brunt of this charge.
Segment-level 2Q26E operating profit breakdown is as follows: semiconductors W7.13 trillion, mobile W0.05 trillion, display W0.03 trillion, consumer electronics W0.01 trillion, and others W0.01 trillion. Despite the near-term earnings pressure, Citi remains constructive on the global memory supply-demand dynamics. The memory shortage persists, driven by AI inference demand and constrained supply growth across global suppliers. Citi expects DRAM and NAND ASPs to surge 263% and 232% year-over-year, respectively, in 2026E.
Accordingly, Citi raised its full-year 2026E operating profit estimate from W33.10 trillion to W33.42 trillion, anticipating the global memory market will remain undersupplied through 2H26E and 2027E.
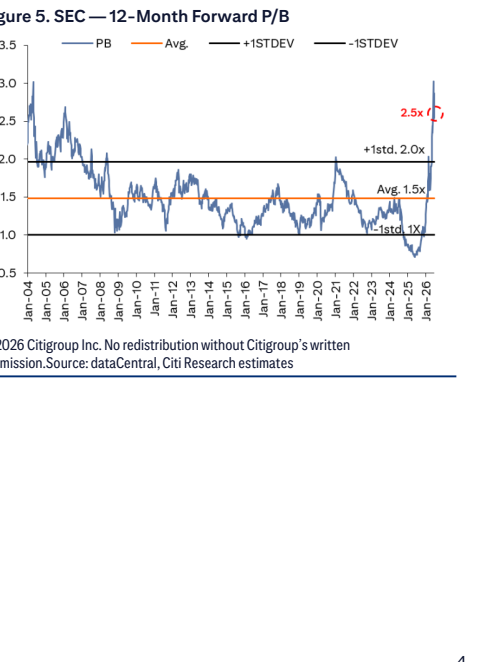
Citi maintains a Buy rating with a target price of W46,000. With the stock currently at W31,000, this implies 48.4% expected price return and 48.9% total return. Citi emphasizes that the memory cycle trajectory remains in an uptrend, despite the one-time bonus provision overhang. Key upside catalysts are linked to August 10, 2026, while downside risks include HBM shipment delays, weak PC sales, competitor capex, smartphone competition, and KRW appreciation.
Key exhibits
Exhibit 1
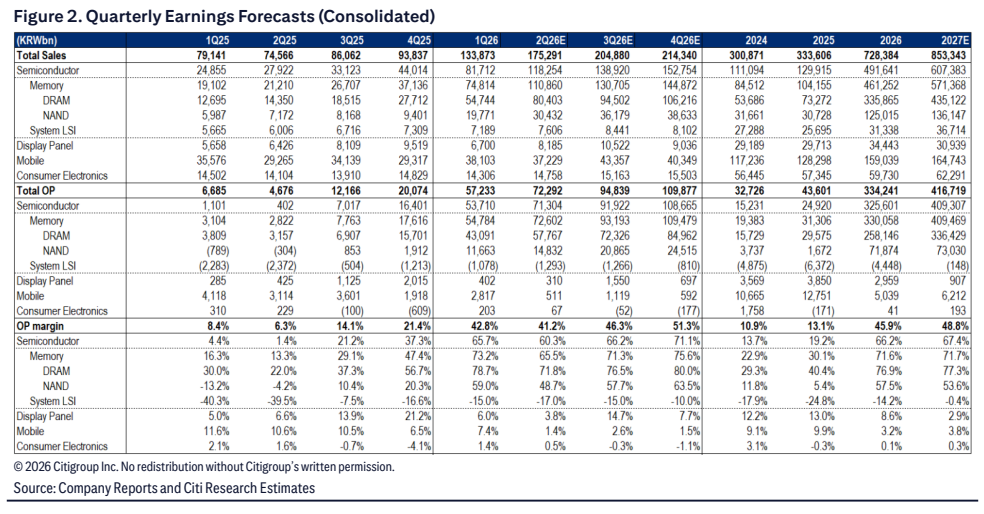
Exhibit 2
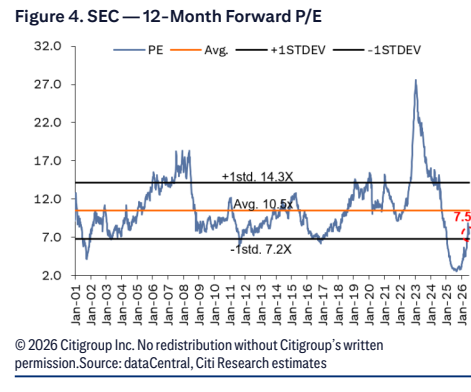
Exhibit 3