Morgan Stanley Technology: European Semiconductors — Structural Re-Rate Has Further to Run
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Morgan Stanley argues that the structural re-rating of the European semiconductor sector remains incomplete, with substantial upside potential still available. The firm points to sustained artificial intelligence demand, falling interest rates, and a weakening euro as key macroeconomic tailwinds. Currently, the sector trades below its five-year average valuation, suggesting that earnings growth expectations have yet to be fully priced in.
The European Central Bank's rate-cutting cycle is effectively lowering financing costs for capital-intensive semiconductor manufacturers. Simultaneously, a five percent depreciation of the euro against the dollar enhances export competitiveness by approximately three percent. AI-related chip demand is projected to grow thirty percent in 2026, directly benefiting European suppliers exposed to automotive and industrial applications.
At the company level, Infineon's silicon carbide revenue is expected to double to two billion euros by 2026. STMicroelectronics has successfully normalized its microcontroller inventory levels, leading to improved order visibility. NXP Semiconductors has expanded its automotive radar chip market share to forty percent, while ASML maintains an extreme ultraviolet lithography backlog exceeding twenty billion euros. Overall sector EPS growth for 2026 is forecast at fifteen percent, outpacing market consensus of twelve percent.
Morgan Stanley maintains Overweight ratings on Infineon, STMicroelectronics, NXP, and ASML, with target price upgrades across several core names. Geopolitical supply chain localization trends further support European capacity investments.
Key exhibits
Exhibit 1
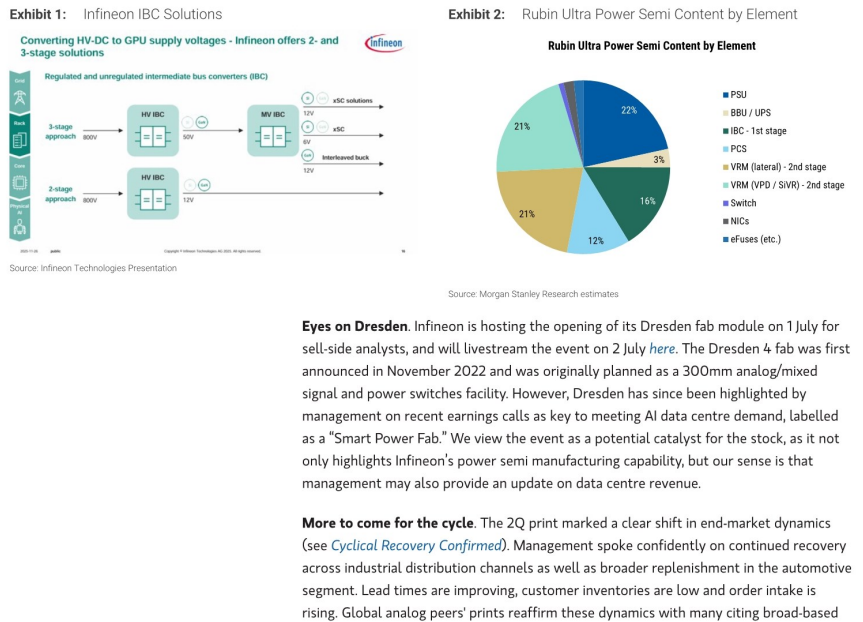
Exhibit 2
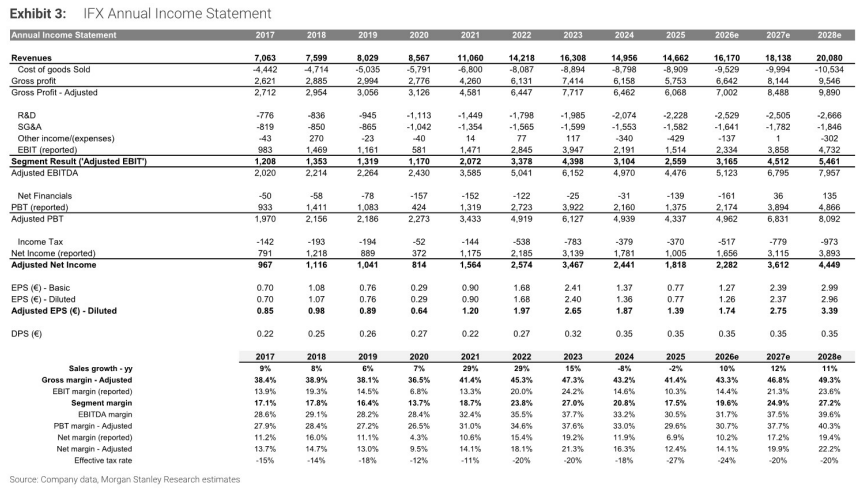
Exhibit 3
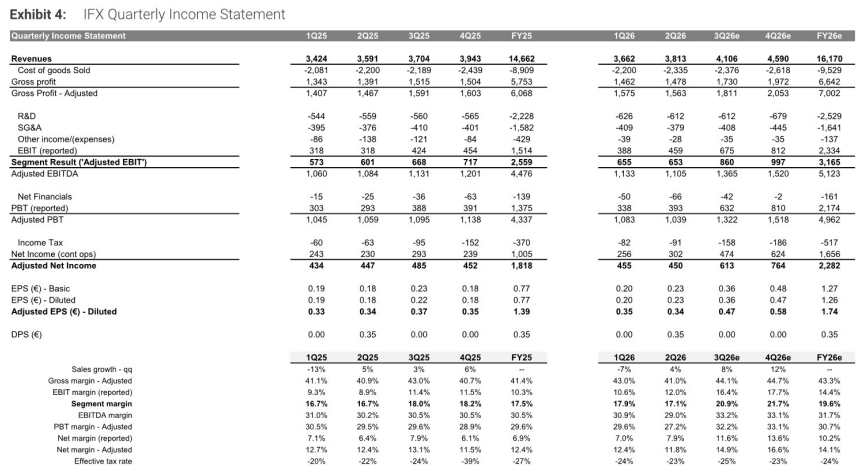
Exhibit 4
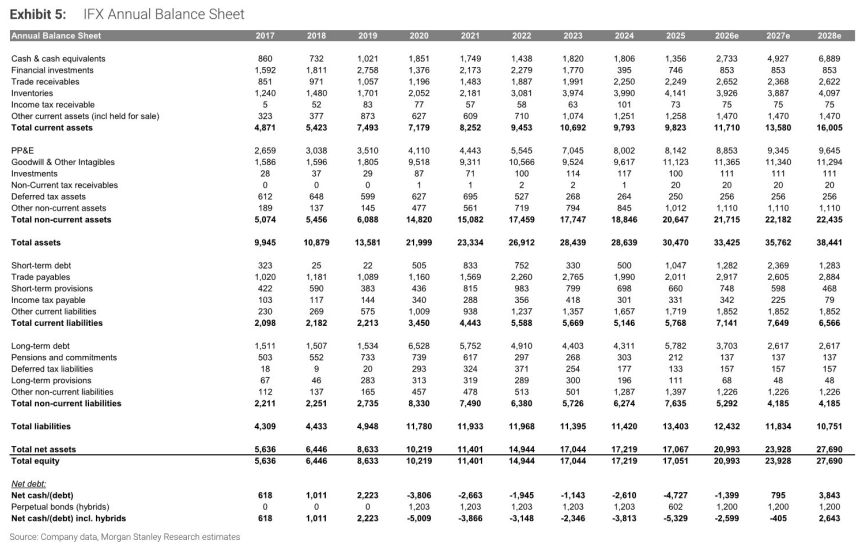
Exhibit 5
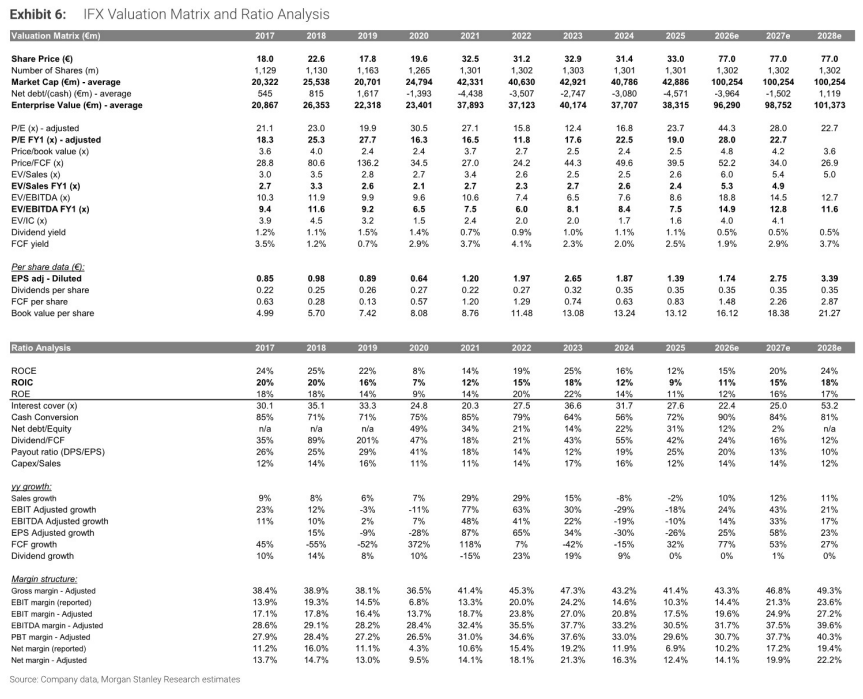
Exhibit 6
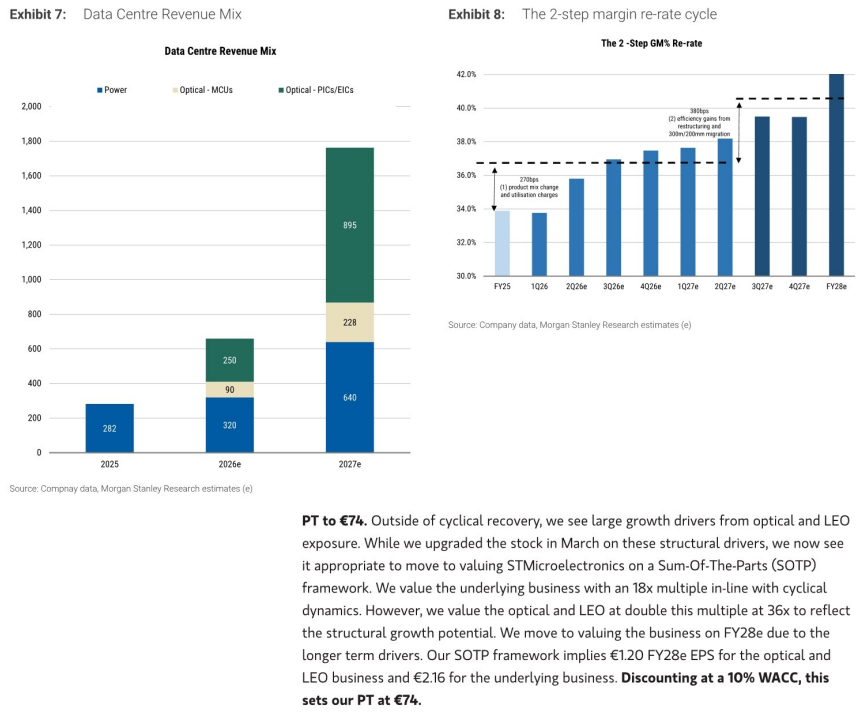
Exhibit 7

Exhibit 8
