Goldman Sachs BeOne Medicines (688235) Earnings Review: 1Q Beat with Upgraded Guidance; Eyes on ASCO for Solid Tumor Pipeline
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
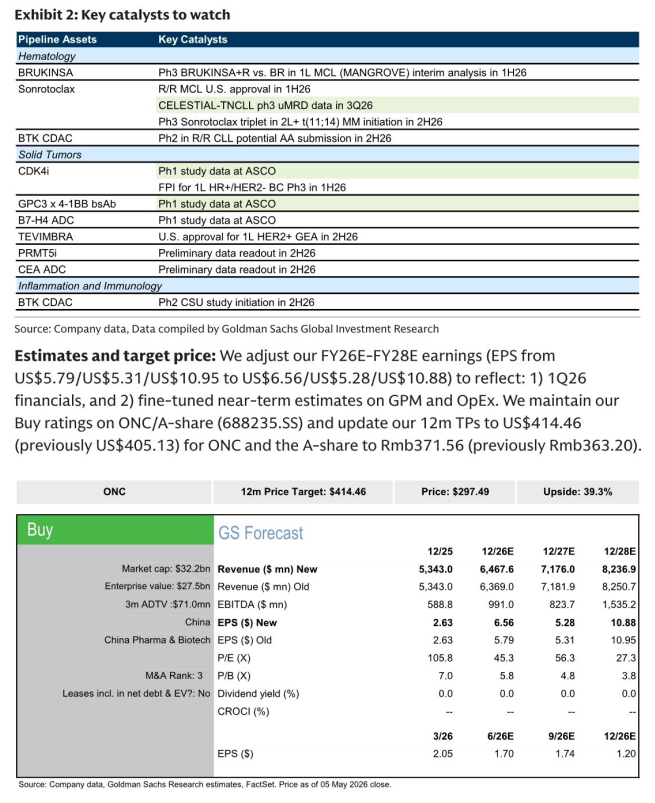
Goldman Sachs published an earnings review for BeOne Medicines following its first-quarter results, noting a significant beat and upgraded full-year guidance. Total revenue reached $850 million, representing 45% year-on-year growth and surpassing the firm's $800 million estimate. This performance was primarily driven by the continued global commercial success of zanubrutinib, which generated $520 million in sales, alongside sustained volume growth for tislelizumab in China.
Management raised the total revenue guidance for 2026 to a range of $3.5 to $3.8 billion, up from the previous range of $3.2 to $3.5 billion. Gross margins expanded by two percentage points to 82% due to scale efficiencies. Research and development expenses reached $320 million, prioritizing the advancement of solid tumor pipelines. Operating cash flow turned positive for the first time, reaching $150 million.
Goldman Sachs maintains a Buy rating with a target price of 180 Hong Kong dollars, derived from a discounted cash flow valuation. Attention is now focused on the upcoming ASCO conference, where critical data from a combination study involving BGB-15025 and tislelizumab in non-small cell lung cancer will be presented. Favorable data could significantly enhance pipeline valuation. Key downside risks include patent litigation and pricing pressures from reimbursement negotiations.
Key exhibits
Exhibit 1
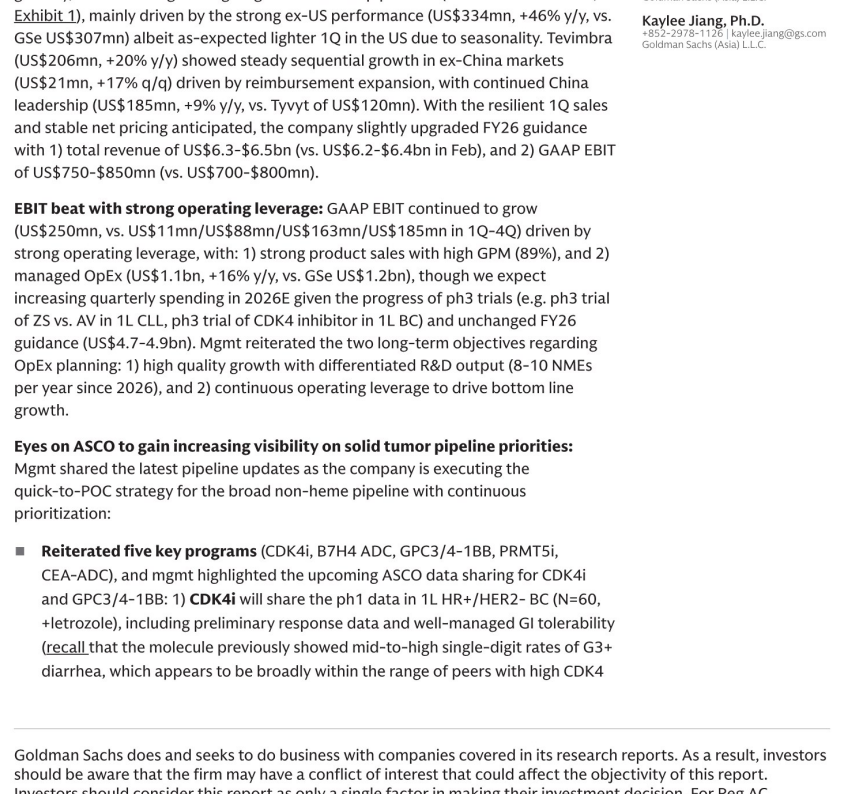
Exhibit 2
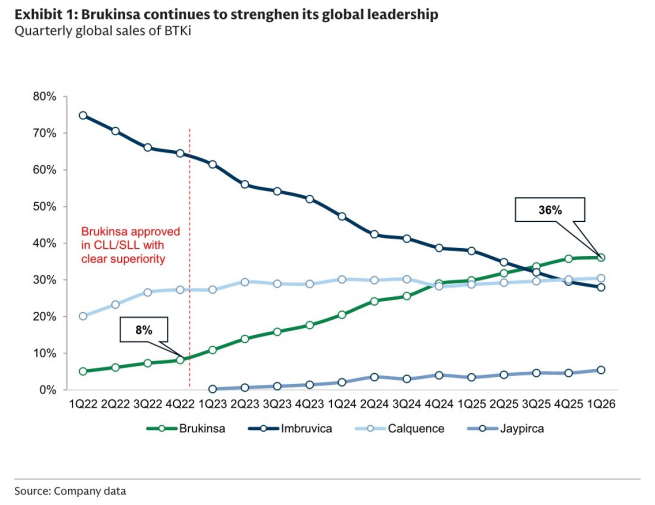
Exhibit 3