UBS Global Gas: Storage Rebuilds Uneven
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
UBS observes that global natural gas storage rebuilds are progressing unevenly, creating regional supply disparities. In Europe, storage refill rates are trailing historical averages. By early June, storage levels reached only 65% capacity, down from 72% in the prior year. This sluggish replenishment stems from declining Russian pipeline gas deliveries, which fell 15% year-over-year, and intense competition for global liquefied natural gas (LNG) cargoes.
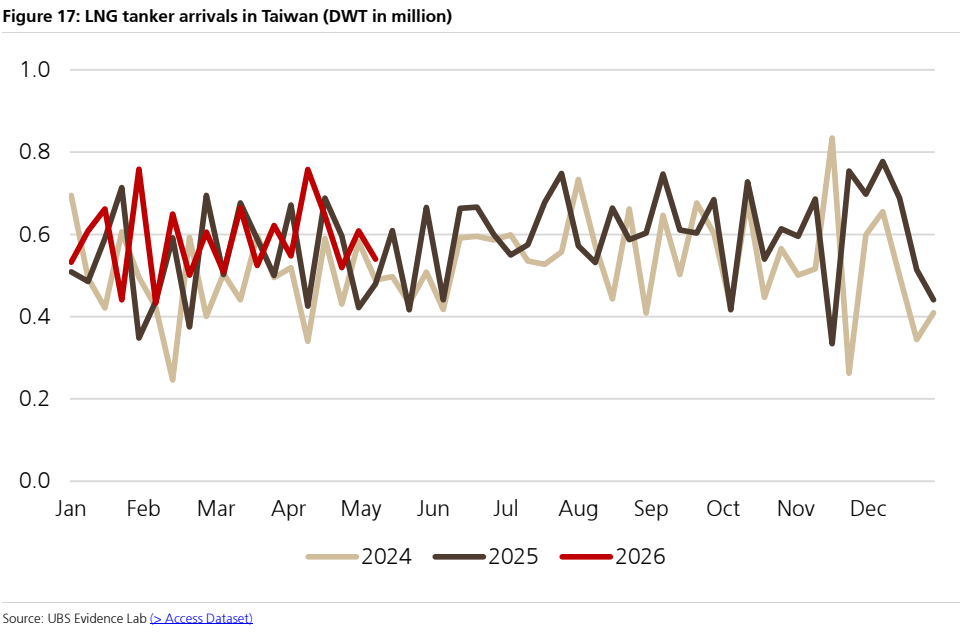
Meanwhile, Asian LNG demand has surged unexpectedly, climbing 8% year-over-year in the first half of 2026. This robust recovery is driven by industrial gas consumption in China and India, widening the spread between Asian JKM and European TTF prices to $5 per million British thermal units. The supply side offers little relief, with global LNG capacity additions limited to 20 million tons, primarily from the United States and Qatar.
In the United States, dry gas production growth is stalling. May 2026 output dipped 0.5% month-over-month as producers maintain strict capital discipline. Total global gas inventories currently sit approximately 3% below the five-year average.
UBS anticipates that this tightening fundamental backdrop will push prices higher. The firm forecasts 2.5% global demand growth against a mere 1.8% supply expansion for 2026. Weather patterns, particularly El Niño effects driving summer cooling needs, remain the key near-term variable.
Key exhibits
Exhibit 1
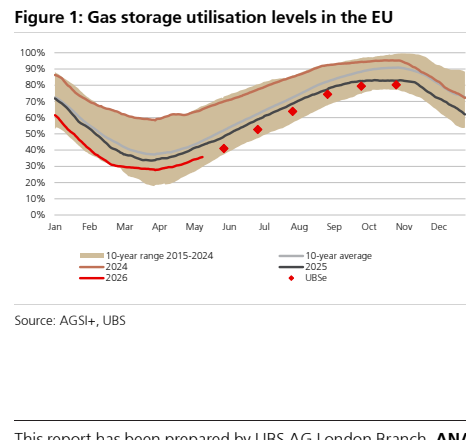
Exhibit 2

Exhibit 3

Exhibit 4
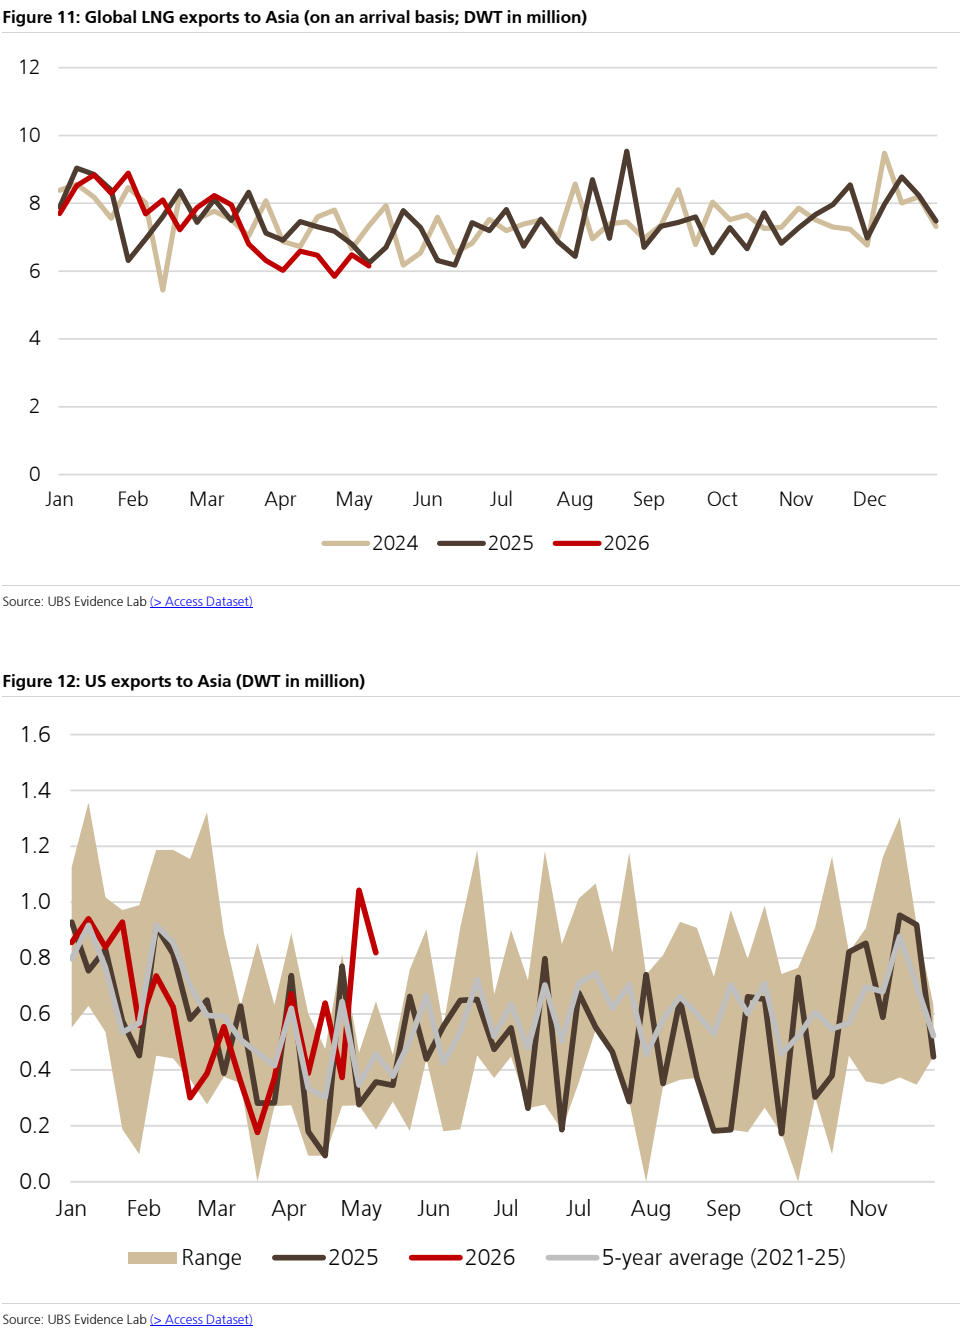
Exhibit 5
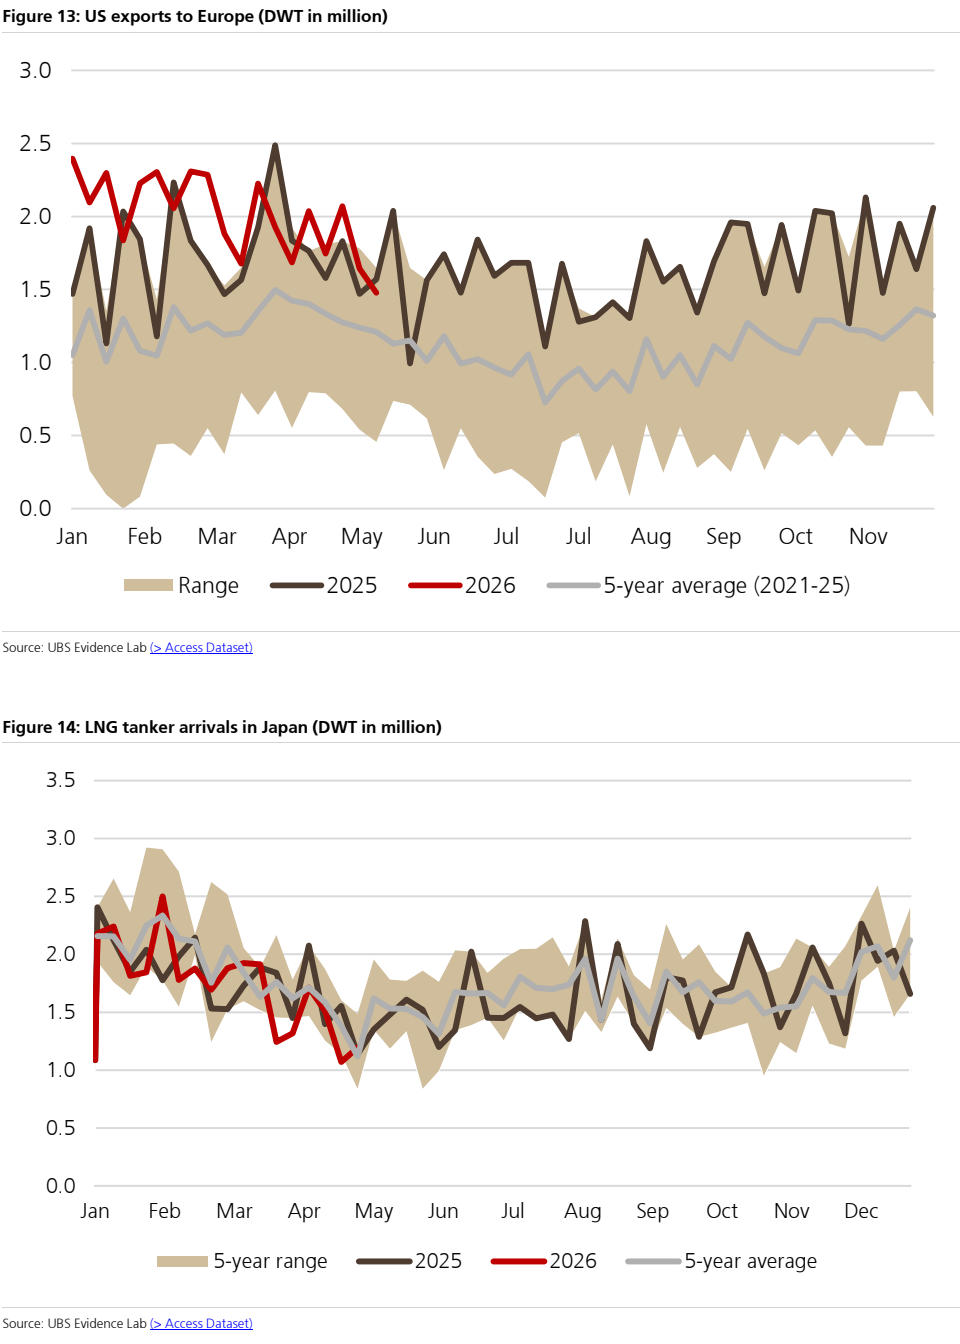
Exhibit 6
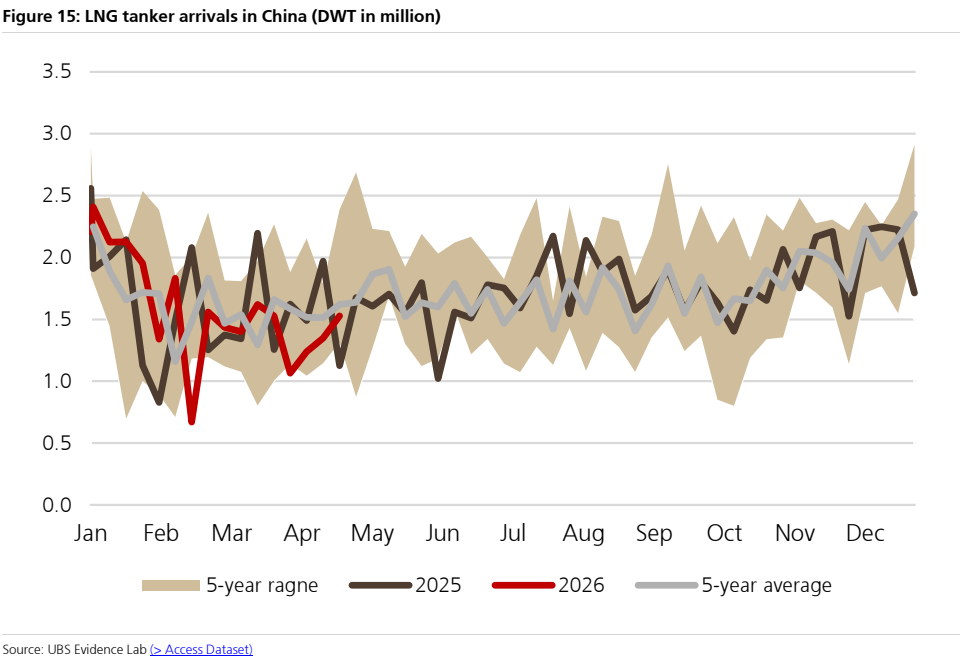
Exhibit 7

Exhibit 8