BofA: Seagate Technology F4Q26 Preview — Pricing Can Drive Upside; PO Raised to $1,150
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
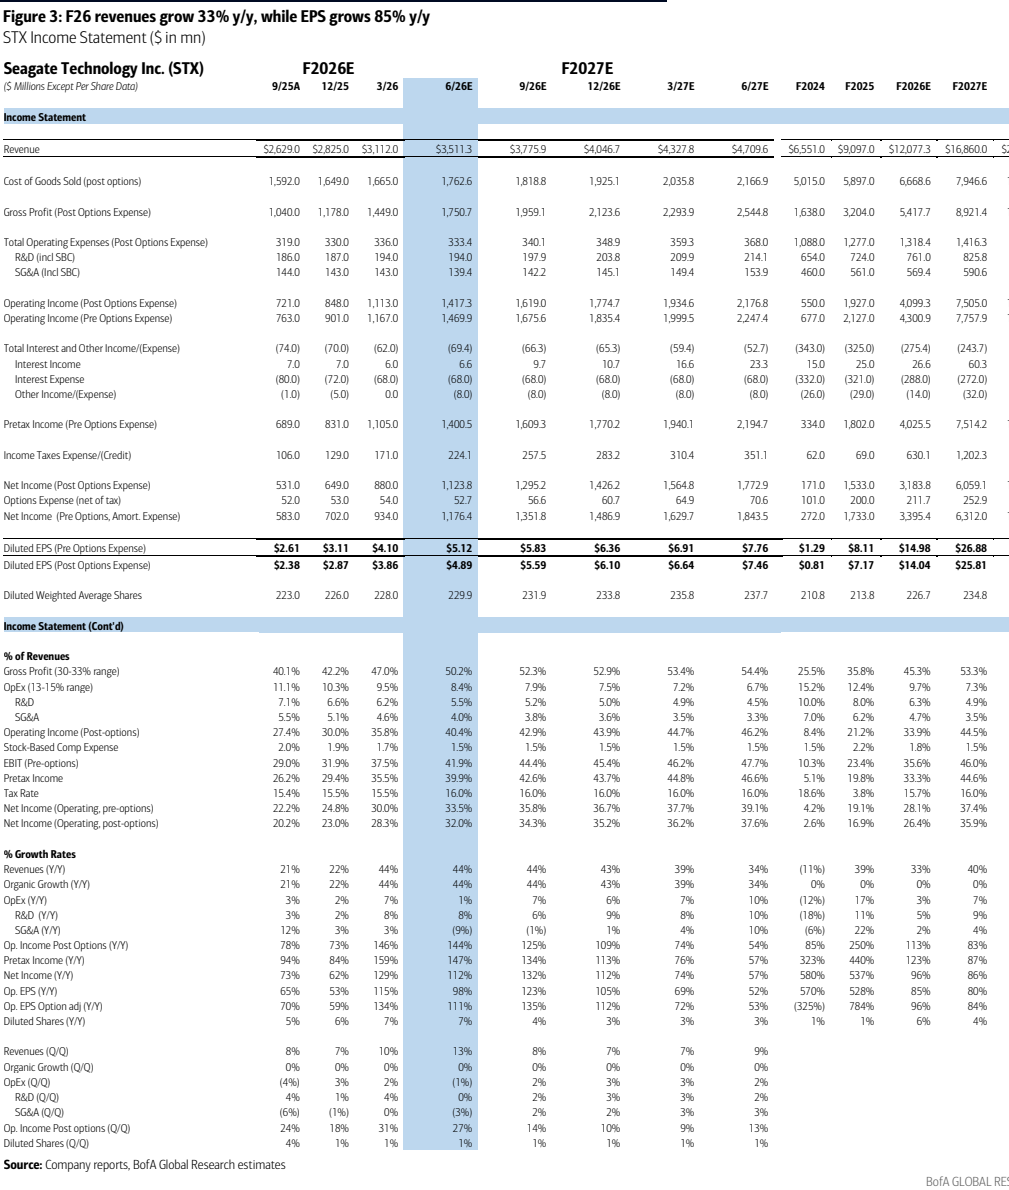
BofA reiterates a Buy rating on Seagate Technology (STX) and raises the target price from $1,000 to $1,150, based on 19x calendar 2028 EPS of $61.24. The firm expects F4Q26 revenue of $3.51 billion and EPS of $5.12, slightly above the consensus of $3.49 billion and $5.11. For F1Q27, revenue is projected at $3.78 billion with EPS of $5.83, compared to consensus estimates of $3.74 billion and $5.77.
The HDD industry is exhibiting greater capacity discipline, focusing on exabyte growth rather than adding unit capacity, which supports a healthy pricing environment. The majority of Seagate's nearline HDD orders are build-to-plan contracts, and renewals are expected to bring moderate but sustainable price increases. With factory utilization at full capacity, future growth must come from higher-capacity drives, favorable pricing, and the migration toward HAMR technology, which lowers per-terabyte costs.
Management's F1Q guidance is expected at approximately $3.7 billion plus or minus $100 million in revenue, a gross margin of 51-53%, and EPS of $5.75 plus or minus $0.20. F27 estimates are revised upward to $16.9 billion in revenue and EPS of $26.88. Free cash flow is projected at $2.7 billion for F26 and $4.5 billion for F27.
Key exhibits
Exhibit 1