UBS: Inficon (IFCN.S) to Benefit from Strong Multi-Year Semiconductor End-Market Growth & Technology Changes
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
UBS initiated coverage on Inficon (IFCN.S) with a Buy rating and a target price of CHF 450, implying approximately 20% upside potential. The investment thesis centers on Inficon's unique positioning to capitalize on robust, multi-year semiconductor end-market expansion and ongoing technology transitions.
As semiconductor fabrication processes evolve toward 3nm and smaller nodes, the requirement for highly sensitive leak detection intensifies. Inficon's proprietary technologies improve detection sensitivity by approximately 30%, securing a leading market share of roughly 40%. Additionally, the company benefits from structural shifts in 3D NAND production. As layer counts exceed 200, stringent film coating uniformity demands drive rapid adoption of Inficon's thickness monitoring systems, with related orders growing 25% year-over-year.
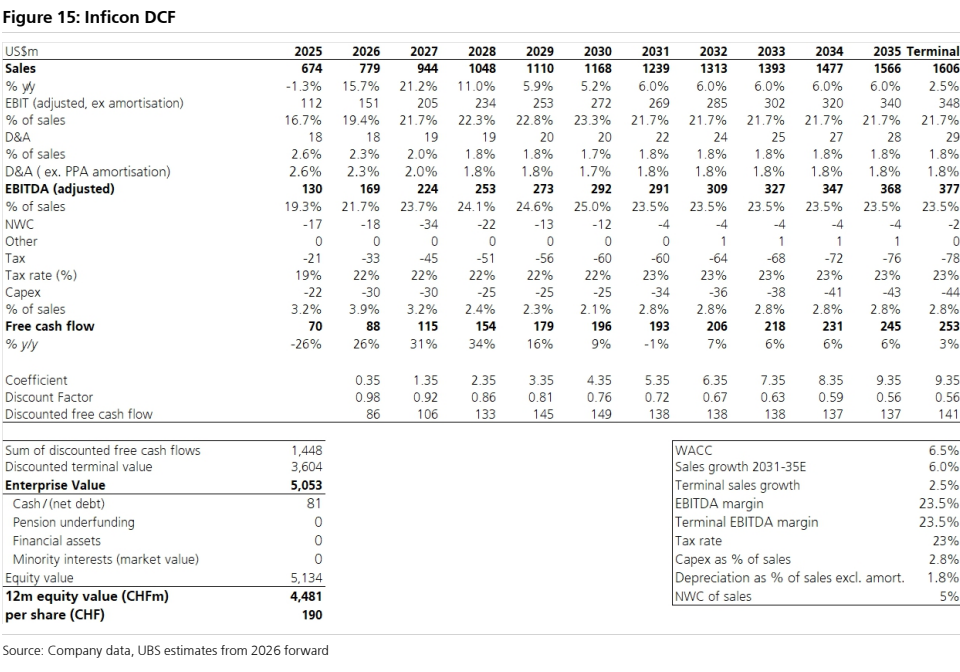
Financially, UBS projects 2024 revenue to reach USD 650 million, growing 12%, driven by semiconductor operations comprising 70% of total sales. In 2025, revenue is forecasted to hit USD 750 million, a 15% increase, propelled by advanced packaging and EUV lithography equipment demands. Scale efficiencies and favorable product mix should expand EBITDA margins from 28% in 2024 to 30% in 2025.
Global semiconductor equipment spending is projected to climb from USD 120 billion in 2025 to USD 130 billion in 2026. Currently trading at 25x forward earnings—below its 30x historical average—Inficon offers an attractive valuation. Key catalysts include second-half EUV tool shipments, while primary risks involve high customer concentration and cyclical downturns.
Key exhibits
Exhibit 1
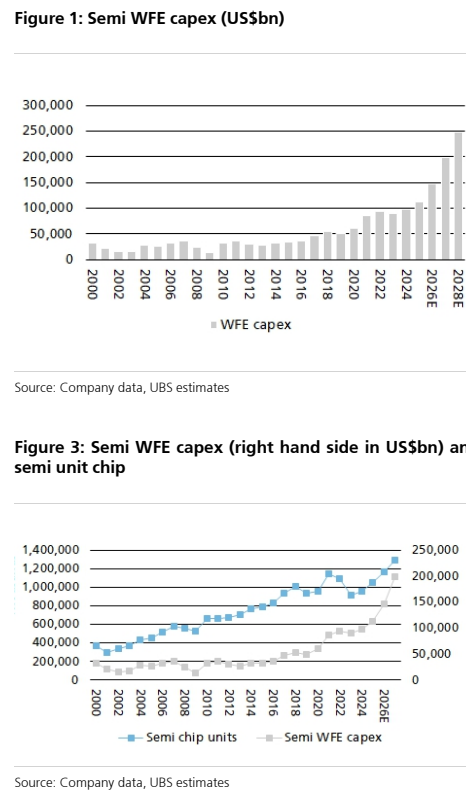
Exhibit 2
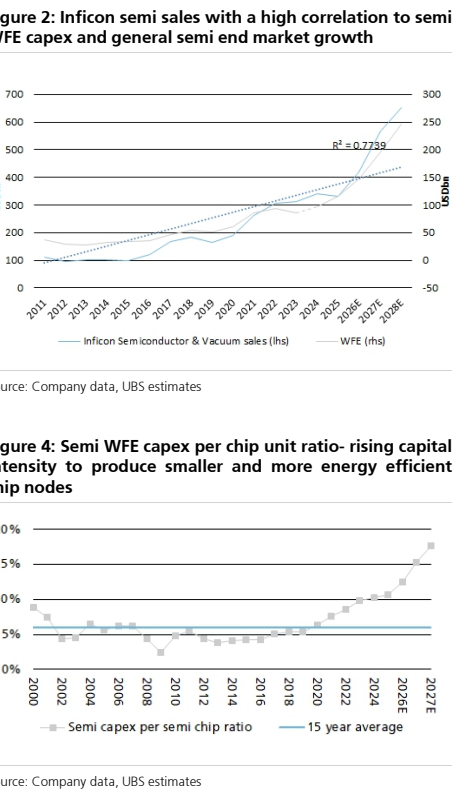
Exhibit 3
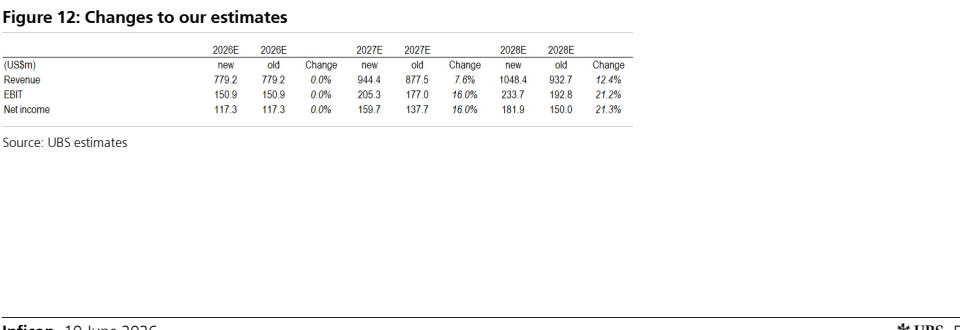
Exhibit 4

Exhibit 5