Morgan Stanley Global CLO Strategy: CLO Tracker October 2026 – Keep Calm and Carry On
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Morgan Stanley's October 2026 CLO Tracker reviews a global CLO market where macro volatility widened AAA spreads, yet CLO AAA paper outperformed other securitized credit such as CMBS, prime auto and non-QM. With rate volatility elevated and expectations of further rate hikes strengthening, the bank views CLO AAA as an ideal cash parking spot, supported by healthy earnings trends that offset fundamental pressure from higher rates. CLO ETF inflows accelerated to $3.2 billion in September, the strongest monthly intake since early 2025. The leveraged loan market is bifurcating, which the report expects to drive further dispersion in mezzanine spreads, and it stays cautious on BB tranches, where the interquartile range of spreads approaches 200 basis points. Median NAV for US CLO 2.0 BSL deals fell 2.4% to 44.7% at end-September, while European CLO 2.0 BSL medians fell 1.3% to 42.3%. TRACE IG CLO/CDO volumes rose 47.6% month-over-month to $30.4 billion. US CLO 2.0 portfolios saw collateral priced below 90 climb 0.1 percentage point to 9.2%. Morgan Stanley maintains its preference for CLO AAA and expects a steeper CLO credit curve; should high rates persist and aggregate demand slip, the default cycle could deepen and broaden.
Key exhibits
Exhibit 1
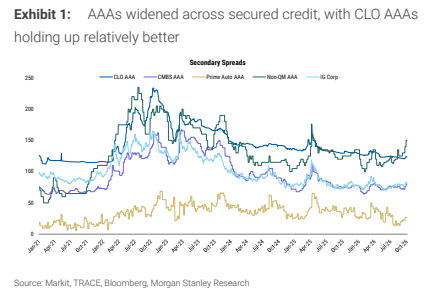
Exhibit 2
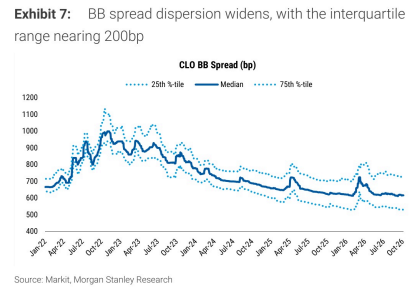
Exhibit 3
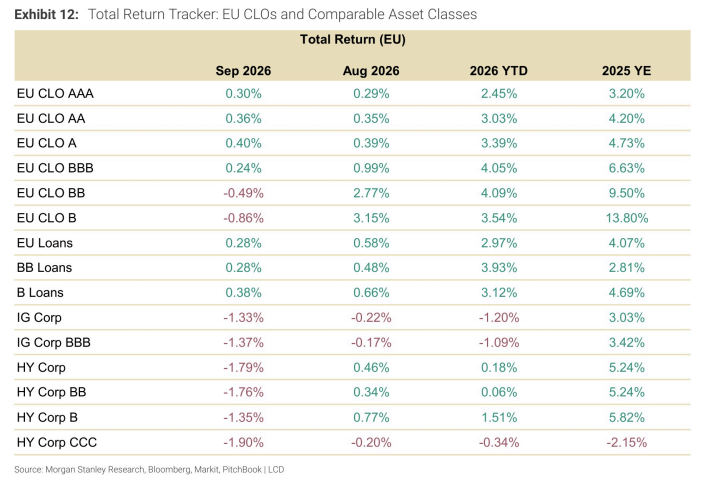
Exhibit 4
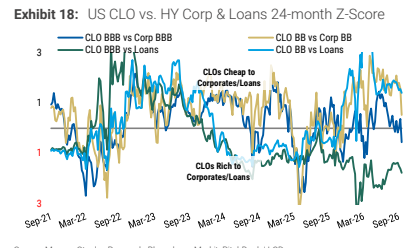
Exhibit 5

Exhibit 6
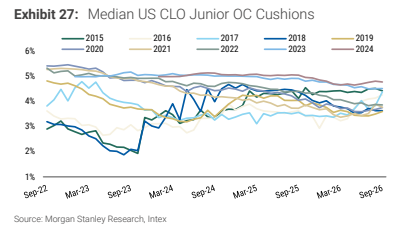
Exhibit 7
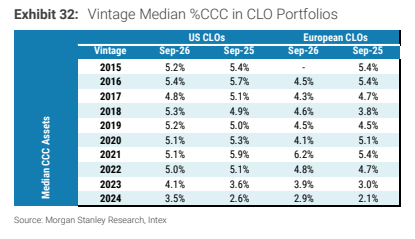
Exhibit 8
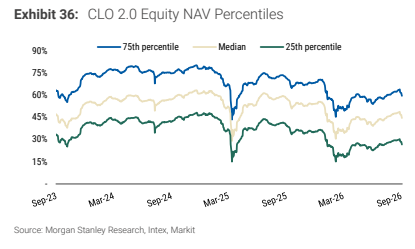
Exhibit 9

Exhibit 10

Exhibit 11

Exhibit 12
