Morgan Stanley JD.com (JD.US): Q3 2026 Results Expected In Line
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
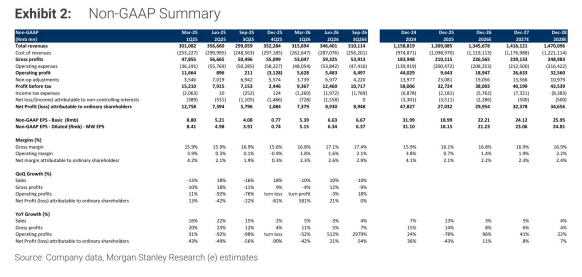
Morgan Stanley expects JD.com's Q3 2026 results to be in line, modeling JD Retail revenue growth of 3.2% year-over-year—an improvement from the 5% decline in Q2—and operating margin roughly flat YoY, as gross-margin expansion is offset by higher R&D and fulfillment expense ratios. Electronics and home appliances revenue should return to about -1% YoY, while general merchandise growth accelerates to 7%, with supermarket up 9–10%. New-business losses are expected to narrow sequentially to RMB 9.6 billion, as food-delivery losses shrink to roughly RMB 5.8 billion, with further reduction toward about RMB 5 billion or below possible in Q4. Q4 JD Retail revenue growth is seen improving moderately to 6%, though rising R&D—including AI infrastructure investment—and fulfillment costs, JoyBuy expansion losses, and soft consumption keep outcomes uncertain. Morgan Stanley views JD as the least favorably positioned China e-commerce name over the next 12 months and maintains Underweight with a $25.00 target, implying 8x 2026E non-GAAP P/E, which it deems unattractive against a 9% earnings CAGR.
Key exhibits
Exhibit 1
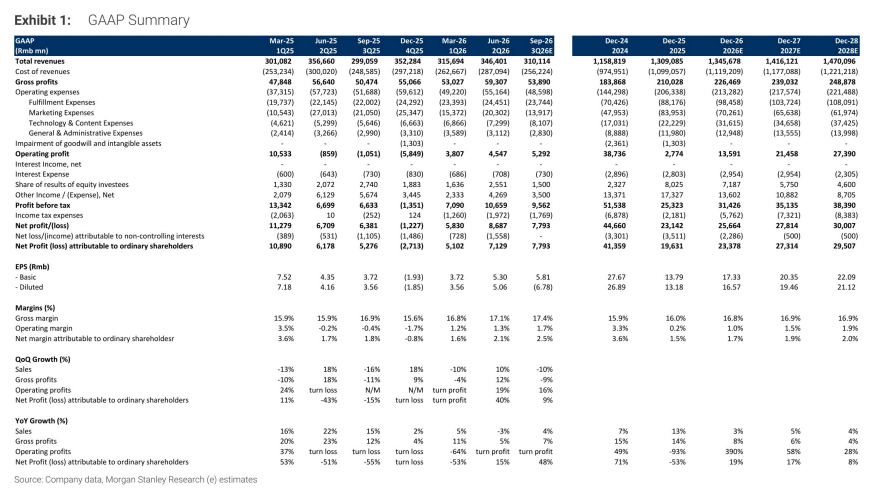
Exhibit 2