Goldman Sachs: Tokyo Electron (8035.T) 4Q Beat, FY3/27 Outlook Strong; Reiterate Buy
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Goldman Sachs published an earnings review for Tokyo Electron (8035.T), highlighting a fourth-quarter beat and a robust fiscal year 2027 outlook that should alleviate lingering market concerns. The firm reiterated its Buy rating with a target price of 45,000 yen, based on a 20x price-to-earnings multiple for 2027.
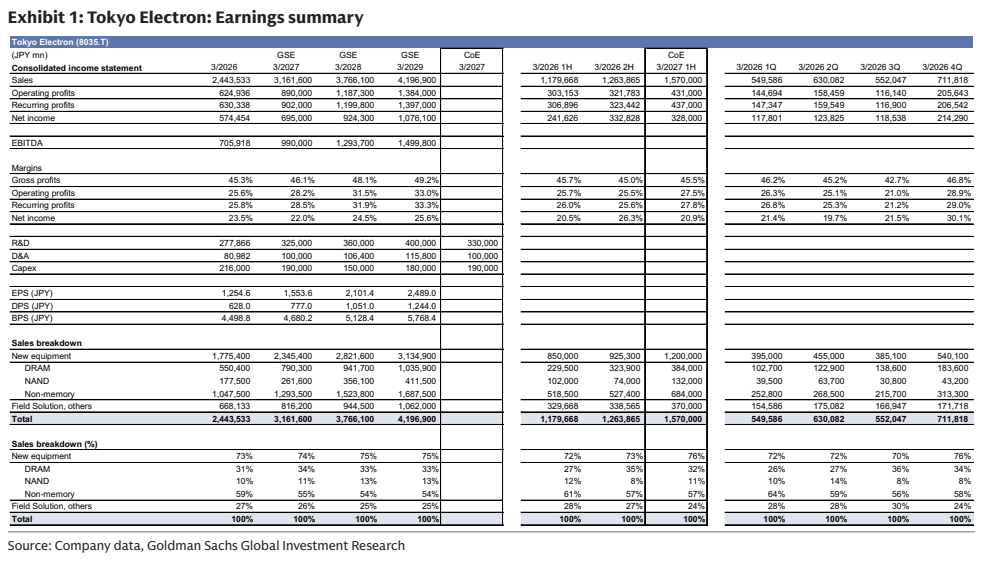
Fourth-quarter revenue surpassed market expectations by 10%, primarily driven by strong demand for DRAM and NAND manufacturing equipment. Gross margins improved by 2 percentage points quarter-over-quarter to reach 45.5%, reflecting favorable product mix optimization. Additionally, orders surged 20% sequentially, with artificial intelligence-related equipment now comprising 30% of the total order book. Revenue from the Chinese market remained stable at a 25% share, demonstrating resilience against potential export control headwinds.
Looking forward to fiscal year 2027, management issued strong revenue guidance projecting 15% year-over-year growth, outpacing the market consensus of 12%. The company plans to increase research and development spending by 8%, focusing on advanced process equipment. Capital expenditures are guided at 80 billion yen for capacity expansion. Management also announced a 10% year-over-year dividend increase to 200 yen per share. Key geopolitical uncertainties and potential delays in customer capital expenditures remain the primary risk factors. Overall, Goldman Sachs believes these positive operational signals will effectively dissipate market anxieties regarding a cyclical peak in semiconductor demand.
Key exhibits
Exhibit 1