UBS: Accton Technology (2345.TW) — Multiple Drivers from AI Infrastructure and High-Speed Networking; Initiate at Buy
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
UBS initiates coverage of Accton Technology (2345.TW) with a Buy rating and a target price of NT$800, implying approximately 30% upside. As a global leading network switch ODM, Accton is strategically positioned in the AI data center high-speed networking market.
The firm projects a 25% EPS CAGR for 2025–2027, driven by multiple catalysts. The 800G switch ramp, expected to begin volume shipments in the second half of 2025 and become a major revenue contributor in 2026, coincides with an accelerated 400G to 800G upgrade cycle fueled by AI training and inference clusters. Additionally, the AI accelerator business, including GPU baseboards, is forecast to contribute 10% of revenue in 2025, expanding to 15% in 2026. This diversification opens a second growth curve alongside the core networking franchise.
In 2024, the company posted 18% year-over-year revenue growth and 22% net income growth, maintaining a gross margin of approximately 21%. UBS forecasts EPS of NT$15.2, NT$19.8, and NT$24.5 for 2025 through 2027. The NT$800 target price is based on a 40x P/E multiple applied to the 2026 projected EPS of NT$19.8.
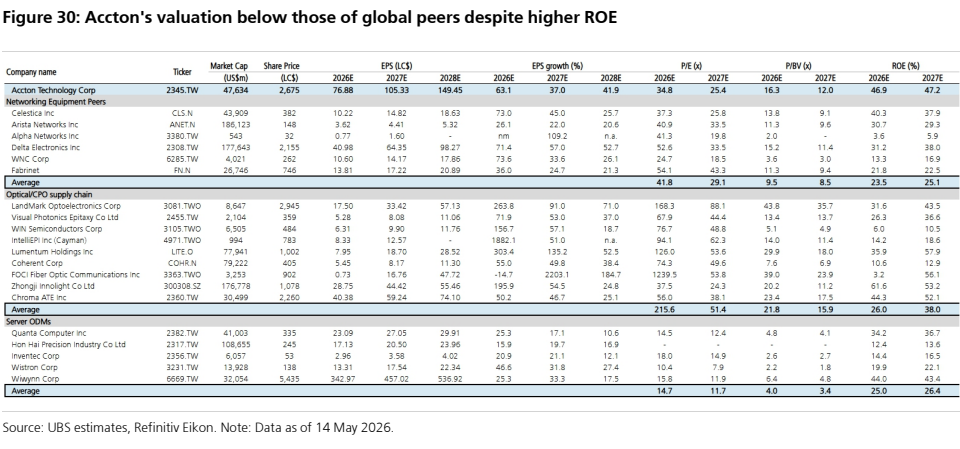
Key customers include Cisco and Arista, with the top five accounting for over 70% of revenue. A new manufacturing facility in Vietnam is slated for 2025 production. Despite high returns on equity, Accton trades at a discount to global peers. Principal risks involve high customer concentration, supply chain disruptions, and potential geopolitical impacts.
Key exhibits
Exhibit 1

Exhibit 2

Exhibit 3
Exhibit 4

Exhibit 5
Exhibit 6
Exhibit 7
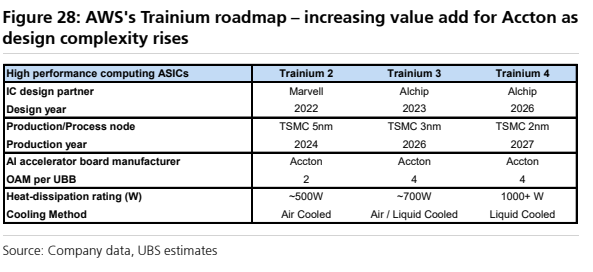
Exhibit 8