Petrochemicals & Chemicals: October 2026 Strategy — Favor Segments Benefiting from Rising Energy Prices and Supply Constraints
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
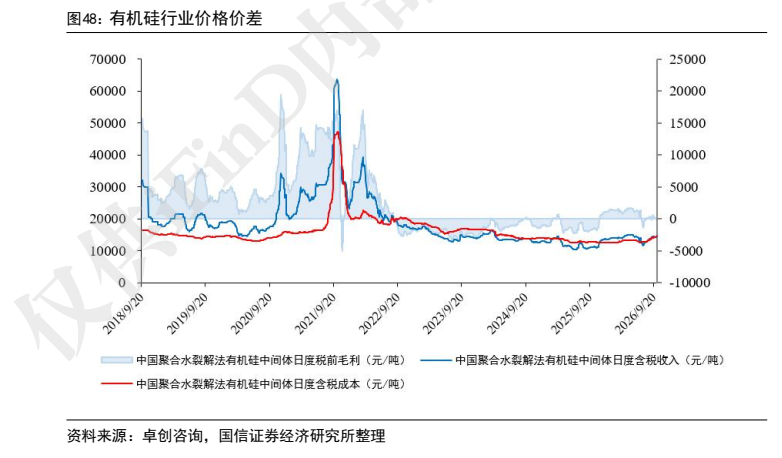
Guosen Securities' October 2026 investment strategy for petrochemicals argues that Middle East geopolitical conflict is curbing global crude supply, with low inventories amplifying price elasticity; it expects 2026 Brent and WTI price centers at USD 80-100 per barrel. Disruption to shipping through the Strait of Hormuz and the Bab el-Mandeb Strait tightens supply further, supporting upstream producers. China's chemical industry is exiting its large-scale capacity expansion cycle, the supply structure keeps improving, and supply-demand is shifting from surplus to structural tight balance; the domestic chemical product price index (CCPI) rose month over month, and domestic demand is steadily recovering while advanced-manufacturing demand is released. The report recommends oil, refining, dyes and organic silicon as key segments: methanol spot supply remains tight with prices likely to stay high; dye industry concentration is rising, benefiting top producers; organic silicon makers are coordinating output cuts, keeping supply-demand in tight balance with prices expected to rise further; and refined-product tightness should persist. Rated Outperform: CNOOC, PetroChina, Satellite Chemical, Guanghui Energy, Hengyi Petrochemical and Zhejiang Longsheng.
Key exhibits
Exhibit 1
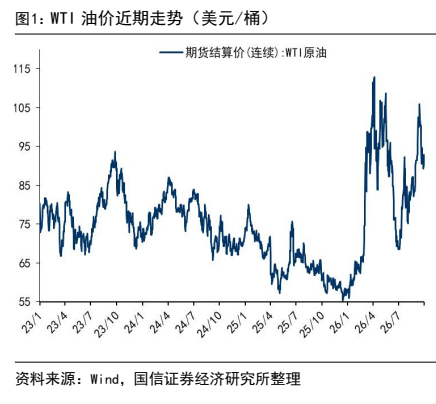
Exhibit 2
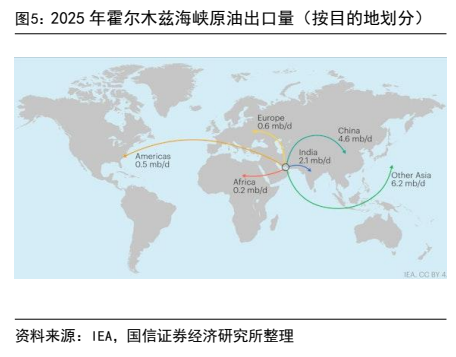
Exhibit 3
Exhibit 4
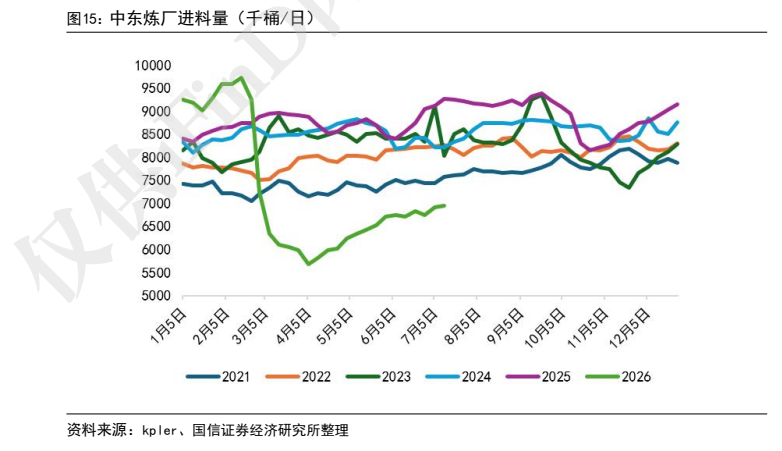
Exhibit 5
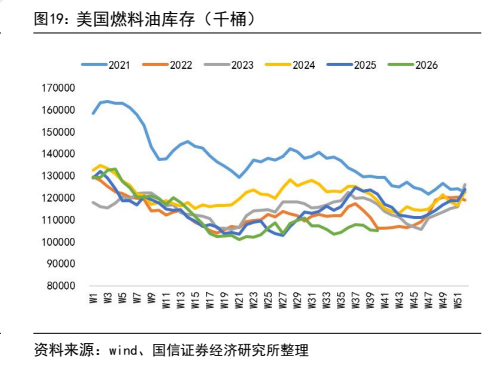
Exhibit 6
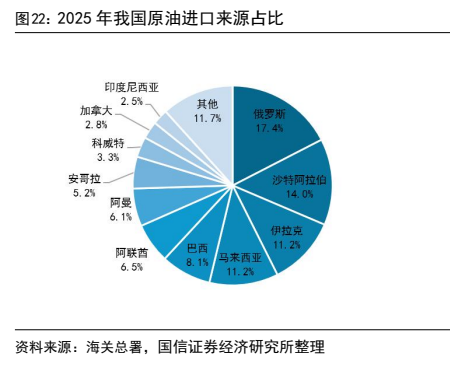
Exhibit 7
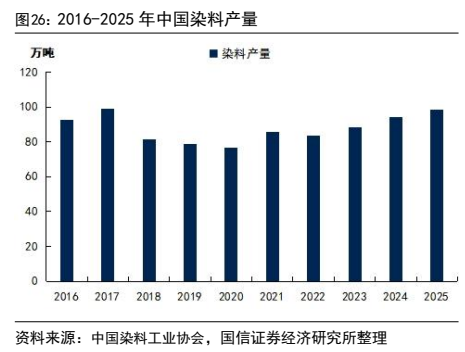
Exhibit 8
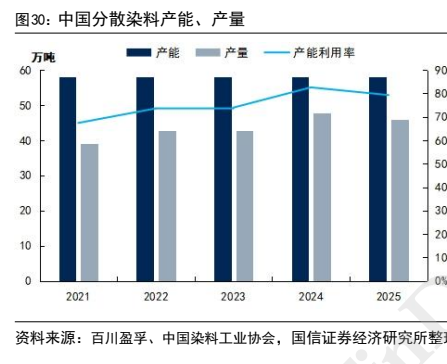
Exhibit 9
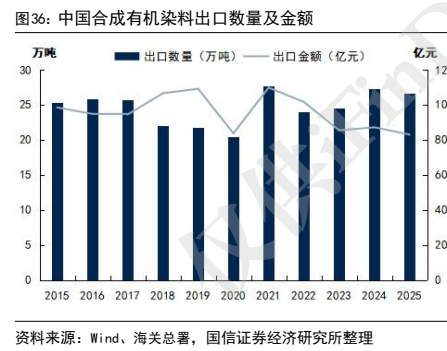
Exhibit 10
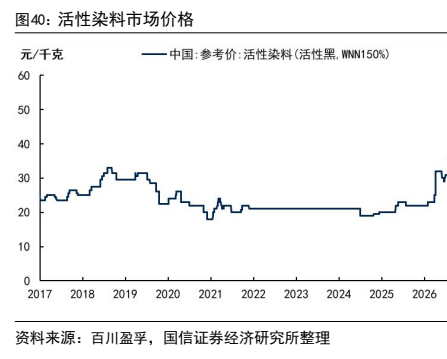
Exhibit 11
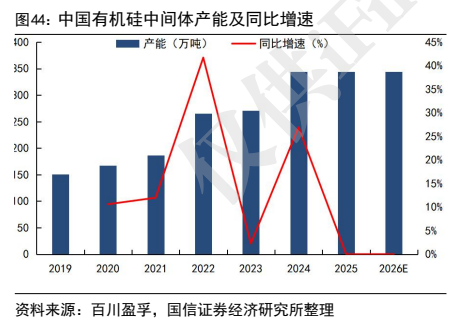
Exhibit 12