Goldman Sachs | Korean Entertainment: 3Q26 Preview - HYBE Powered by Tours; JYP Recovery Milder
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
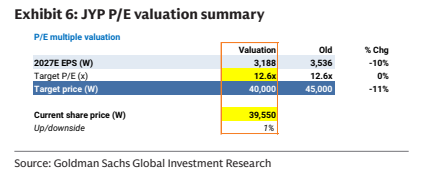
Goldman Sachs expects divergent third-quarter 2026 results across the Korean entertainment sector. HYBE is forecast to post revenue of KRW 1.5 trillion, up 102% year-on-year and 1% quarter-on-quarter, propelled by BTS stadium tours across North America and Europe and related merchandise sales. Operating profit is projected at KRW 160 billion, swinging to a year-on-year profit but down 6% sequentially, as concert-related production and artist costs temper margin expansion. JYP's recovery looks milder: revenue of KRW 236 billion (+1% YoY, +29% QoQ) and operating profit of KRW 39 billion (-4% YoY, +27% QoQ), with the Stray Kids comeback offset by delayed album recognition, as some Western-market shipments slip into 4Q26 or 1Q27, an unfavorable concert mix and investment in new artists. Goldman cut JYP's 2026E-2028E revenue forecasts by 13%, 7% and 9%, and operating profit by 28%, 13% and 23%. The bank maintains Buy on HYBE with a KRW 300,000 target price and downgrades JYP to Neutral, cutting its target from KRW 45,000 to KRW 40,000. In 4Q26, HYBE's continuing tour schedule and release lineup should support revenue, while JYP faces tougher comparisons on a lighter slate.
Key exhibits
Exhibit 1
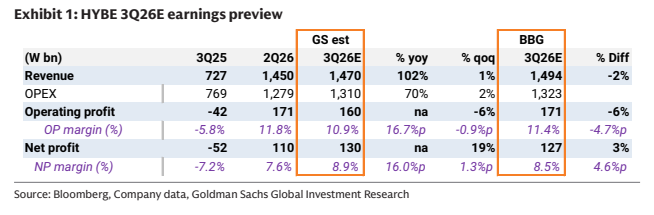
Exhibit 2
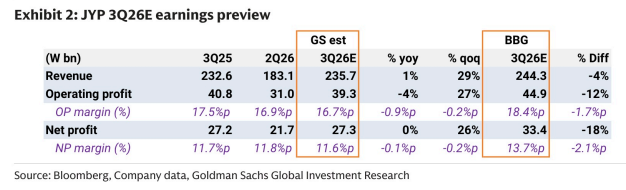
Exhibit 3
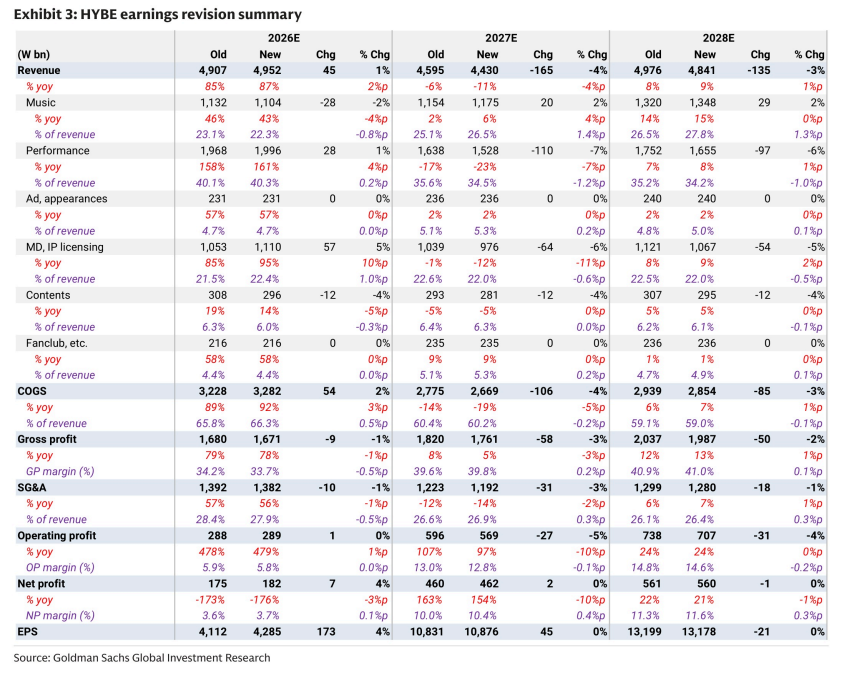
Exhibit 4
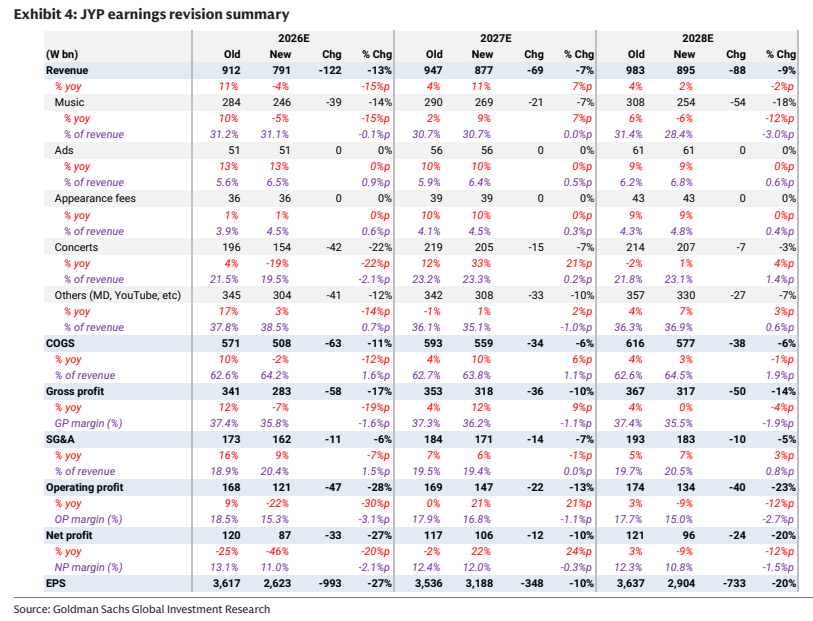
Exhibit 5
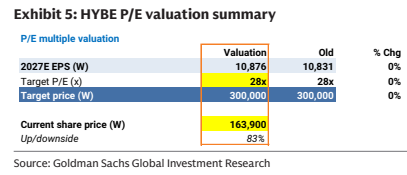
Exhibit 6