UBS on BE Semiconductor Industries (BESI.AS): Addressing the Key Questions Behind Our Sell Downgrade
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
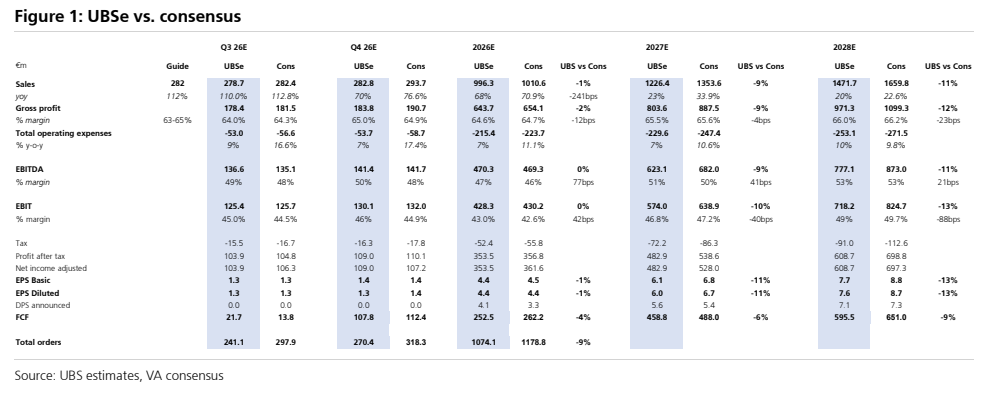
UBS responds to market feedback following its downgrade of BE Semiconductor Industries (BESI.AS) to Sell and previews Q3 results due October 22, 2026. While investors remain optimistic about hybrid bonding adoption in logic and photonics, UBS's bottom-up demand and capacity model suggests the market overestimates incremental tool demand and underestimates existing capacity at TSMC and Intel. UBS expects Q3 orders to come in 19% below consensus and highlights two underappreciated downside risks to memory hybrid bonding adoption. The analyst expects non-hybrid bonding revenue to grow at roughly a 21% CAGR over 2026-2028, but not enough to offset hybrid bonding weakness. UBS assumes Besi retains a majority share in die-to-wafer bonding and does not view new entrants such as ASML as direct competitors. Order momentum and visibility into memory customers' HBM roadmaps over the coming quarters should challenge current expectations, with potential updates at upcoming industry conferences. The target price stays at €159.00, implying downside from the October 9 close of €179.50.
Key exhibits
Exhibit 1