Goldman Sachs: China Banking – 1H26 Credit Growth and Government Bond Issuance Slow Further; Focus on Balance Sheet Strengthening; Top Picks are Buy-Rated CCB and BOC
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Key Views
Goldman Sachs expects the shift toward lower-yielding corporate loans, intensifying deposit competition, and waning benefits from deposit repricing in 2H26 to pressure bank margins. Future differentiation will depend increasingly on NPL coverage improvement and endogenous capital accumulation. Large banks are better positioned given their longer deposit repricing cycles.
Recommended Securities
- CCB A-share: Buy (RMB 10.00)
- CCB H-share: Buy (HKD 8.17)
- BOC A-share: Buy (RMB 5.88)
- BOC H-share: Buy (HKD 5.04)
Key exhibits
Exhibit 1
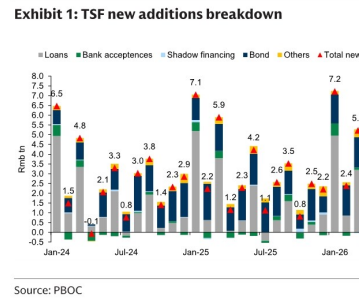
Exhibit 2


Exhibit 3

Exhibit 4
