HSBC Samsung Electronics (005930.KP) Buy: 3Q26 Preliminary Results Better Than Expected
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Samsung Electronics (005930.KP) posted preliminary third-quarter 2026 results that came in better than feared: operating profit of KRW107tn, up 20% quarter-on-quarter and 780% year-on-year, on revenue of KRW195tn, up 14% and 127%. Despite headwinds from Korean won appreciation, an 18% quarter-on-quarter rise in DRAM/NAND prices and stronger seasonal OLED profitability—margins improved from 9% in the second quarter to 14%—supported the beat, though the smartphone business recorded a quarterly loss on rising memory and application processor component costs. HSBC maintains Buy and a KRW450,000 target price, arguing the memory supercycle and improving foundry margins will keep strengthening competitiveness. It expects fourth-quarter DRAM ASPs to rise 7% quarter-on-quarter, underpinning KRW123tn of quarterly operating profit, with HBM demand robust and 2027 HBM blended ASPs forecast up 65% year-on-year. Foundry should reach breakeven from 2028 at around 90% utilisation. Further forecasts: 2026 memory capex up 32%, eSSD at 46% of total NAND demand by 2028, and 38% year-on-year operating profit growth in 2027.
Key exhibits
Exhibit 1
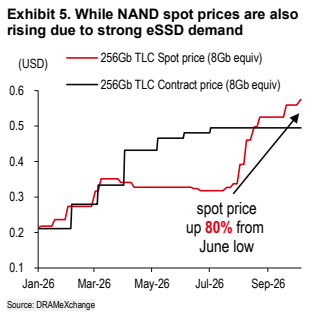
Exhibit 2
Exhibit 3
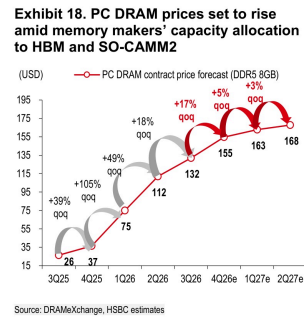
Exhibit 4
Exhibit 5
Exhibit 6
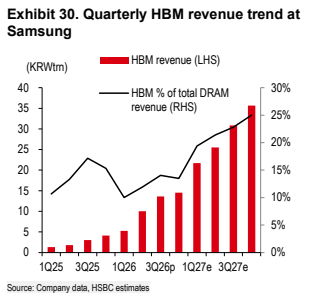
Exhibit 7
Exhibit 8