Goldman Sachs: ZTO Express (ZTO) — 1Q26 Review; Buy Rating Maintained
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
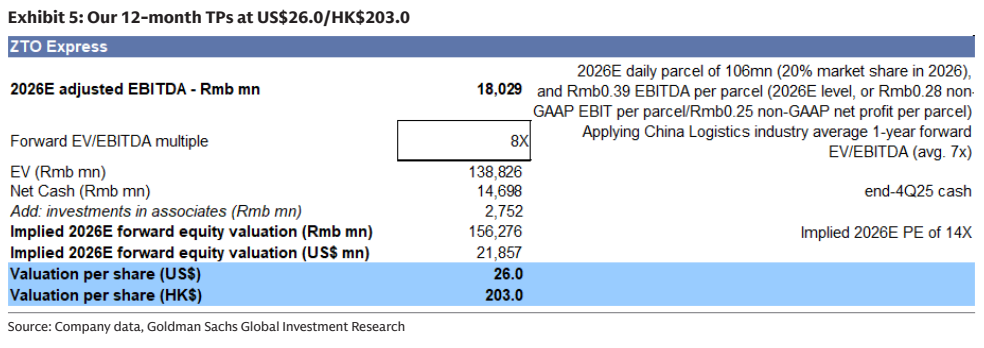
Goldman Sachs maintains a Buy rating on ZTO Express with 12-month target prices of $26.00 for the US ADRs and HK$203.00 for the Hong Kong shares. In the first quarter of 2026, ZTO reported adjusted net income of RMB 2.38 billion, representing a 5.2% year-over-year increase but falling below broader market expectations. This shortfall was primarily driven by a high baseline from one-off other income in the prior year. However, core operating metrics remained robust. Parcel volume grew 13.2% year-over-year, outpacing the industry by 7.4 percentage points and expanding market share to 20.3%. Average selling prices for core express services improved, supported by strong growth in reverse logistics and key account business.
The company is actively leveraging AI to optimize operations. Machine vision now covers 25 sorting centers, reducing sorting errors by over 60%, while smart customer service handles more than 70% of full-link tickets. Furthermore, internal AI agents successfully manage daily inquiries across 80% of network branches, driving meaningful cost efficiencies.
Management reaffirmed fiscal 2026 guidance for parcel volume growth of 10-13% and capital expenditure of RMB 6 billion. Goldman Sachs notes that while anti-involution pricing policies are strengthening, potential share overhangs from Alibaba may create near-term stock volatility. Nevertheless, ZTO has an $800 million shareholder return plan for 2026 to help mitigate this risk. Goldman Sachs raised its revenue forecasts by approximately 3% and maintained its Buy thesis based on the company's market leadership and scalable AI integration.
Key exhibits
Exhibit 1
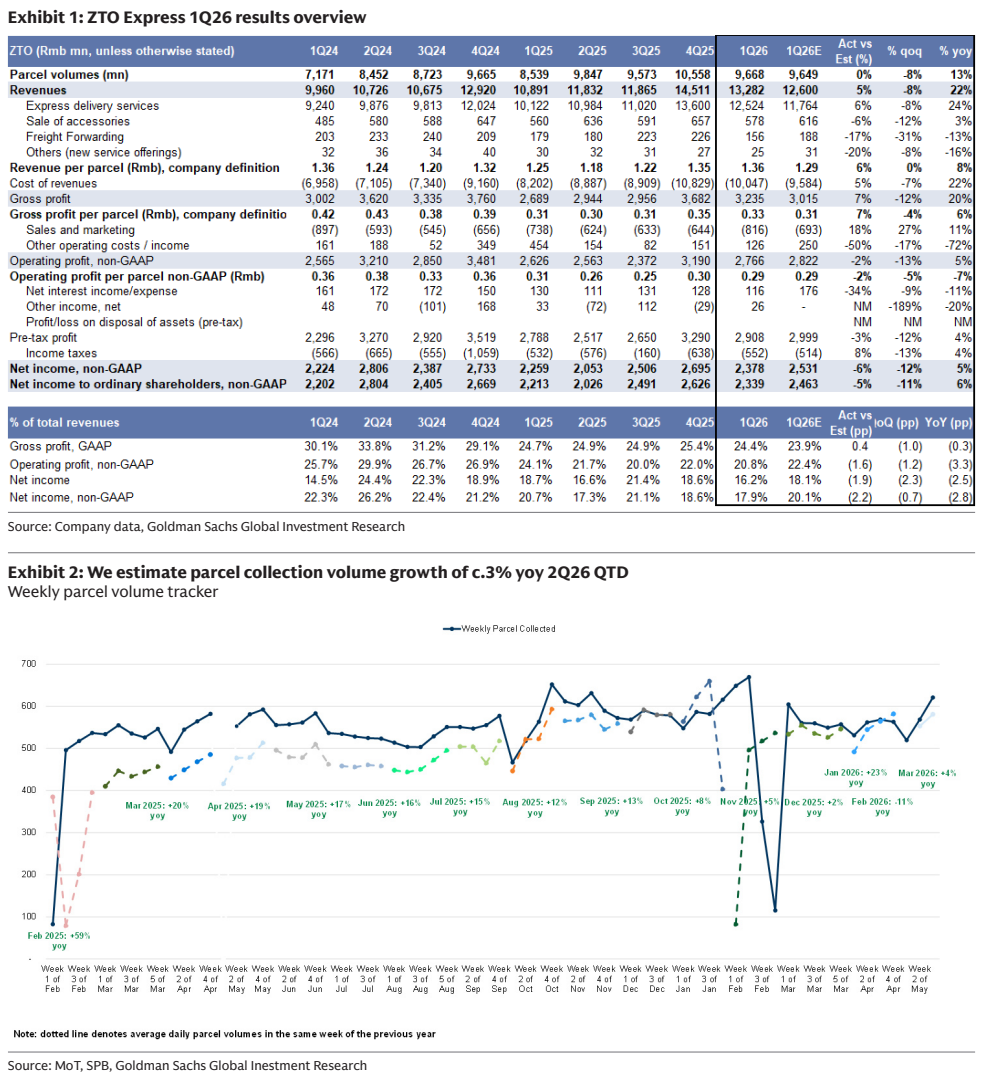
Exhibit 2
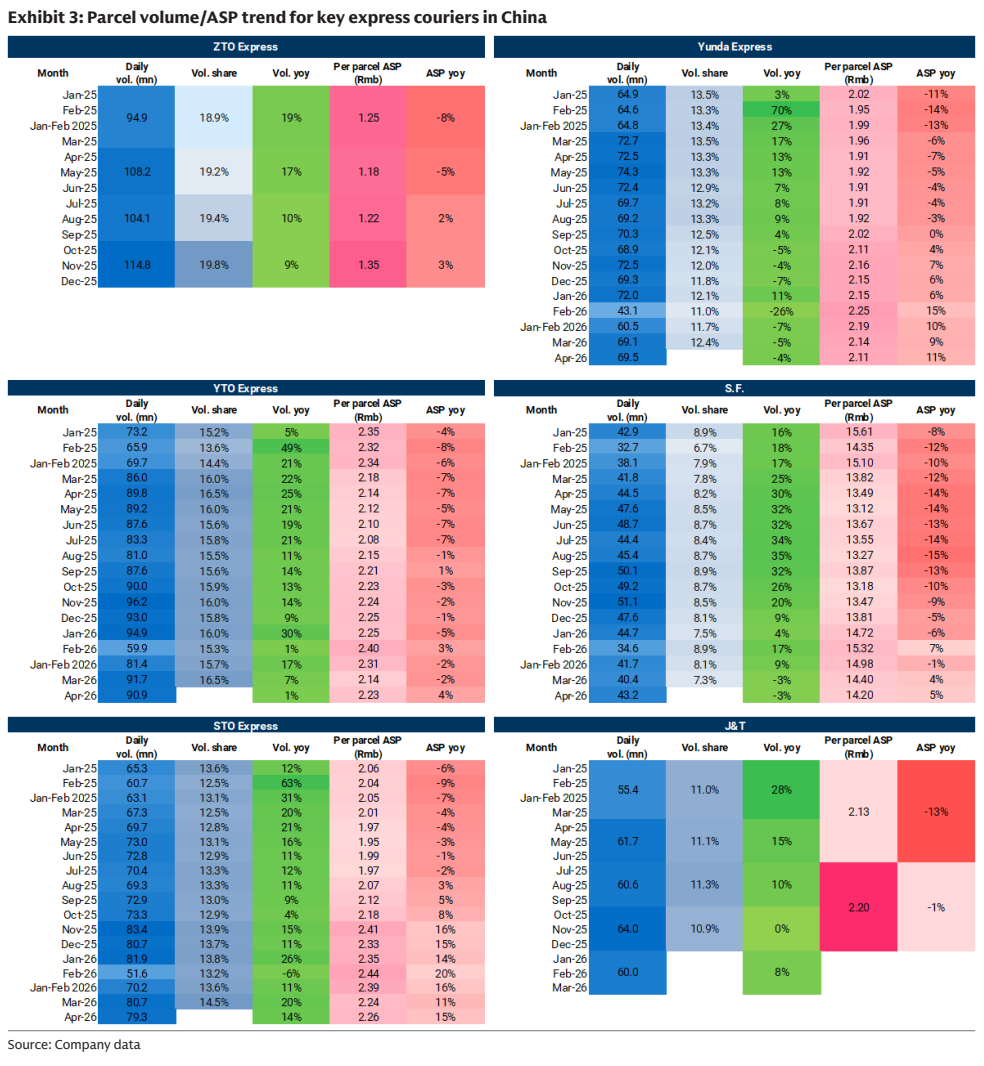
Exhibit 3
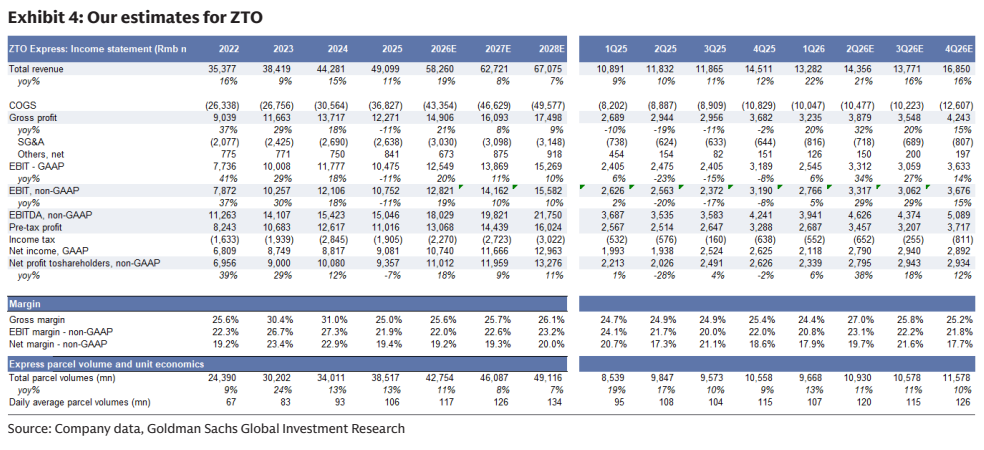
Exhibit 4