Goldman Sachs: Resilient CNY Amid Dollar Strength and Persistently Low China Rates
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Goldman Sachs highlights rising China growth concerns driven by notably weakening domestic demand, yet expects only a limited broad-based easing response. May data showed retail sales declining 0.6% year-on-year and fixed-asset investment falling 10.6%, suggesting April–May real domestic demand growth may have slowed to just 1–2%. Consequently, second-quarter real GDP faces downside risk of falling below 4.5% year-on-year.
Despite this weakness, the 4.5–5.0% growth target range grants policymakers tolerance for short-term softness, keeping the policy reaction function reactive rather than proactive. Support will likely materialize through accelerated fiscal deployment, ample interbank liquidity, and targeted credit.
On currencies, despite the US Dollar Index rising approximately 2% in June, the yuan depreciated only marginally against the dollar. The CFETS basket actually appreciated around 2%, demonstrating that policy anchors continue to favor CNY resilience. Over the summer, USD/CNY is expected to trade range-bound. Exporters' foreign exchange settlement should limit any upside in the pair.
Regarding rates, weak domestic demand and falling oil prices keep rates low, particularly at the front end, supported by ample liquidity. However, accelerated ultra-long government bond supply in the third quarter will constrain long-end yields. Goldman expects the 10-year sovereign yield to range-bound at low levels, while the 10s-30s curve remains relatively steep.
Key exhibits
Exhibit 1
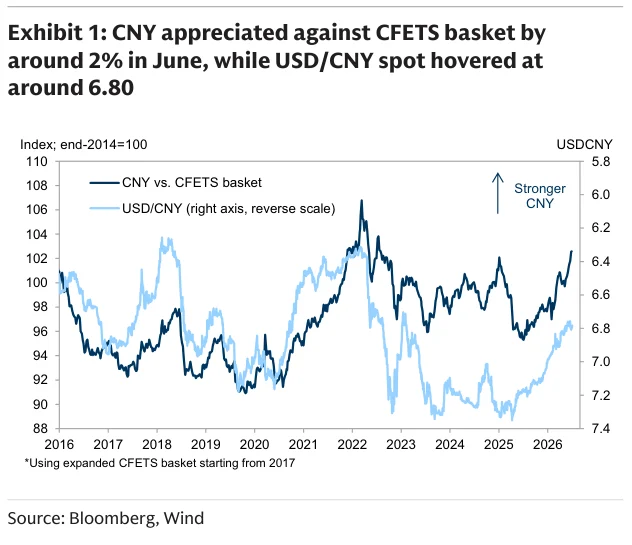
Exhibit 2

Exhibit 3

Exhibit 4
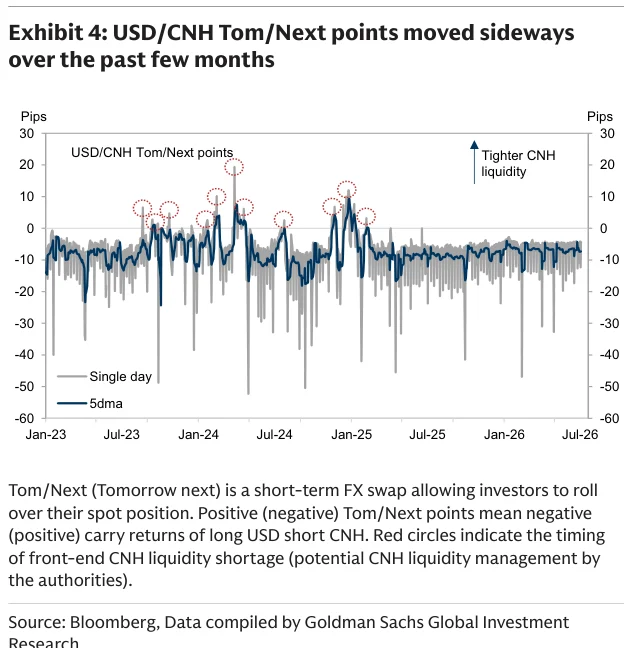
Exhibit 5

Exhibit 6

Exhibit 7
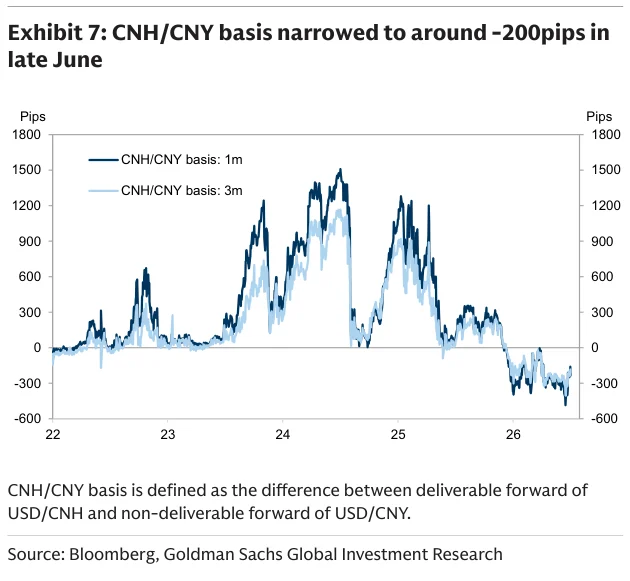
Exhibit 8

Exhibit 9

Exhibit 10
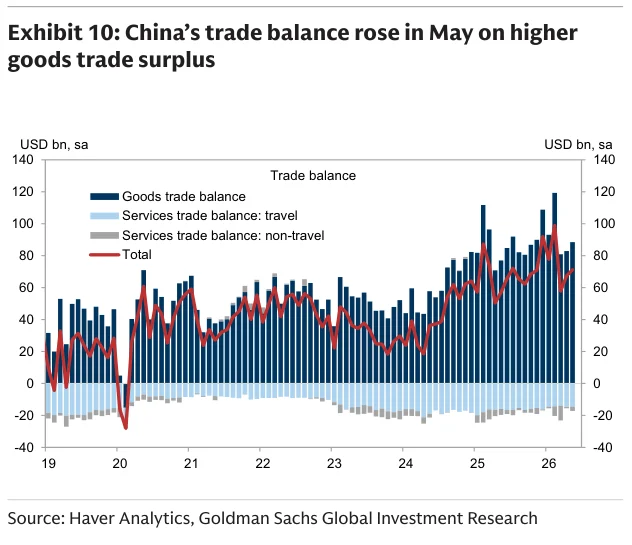
Exhibit 11
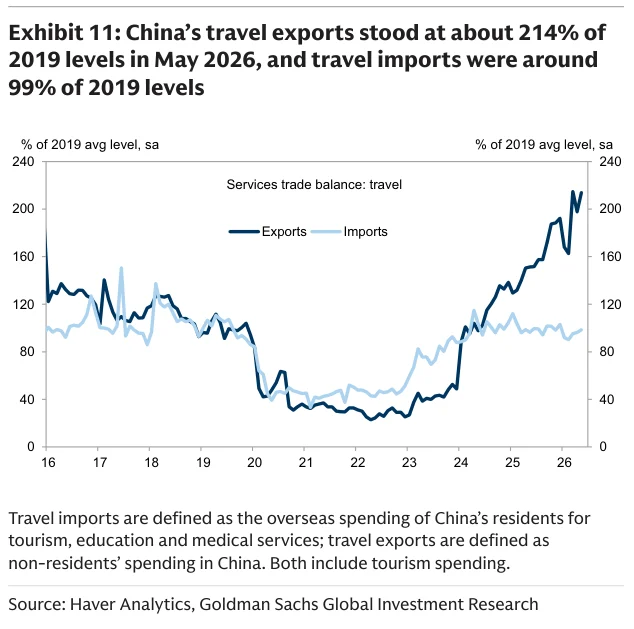
Exhibit 12
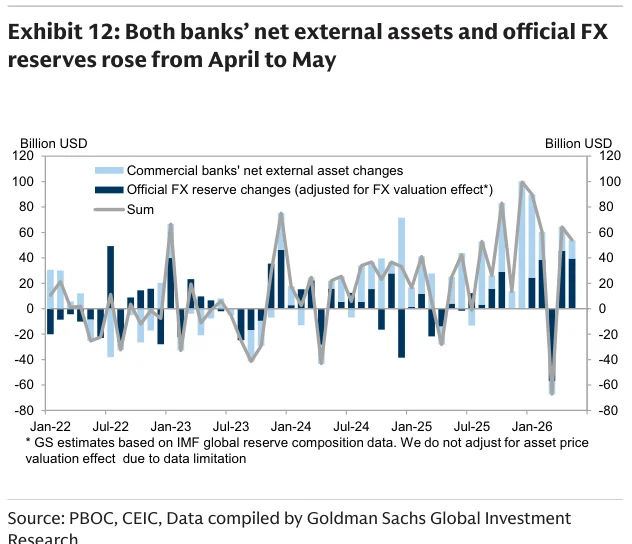
Exhibit 13

Exhibit 14

Exhibit 15

Exhibit 16

Exhibit 17

Exhibit 18

Exhibit 19
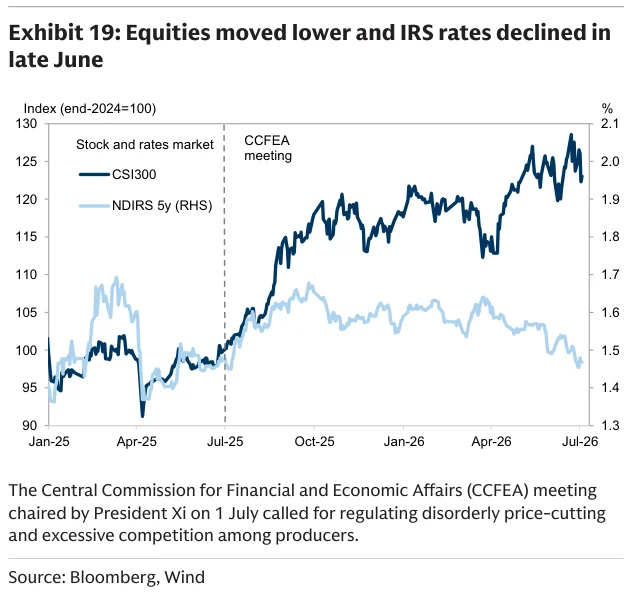
Exhibit 20

Exhibit 21

Exhibit 22

Exhibit 23
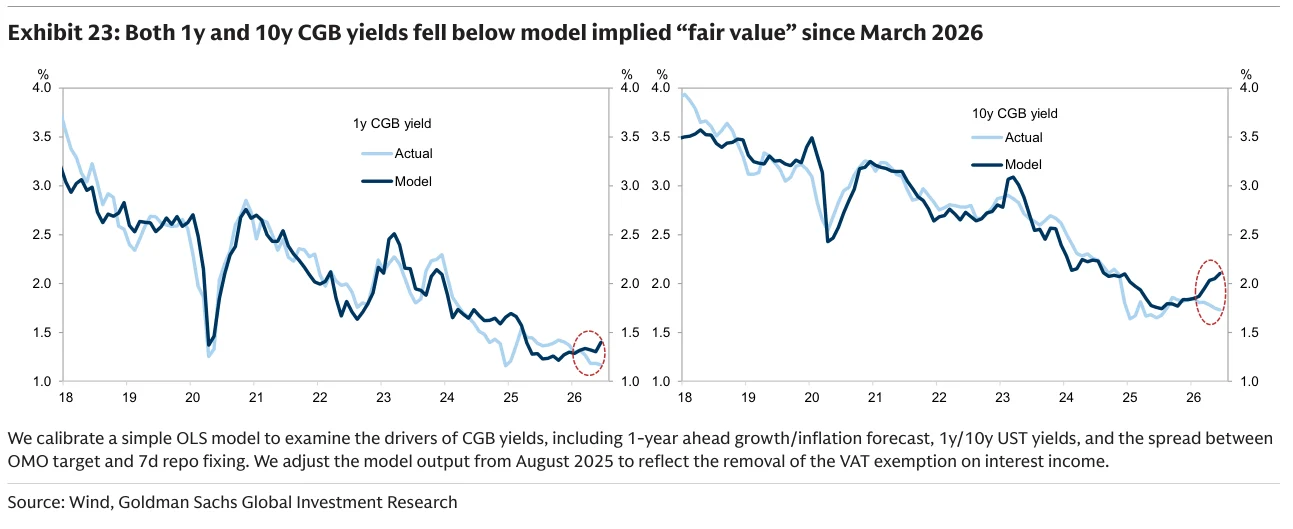
Exhibit 24

Exhibit 25

Exhibit 26

Exhibit 27

Exhibit 28

Exhibit 29

Exhibit 30

Exhibit 31

Exhibit 32

Exhibit 33
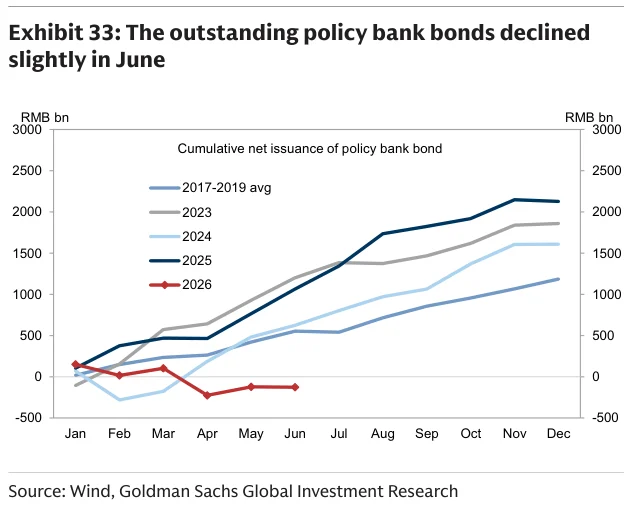
Exhibit 34

Exhibit 35

Exhibit 36

Exhibit 37

Exhibit 38

Exhibit 39
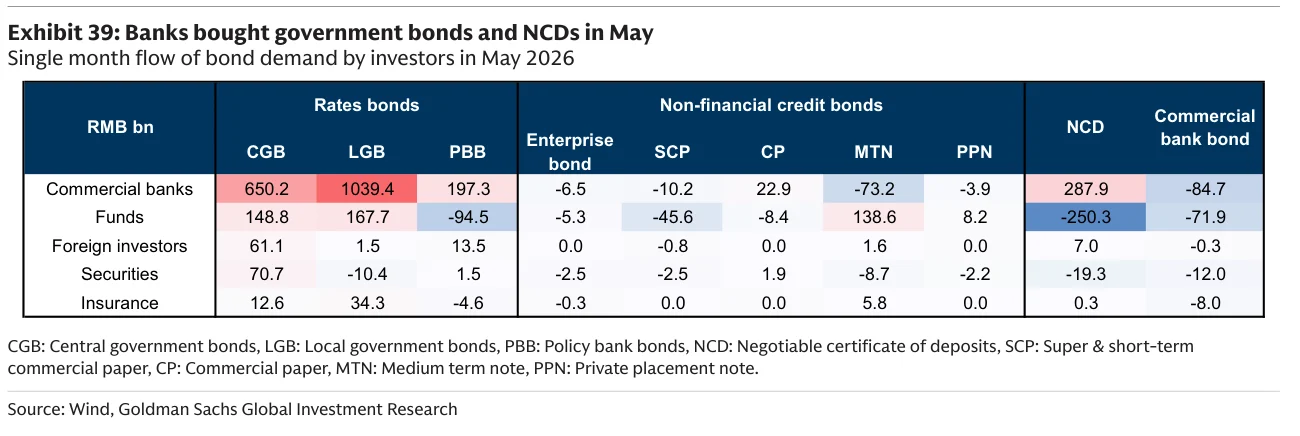
Exhibit 40
