JPMorgan: Netflix Inc — Focus on Engagement, Content Quality, and Revenue Growth; Overweight Rating Maintained
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
Key Views
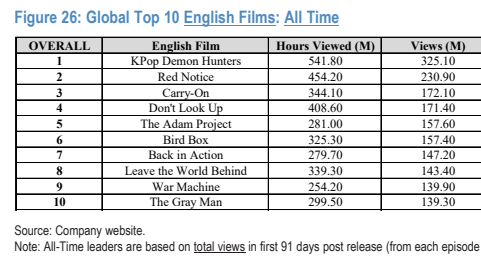
JPMorgan argues that third-party engagement data understates underlying trends, noting Netflix's internal quality engagement metrics hit record highs in the first quarter. With over 325 million subscribers, the correlation between engagement and revenue growth has weakened; pricing and advertising now provide incremental levers. The U.S. price increase is expected to generate approximately $1.7 billion in annualized revenue upside, contributing roughly 250 basis points to 2026 growth. Advertising revenue should roughly double to about $3 billion. Global connected-TV household penetration remains below 45%, supporting the long-term target of one billion viewers.
Outlook
JPMorgan projects 2026 revenue growth of 13% at constant currency (company guidance: 11–13%), an operating margin of 31.7%, and free cash flow of $12.7 billion. The second half should see expense growth slow to roughly 7%, driving operating profit growth above 30%. The 2025–2028 CAGR outlook includes constant-currency revenue at 12%, operating profit at 21%, GAAP EPS at 24%, and free cash flow at 23%.
Recommended Securities
- Netflix (NFLX US): Overweight; target price $118.
Key exhibits
Exhibit 1

Exhibit 2

Exhibit 3
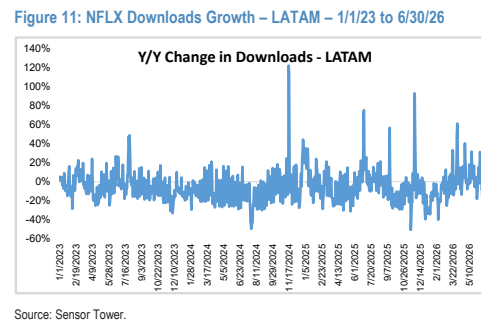
Exhibit 4
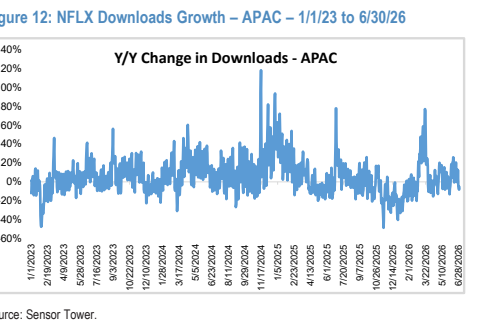
Exhibit 5
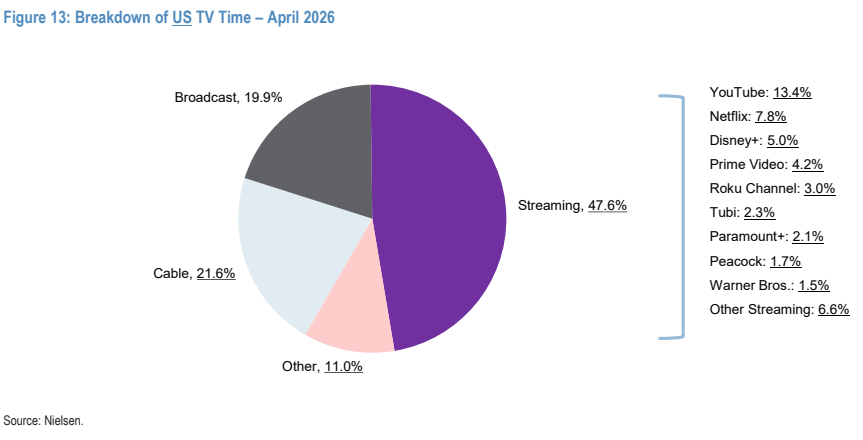
Exhibit 6
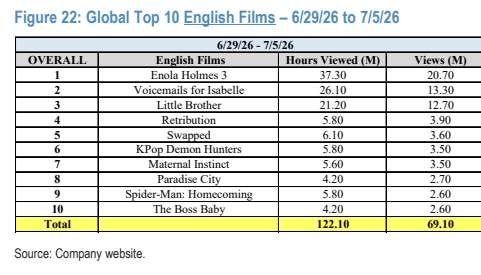
Exhibit 7
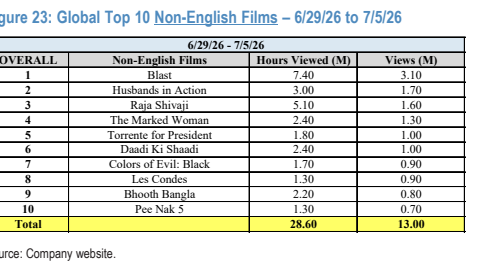
Exhibit 8