Goldman Sachs on Air Liquide: Updating Estimates Ahead of 2Q26
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
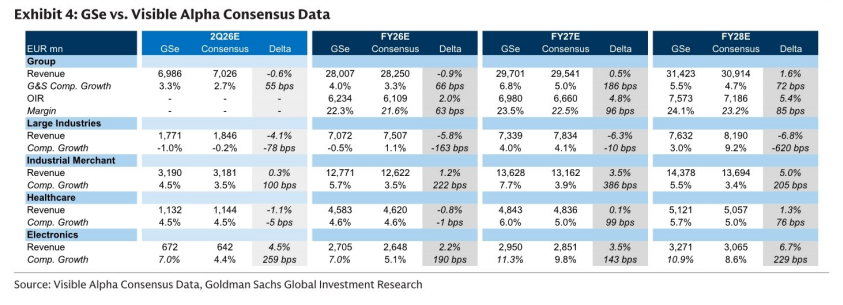
Goldman Sachs has made minor adjustments to its Air Liquide (AIRP.PA) forecasts ahead of the company's second-quarter 2026 results on July 28, maintaining its Buy rating and a target price of €179. Analysts anticipate a roughly 1% foreign exchange headwind for 2Q26, offset by a 1% positive impact from energy pass-through. The full-year 2026 operating income recurring (OIR) estimate was nudged up 0.4% to €6,234 million, while the 2027 forecast rose 0.8% to €6,980 million.
However, the firm trimmed its gas and services organic sales growth (OSG) estimate for 2026 from 4.7% to 4.0%, and for 2Q26 from 3.9% to 3.3%. This reduction is primarily driven by lower comparable growth expectations in industrial merchandising, which was cut from 7.6% to 5.7%. Volumes are projected to remain broadly stable with a slight recovery in the second half, supported by improving pricing.
Large industries remain sluggish with a roughly 1% comparable decline in 2Q, though a slight improvement is expected later in the year due to steel furnace restarts. Conversely, the electronics sector's 2Q comparable growth was raised to 7.0% from 6.0% on easing equipment comparables. Goldman Sachs remains more optimistic than Visible Alpha consensus on organic growth and OIR, driven by industrial pricing and carrier gas momentum.
Key exhibits
Exhibit 1
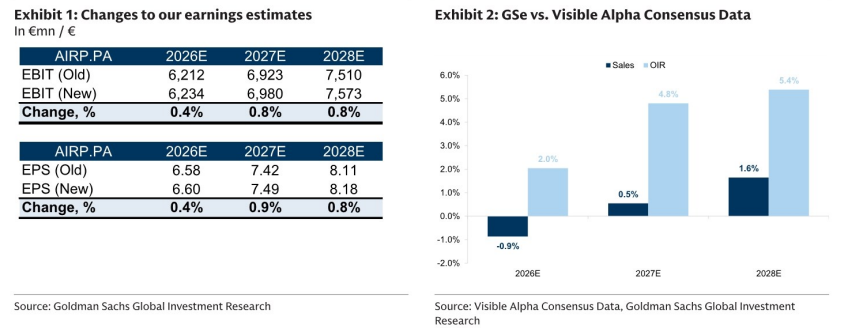
Exhibit 2
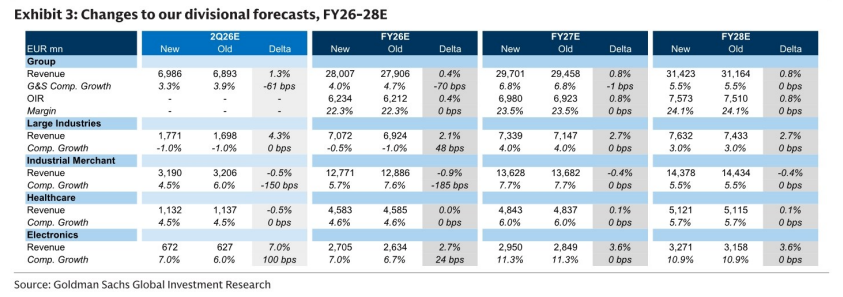
Exhibit 3