Goldman Sachs China Consumer Staples — Pork: 3Q26 Preview — Operating Profit Remains Weak Amid Continued Pressure from Chinese and International Operations
Summaries are public. PDF access requires an active membership; all members have the same access. Sign in
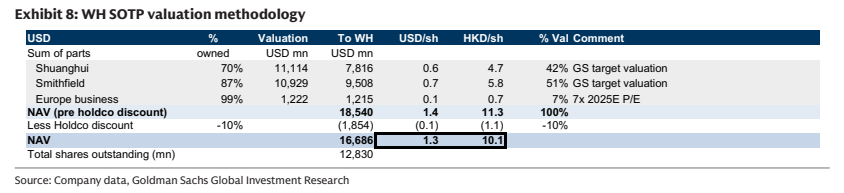
Following September's cut to US guidance and ensuing downgrades, Goldman Sachs expects WH Group's 3Q26 operating profit to decline near 30% year-on-year, worse than 2Q26's −11%, with pressure across China, the US and Europe. China (Shuanghui) OP is seen −8% in USD terms (−13% in RMB): packaged-meat volumes roughly flat (+0.5%), per-ton profit down ~10% to Rmb4,674/ton, and hog-farming losses similar to 2Q26. US OP is forecast −46% to US$170mn, at the high end of management's US$115–175mn guidance (implying −44% to −63%), with US packaged-meat OP +6%; Europe likely remains loss-making on hog-price pressure. For 4Q26, China OP should return to low-single-digit growth, but overseas remains the key watch item—futures imply 4Q26 hog prices and mixed-feed costs of −16%/+16% YoY, and US mixed-feed costs surge 15% YoY from 3Q26. GS trimmed WH Group/Shuanghui 3Q–4Q26 net income by 1–4%; WH Group 2026–28E underlying NPAT cut 1.6%/2.7%/2.5%; Shuanghui recurring NPAT cut 3.7%/2.5%/2.7%. Ratings unchanged: WH Group Buy, TP HK$10.1 (SOTP: Shuanghui 42%, Smithfield 51%, Europe 7%, 10% holding discount); Shuanghui Neutral, TP Rmb25.0 (17X 2026E P/E).
Key exhibits
Exhibit 1
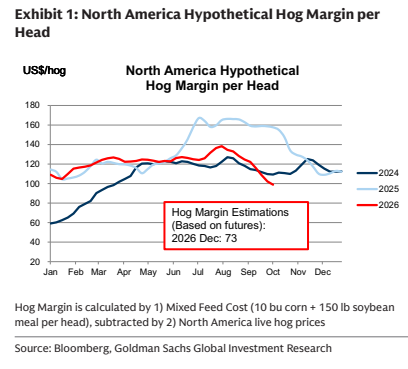
Exhibit 2
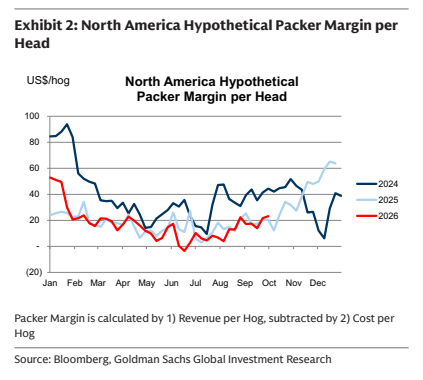
Exhibit 3
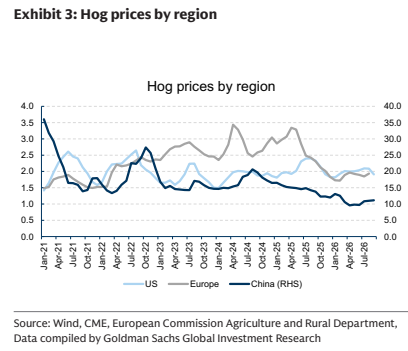
Exhibit 4
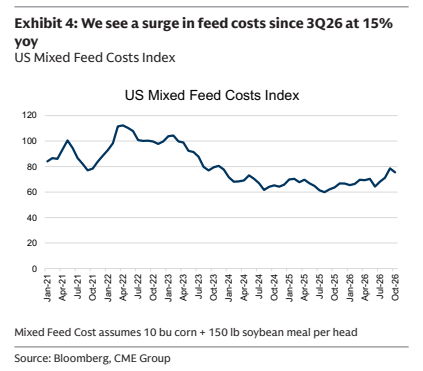
Exhibit 5